


Rogers (ROG) Faces A Valuation Test After Argus Cuts Its Price Target
Argus cut its price target on Rogers (ROG) to US$122, while the stock closed at US$125.63 on 14 November 2026. That small gap immediately raises questions about upside, downside, and timing.
Over the past year, Rogers has given investors a 60.34% total shareholder return, even as the share price has recently cooled with a 13.92% decline over 90 days and a 5.80% drop over 30 days. This suggests strong longer term momentum that has started to fade in the short term as expectations and perceived risks reset around the current US$125.63 level.
Compare Rogers with a curated group of materials and advanced electronics peers that currently screen as 34 high quality undervalued stocks based on quality and pricing signals.
Rogers appears to be a solid specialist in engineered materials, yet the share price has just slipped below a recent US$122 target. Is this still a quality business offered at a sensible valuation today?
Most Popular Narrative: 35% Undervalued
On the analyst consensus Narrative on Simply Wall St, Rogers screens with a fair value of $193.33 versus the latest $125.63 close. This implies a sizeable valuation gap that the narrative links to specific growth and margin targets rather than vague optimism.
Expansion into AI data center connectivity and cooling through next generation PTFE-based laminates that already meet and exceed M9 performance requirements, with a path to M10, and direct-to-chip microchannel coolers now being prototyped with several major AI chip and data center customers, alongside management’s expectation that these adjacencies contribute meaningfully to roughly US$450 million of targeted incremental revenue by 2030, provides a potential new leg of growth and margin mix improvement.
See why 2 investors see Rogers as 35% undervalued.
Result: Fair Value of $193.33 (UNDERVALUED)
Still, the Rogers narrative leans heavily on hitting ambitious margin targets while ramping the underutilized ceramic substrate plant, and any stumble on either front could quickly challenge that 35% undervalued story.
Find out about the key risks to this Rogers narrative.
Another View: Rogers Looks Expensive On Earnings
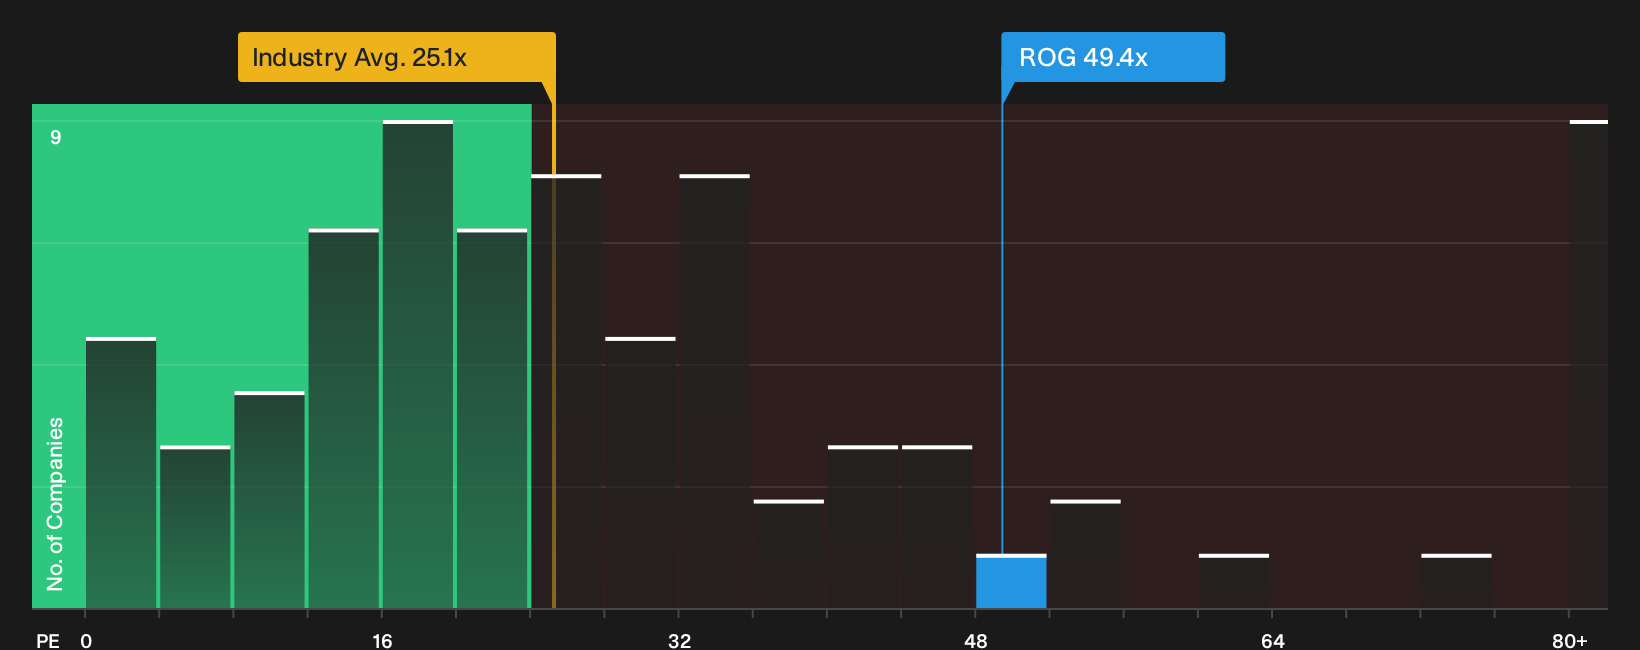
Rogers may screen as 35% undervalued on the analyst fair value of $193.33, yet the current P/E of 49.4x tells a very different story. That multiple sits well above the US Electronic industry at 25.2x, the peer average at 36.6x, and even the 30.8x fair ratio the market could move toward. This raises a simple question for investors: how much execution risk are you really paying for here?
For readers weighing this richer earnings multiple against the bullish narrative, it can help to see how the valuation stacks up on detailed numbers, not just headlines, through the See what the numbers say about this price — find out in our valuation breakdown..
Here is how that P/E compares visually with sector benchmarks in the latest Simply Wall St data, via the
Next Steps
With both bullish and cautious signals on the table for Rogers, it helps to move fast, review the underlying data, and pressure test the optimism for yourself. To see what investors are currently excited about in the numbers, start with the 3 key rewards.
Looking for more Rogers investment ideas?
If Rogers has sharpened your appetite for opportunities, do not stop here. The right shortlist can change your next move entirely, and waiting could mean missing the setups already forming.
- Target financial resilience first by scanning a list of solid balance sheet and fundamentals (24 results). This can help you focus on businesses with sturdier fundamentals before the crowd catches on.
- Hunt for mispriced quality through the 19 high quality undiscovered gems and give yourself a shot at finding strong companies that many portfolios still overlook.
- Dial down portfolio shocks by filtering for a 29 resilient stocks with low risk scores so you can focus on steadier performers while others react late to volatility.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com