


What Cloetta (OM:CLA B) Earnings Growth Means For Shareholders
- Cloetta reported third quarter 2026 sales of SEK 2,233 million and net income of SEK 246 million, with basic EPS from continuing operations at SEK 0.87, and nine month sales of SEK 6,432 million with net income of SEK 673 million.
- The combination of higher sales and net income for both the quarter and year to date may indicate effective cost control and operating efficiency in Cloetta’s confectionery portfolio.
- The next step is to examine how Cloetta's investment narrative is influenced by this quarterly earnings profile and higher net income.
Scan beyond Cloetta's latest earnings and line up other confectionery and consumer staples stocks with resilient cash generation using our hand picked 196 high quality undervalued stocks.
Cloetta Investment Narrative Recap
Cloetta relies on steady confectionery demand, strong super brands and a mix of packaged products and pick and mix to keep cash generation resilient. The latest quarter, with SEK 2,233 million in sales and SEK 246 million in net income, supports that story but does not radically change it. For the near term, the key catalyst is still execution on volume led growth, as pricing flexibility may be limited by pressure on food prices.
The biggest operational risk remains margin pressure if commodity costs, wages or required marketing spend stay elevated while price increases become harder to push through. Reliance on seasonal products and concepts like Lakerol MORE and Malaco Foamy Monkey also keeps Cloetta exposed to shifts in consumer tastes, so sustained demand across those formats matters more than a single strong quarter.
The analyst consensus Narrative on Simply Wall St highlights management’s focus on 10 core super brands in five main markets, backed by cost savings of SEK 60 million to SEK 70 million a year. The recent earnings release, with nine month net income of SEK 673 million and basic EPS from continuing operations of SEK 2.37, gives fresh data on how efficiently that brand focus is converting into profit today.
Analysts in that Narrative point to confectionery demand being relatively stable and to earnings growth forecasts of 4.56% a year, while also flagging that long term margin ambitions rely on both mix and fixed cost absorption. The third quarter figures help you gauge whether Cloetta is tracking toward those goals or if continued pressure on pricing power and input costs could keep branded margins below the pre pandemic ambition around 15%.
Cloetta's narrative projects SEK 10.1b revenue and SEK 979.7 million earnings by 2029, which implies 5.4% yearly revenue growth and an earnings increase of about SEK 130.7 million from SEK 849.0 million today.
Uncover why Cloetta's fair value indicates a 3% potential upside to its current price, which could narrow quickly.
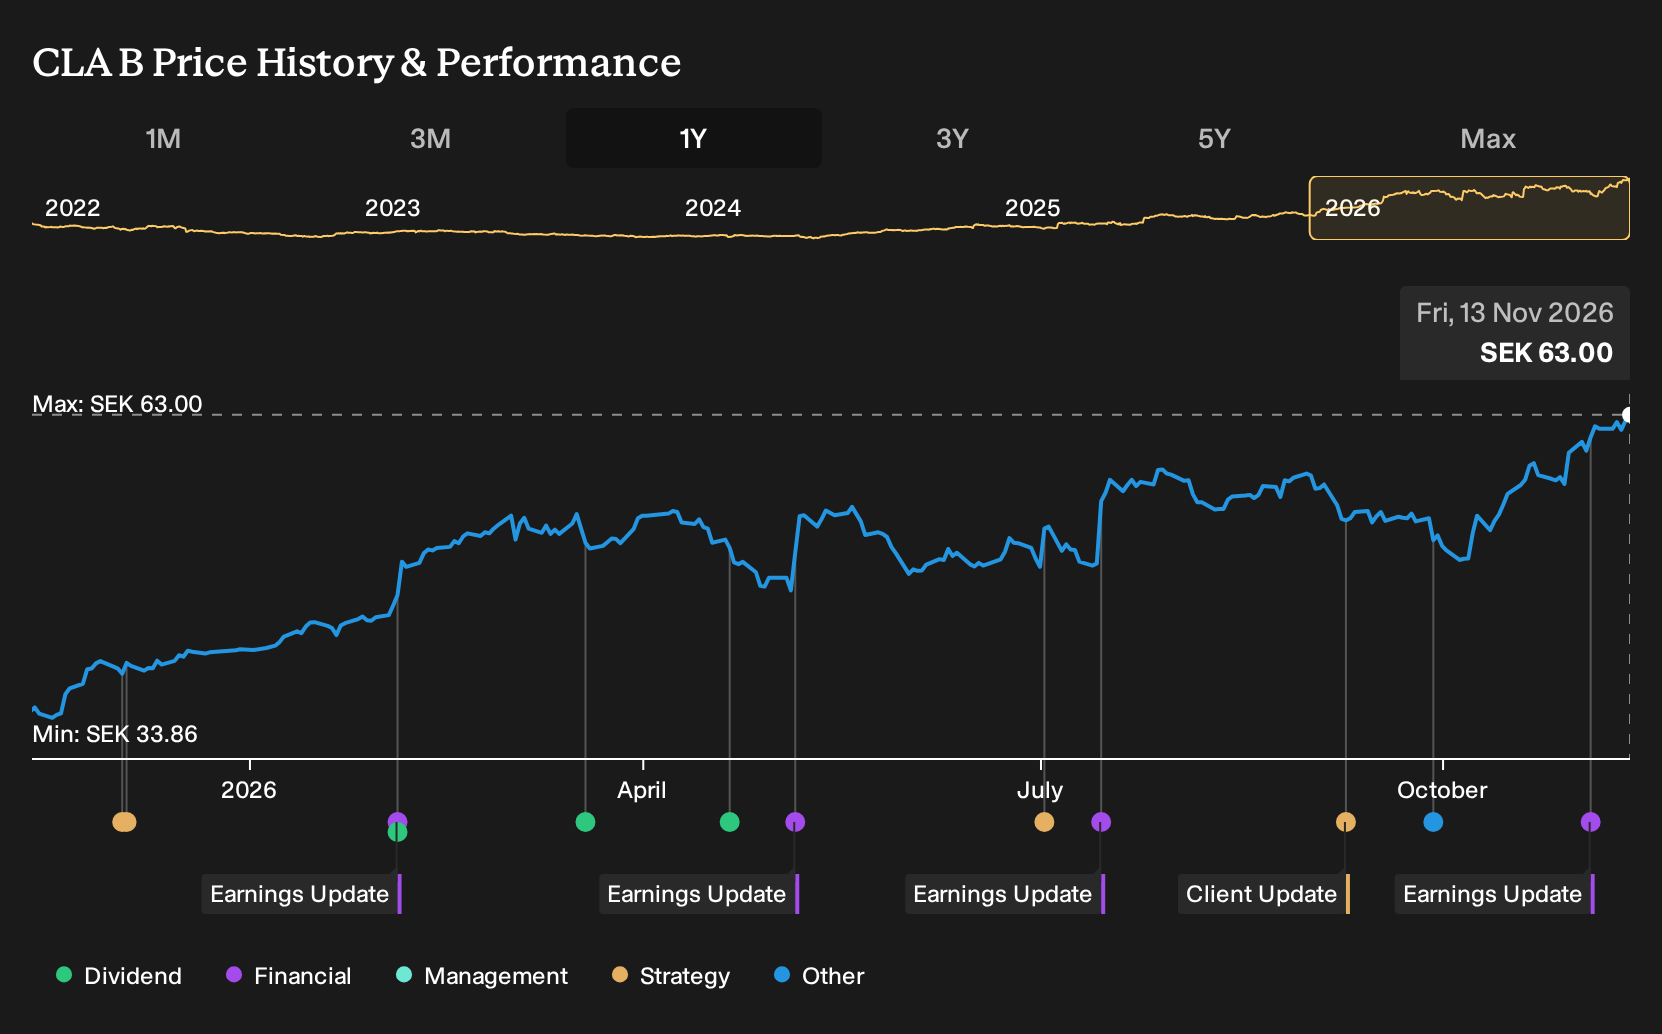
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community cluster between SEK 65 and about SEK 78.84, so retail investors already show a wide span on what Cloetta might be worth. Treat that spread as a prompt to stress test your own view against commodity cost risk, pricing pressure and expansion plans before deciding where you sit.
Explore 2 other Cloetta fair value estimates, including one that suggests it could be worth just SEK65.00.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Cloetta research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Cloetta. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cloetta's overall financial health at a glance.
Looking for more investment ideas beyond Cloetta?
Once you have a handle on Cloetta, it can help to widen the lens and see how it stacks up against other listed businesses with different strengths.
- If you want potential upside with strict quality filters, line up companies that combine healthy fundamentals and attractive pricing using our curated 568 high quality undiscovered gems.
- For income focused portfolios, compare Cloetta's payout profile with a hand picked set of resilient payers through the 221 dividend fortresses.
- If capital preservation sits high on your priorities, scan a carefully filtered 207 resilient stocks with low risk scores to see which businesses match your risk tolerance.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com