


What Lincoln Electric Buyers Were Betting On
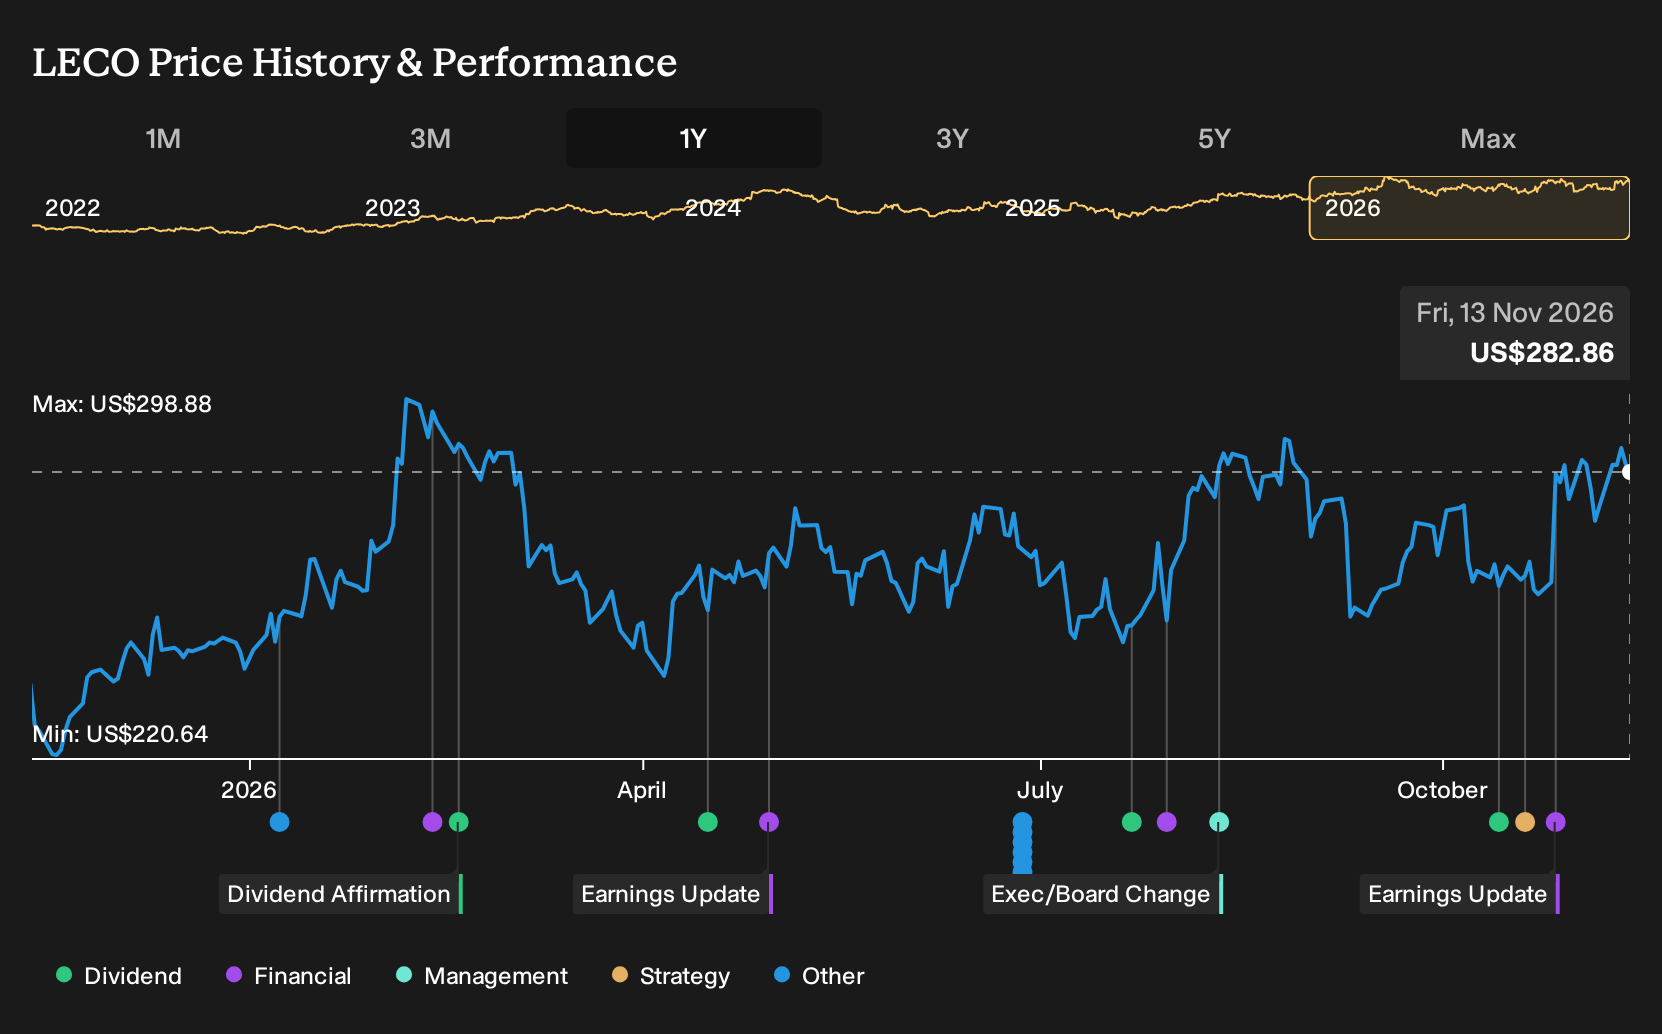
Holding Lincoln Electric over the past year would have returned 26.7%, including dividends. That outcome looks clean on a chart. It did not feel that simple on 13 November 2025, when bulls were talking up accelerating automation demand and reshoring, while bears warned that reliance on traditional welding, cyclicality and rich P/E expectations could strain future margins. If you were weighing a purchase then, which side of Lincoln Electric’s trade-offs would have mattered most to you?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
This theme extends beyond Lincoln Electric. See which of 88 robotics and automation stocks may still merit a closer look.
The Two Lincoln Electric Stories Investors Had To Choose Between
The shares cost US$227 at the start of the period, so any view on Lincoln Electric had to begin with what that price already assumed.
The bullish narrative saw fair value at US$256, or 13% above the start price, built on assumptions of 5.4% annual revenue growth, a 13.8% profit margin and a future P/E of 24.9x over three years.
The bearish case pointed to fair value of US$185, or 19% below the start price, emphasizing reliance on traditional welding and highlighting the risk that slower expansion into areas like additive manufacturing could affect future margins.
What The Results Changed For The Lincoln Electric Debate
Lincoln Electric’s Q3 2026 update gave bulls some backing. Revenue moved from US$1.06b in Q3 2025 to US$1.22b and net income also rose. Net margin edged up from 11.6% to 11.8%, which leaned toward the optimistic case that assumed resilient profitability, although only by a small amount, so the evidence cut both ways rather than settling the argument.
The earlier split between bulls and bears really hinged on whether margins could hold up. When you assess another industrial, track not just sales and earnings but also the direction of net margin in relation to the story you are being given about pricing power and mix.
What Lincoln Electric’s Price Already Assumes Today
Lincoln Electric now trades at US$283, after a 26.7% gain over the past year. The bearish analyst Narrative on Simply Wall St sees Fair Value below that quote, framing today’s tag as already baking in a lot of execution progress.
The Narrative centers on whether automation, efficiency programs and Asia expansion can all deliver as planned. For today’s price to hold up, a buyer would need to judge that margin targets remain achievable even if inflation and traditional welding cycles stay challenging.
"The current valuation implies that Lincoln Electric shares already price in continued mid single to high single digit organic growth, high 20s incremental margins, and successful bolt on M&A execution, which leaves limited room for disappointment if these ambitions are not fully achieved."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Where Lincoln Electric’s Power Leads Next
Following Lincoln Electric takes you straight into factories, shipyards and data centers. The obvious story is robots and welding. The less obvious one sits in the walls.
All that automation runs on electricity that must arrive clean, stable and cooled. Another industrial specialist focuses on routing that power and controlling heat inside huge facilities.
Its equipment helps convert grid energy, manage fault risks and move heat away from critical hardware. Without that plumbing, high powered sites face hard physical limits.
If you are mapping opportunities around Lincoln Electric, this quieter electrical and thermal backbone may deserve its own line on your watchlist.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 46% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com