


Astrana Health (ASTH) Stock Looks Reasonable Despite Its 72% Five Year Fall
Astrana Health has delivered a sharp long term setback for shareholders, even as the business has been reporting record earnings figures and new commercial deals. That mix of a troubled 5 year share price record and stronger recent profit headlines raises a simple question for you as an investor. Is the current valuation really supported by what the company earns today.
- The share price has fallen 72.0% over 5 years, which puts a lot of pressure on the idea that Astrana Health's current market value lines up neatly with its earnings power.
- Recent earnings and partnership announcements suggest the business may support different expectations for profitability and cash generation than the share price history alone might imply.
- The analysts covering Astrana Health have run their own numbers. See what analysts think Astrana Health's shares could be worth.
The issue now is whether Astrana Health's recent earnings are strong enough to justify the price investors are being asked to pay for the stock today.
If you want to test this same earnings based valuation question beyond Astrana Health, you can scan a wider field of companies through the 34 high quality undervalued stocks
Is Astrana Health Still Cheap on Earnings?
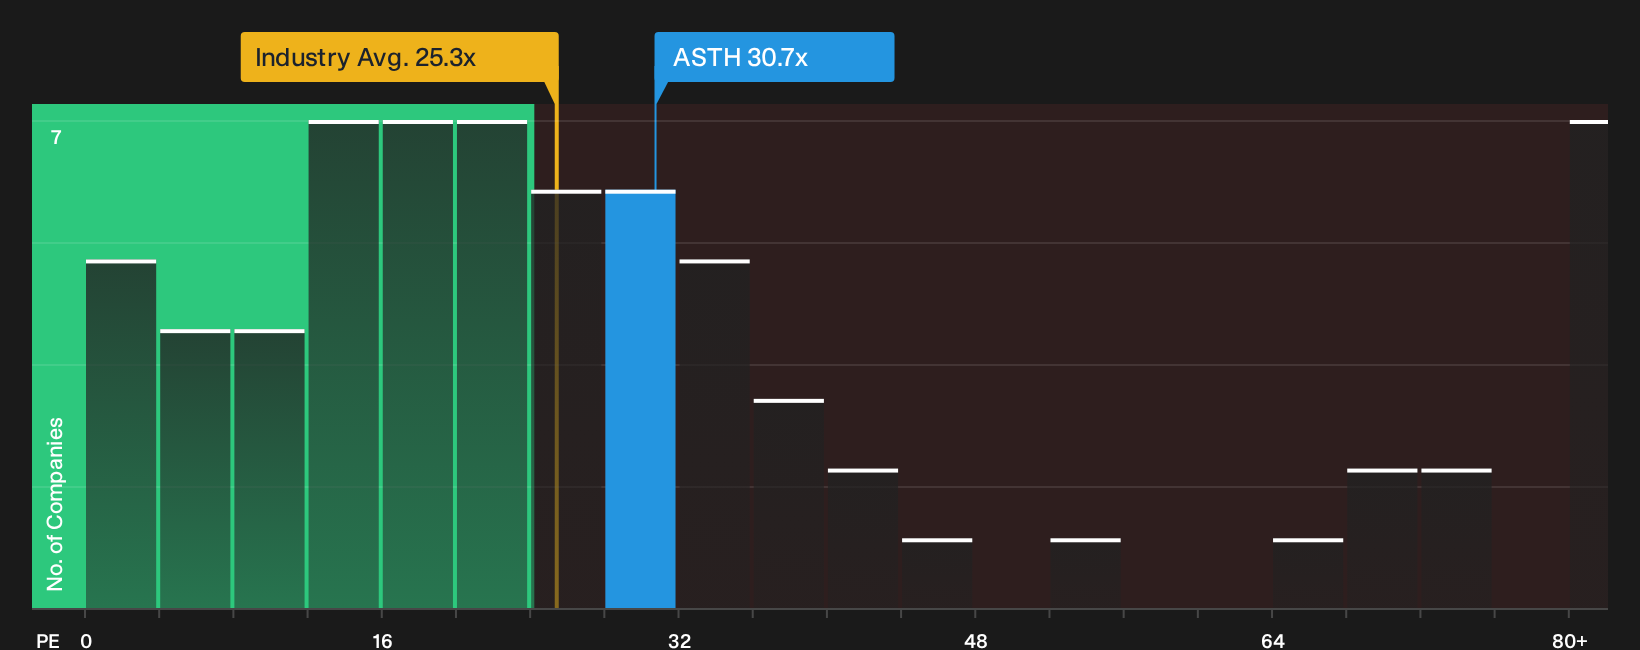
A P/E lens suits Astrana Health because earnings are now a key focus after its recent profit headlines. The stock trades on a P/E of about 30.7x, which sits above the broader Healthcare industry average of 25.3x but well below the peer group average near 65.6x. Based on the tailored fair multiple that reflects Astrana Health's own growth profile, margins, size and risk, the current P/E sits below where that model would expect the shares to trade. This points to the stock screening as undervalued on this yardstick.
Because the latest reported results showed record Q3 2026 earnings, the P/E is anchored to a profit base that has recently strengthened, yet the valuation still prices Astrana Health at a discount to that fair multiple framework. For you as an investor, the key judgment is whether those earnings and the new payer partnerships can be sustained and converted into durable cash generation over time, since that will determine whether this P/E level really looks like value or not. Explore the numbers behind Astrana Health's P/E valuation.
The Astrana Health Narrative: What Would Justify Today's Price?
Astrana Health's Narratives on Simply Wall St pick up where the P/E puzzle leaves off and spell out what kind of future growth, margins and earnings profile would need to hold for the shares to trade meaningfully higher or lower than today. Each scenario treats Astrana Health's implied fair value as a thesis about the business that you can revisit over time, rather than a one off snapshot.
One of the top narratives on Astrana Health: 29% undervalued
This Narrative is the bearish analyst Narrative on Simply Wall St, built on the most pessimistic analyst price target and forecasts, not one person's view.
"The numbers imply that Astrana Health's share price reflects a business where strong free cash flow conversion, rising adjusted EBITDA guidance, higher full-risk exposure and faster deleveraging have not yet been fully credited..."
Discover why this Narrative puts Astrana Health at 29% undervalued.
One more Astrana Health check before you weigh the price
Valuation only tells part of the story for Astrana Health, because the research screen has also picked up specific risk checks that deserve your attention before you form a view. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com