


Invesco (IVZ) Could Be 18% Undervalued As New ETFs Feed Growth Hopes
Invesco (IVZ) has put its quantitative capabilities on display with the launch of four systematic active ETFs that apply factor research and rules-based portfolio construction to broad equity benchmarks across U.S., developed international, and emerging markets.
Recent trading tells a mixed story for Invesco. The share price is up 6.8% over the past week and 2.6% over the past month, yet it is down 11.2% over the last 90 days. At the same time, total shareholder return of 26.7% over one year and 136% over three years points to strong longer term momentum. Recent ETF launches now feed into a broader narrative of product expansion, capital deployment and shifting perceptions of risk and opportunity around the stock.
Compare Invesco's factor-led push with other asset managers by scanning 34 high quality undervalued stocks that may be setting up for their own product-driven breakouts.
Invesco trades at a double discount, both to analyst targets and to an implied intrinsic value, even after the recent ETF-driven bounce. Is the market being prudently wary, or is it mispricing that caution?
Most Popular Narrative: 18% Undervalued
Invesco's last close at $28.92 sits below the $35.07 fair value in the analyst consensus Narrative on Simply Wall St. This blends revenue and earnings forecasts with a single discounted cash flow framework and ties that to an explicit view on future margins and capital returns.
The main requirement for this approach is that the shift toward lower-fee products, balance sheet recapitalization, and technology spending translates into sustained organic inflows and margins that support higher shareholder payouts.
The current valuation, according to this narrative, implies the share price does not fully reflect the combination of record AUM, consistent net long-term inflows, expanding operating margins, and planned EPS accretion from preferred stock redemptions, and therefore characterizes Invesco as undervalued with a positive outlook.
See why 21 investors see Invesco as 18% undervalued.
Result: Fair Value of $35.07 (UNDERVALUED)
Still, pressure on lower fee ETFs and SMAs, along with the fee cuts plus capital support around Core Real Estate USA, could easily challenge that Invesco optimism.
Find out about the key risks to this Invesco narrative.
Another View: Invesco on Sales-Based Valuation
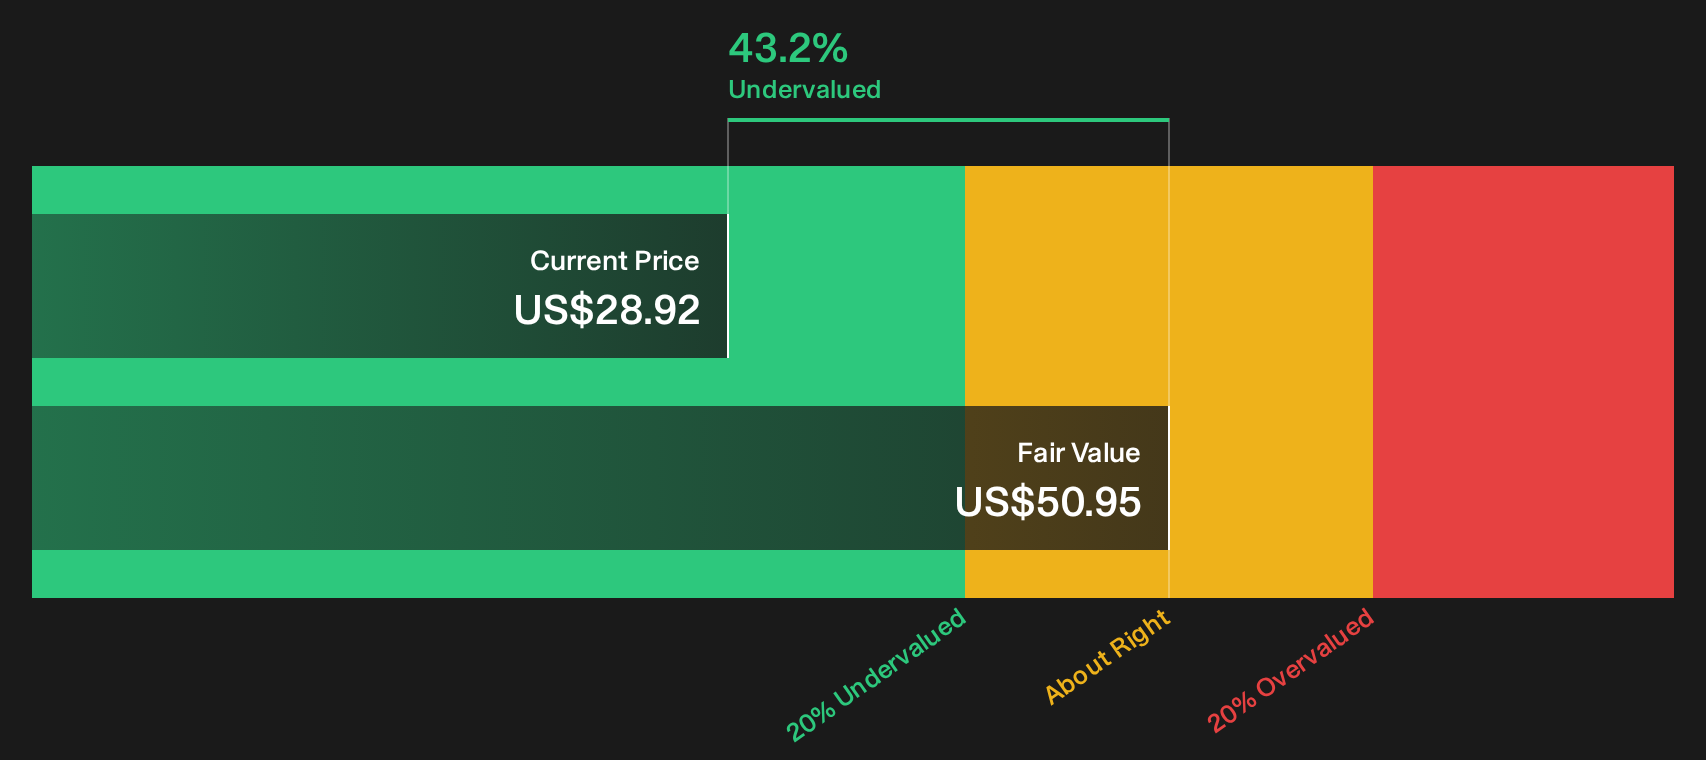
The DCF work suggests Invesco is attractive, with the stock trading about 43.2% below an estimated future cash flow value of $50.95. Yet on P/S, the picture is tighter. The current 1.8x multiple is only slightly above a fair ratio of 1.7x, which points to limited margin for error if sentiment turns.
To see how this cash flow approach is built, and where the moving parts could surprise, Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals so far on Invesco, or a clear skew toward opportunity? Act quickly and pressure test the full picture for yourself by weighing 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Invesco?
If Invesco has caught your attention, do not stop there. Use the Simply Wall St screener to line up a broader watchlist of potential opportunities.
- Target income resilience by scanning companies that show up as 6 dividend fortresses and see which payouts might complement your existing positions.
- Hunt for mispriced quality by reviewing the 19 high quality undiscovered gems before fresh capital crowds into the same opportunities.
- Dial down portfolio stress by checking out the 29 resilient stocks with low risk scores so you are not the one chasing safety after everyone else moves first.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com