


A2A (BIT:A2A) Faces A Valuation Test Following Mixed Nine Month Earnings
Earnings trigger reshapes the conversation around A2A stock
A2A (BIT:A2A) just posted nine month 2026 results that show higher reported sales and revenue, while net income moved the other way. This combination tends to sharpen investor focus.
A2A's latest earnings drop into a mixed price picture, with the 1 day share price return of 0.74% only partly offsetting a 7 day share price decline of 5.43% and a 30 day share price fall of 3.60% as investors absorb higher revenue alongside lower profit. Yet the stock still carries some longer term credit with the market, with the 3 year total shareholder return of 36.96% and 5 year total shareholder return of 62.98% indicating that holders who stayed the course have been rewarded even as recent momentum has faded.
Scan beyond A2A and compare how other utility and infrastructure players with stronger pricing power or a steadier earnings trend perform across our curated list of solid balance sheet and fundamentals (198 results).
Bulls point to A2A's revenue strength and long run returns. Bears flag the softer profit and weaker recent share price. Which side do the current valuation markers support?
Most Popular Narrative: 20% Undervalued
A2A last closed at €2.30, while the analyst consensus Narrative on Simply Wall St assigns a fair value of €2.88 based on detailed earnings and cash flow assumptions, which sets up a clear valuation gap for investors to interrogate.
Ongoing high investment capacity, reflected in €718m of CapEx in H1 2026 with development CapEx up 17% and about 65% cash conversion from €2b of operating cash flow in 2025 while maintaining leverage in the range of 2.4x to 2.6x and a cost of debt near 2.7%, provides room for A2A to keep funding growth projects that may affect future earnings and net margins.
See why 22 investors see A2A as 20% undervalued.
Result: Fair Value of €2.88 (UNDERVALUED)
Still, the A2A narrative depends on key swing factors, including future regulatory decisions on concessions and the heavy CapEx bill that could lift funding costs.
Find out about the key risks to this A2A narrative.
Another view on A2A valuation
Analysts frame A2A as about 20% undervalued at €2.88, yet Simply Wall St's DCF model points to a future cash flow value of €2.15, which sits below the current €2.30 share price. That gap puts the spotlight on whose assumptions about cash generation you trust more.
For investors who want to unpack the moving parts behind this discounted cash flow view in more detail, Look into how the SWS DCF model arrives at its fair value..
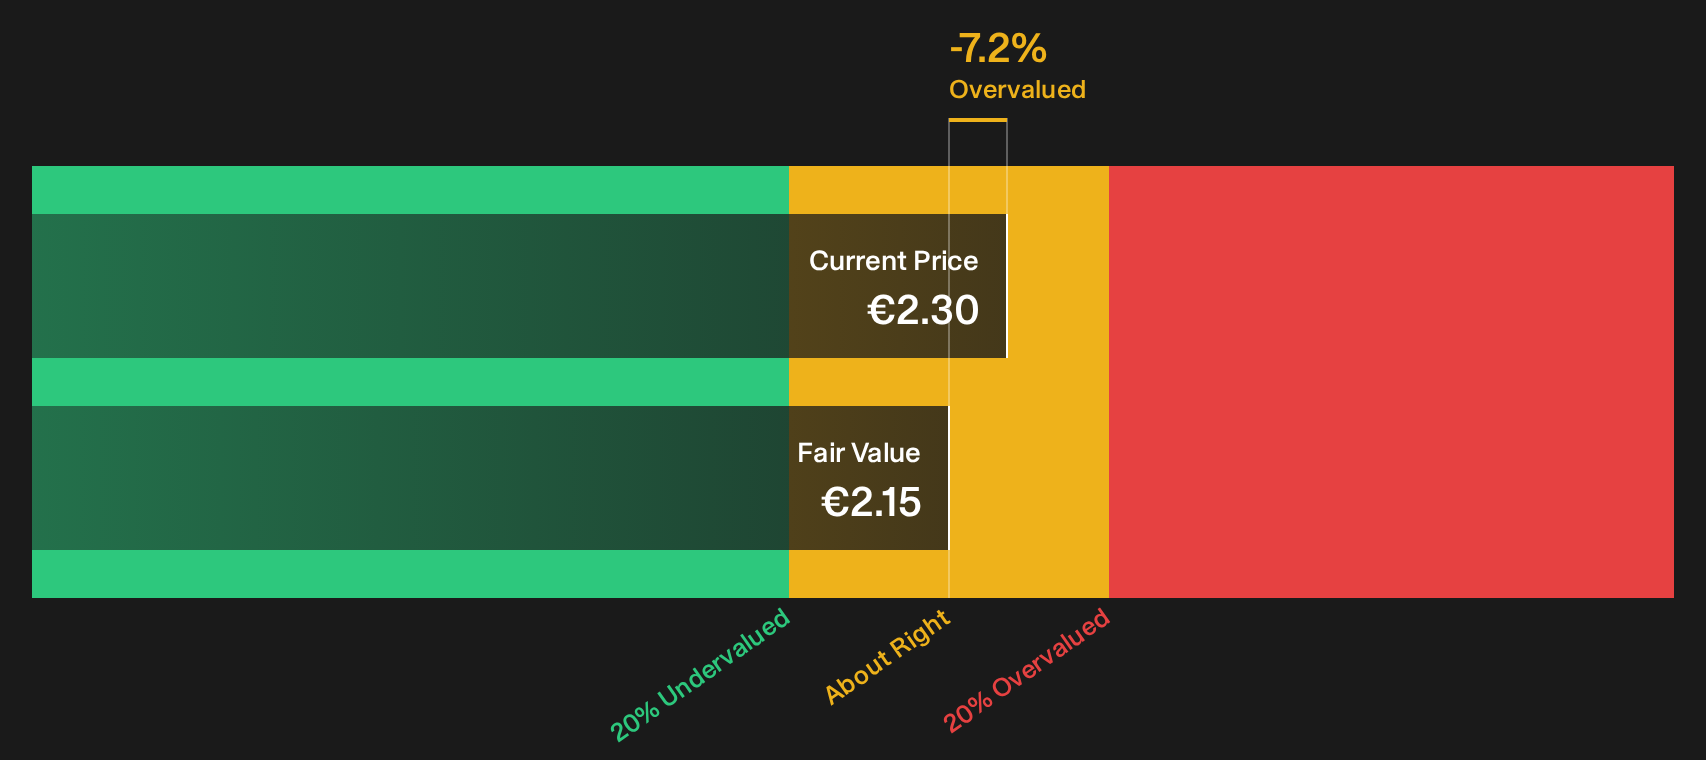
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out A2A for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 196 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages around A2A can feel murky, so move quickly, review the full data for yourself, and weigh both sides of the story with 3 key rewards and 3 important warning signs
Looking for more investment ideas beyond A2A?
Do not stop your research with A2A. Broaden your opportunity set by comparing different business profiles and giving yourself more options before committing fresh capital.
- Target quality at a discount by scanning companies that combine resilient fundamentals with appealing prices through the 196 high quality undervalued stocks.
- Prioritise staying power and capital preservation by assessing businesses that score well on balance sheet strength using the 207 resilient stocks with low risk scores.
- Hunt for promising up-and-comers with strong financial footing by reviewing a curated pool of 568 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com