


Buenaventura (BVN) Stock May Be Below Fair Value As 2026 Investor Day Unfolds
Compañía de Minas BuenaventuraA has delivered a very strong 5 year share price run, yet recent weakness has investors asking whether the current valuation is still backed by its earnings power. With the stock pulling back in the short term while the business lays out long term plans, the question is how much of its earnings story is already reflected in today's price.
- Compañía de Minas BuenaventuraA has returned about 292.5% over 5 years, which puts real pressure on the earnings profile to justify how far the share price has come.
- The recent 2026 Investor Day highlighted plans to lift gold, silver and copper production through targeted capital spending, which can shape future earnings through both higher volumes and the timing of cash flows.
- There is a second opinion on Compañía de Minas BuenaventuraA worth weighing. See what analysts think Compañía de Minas BuenaventuraA's shares could be worth.
The stock's next move may depend on whether Compañía de Minas BuenaventuraA's current price can be squared with what its earnings realistically support.
If you want context on whether Compañía de Minas BuenaventuraA's recent pullback and 5 year surge still line up with its earnings story, it helps to compare it with 34 high quality undervalued stocks.
Is Compañía de Minas BuenaventuraA Still Cheap on Earnings?
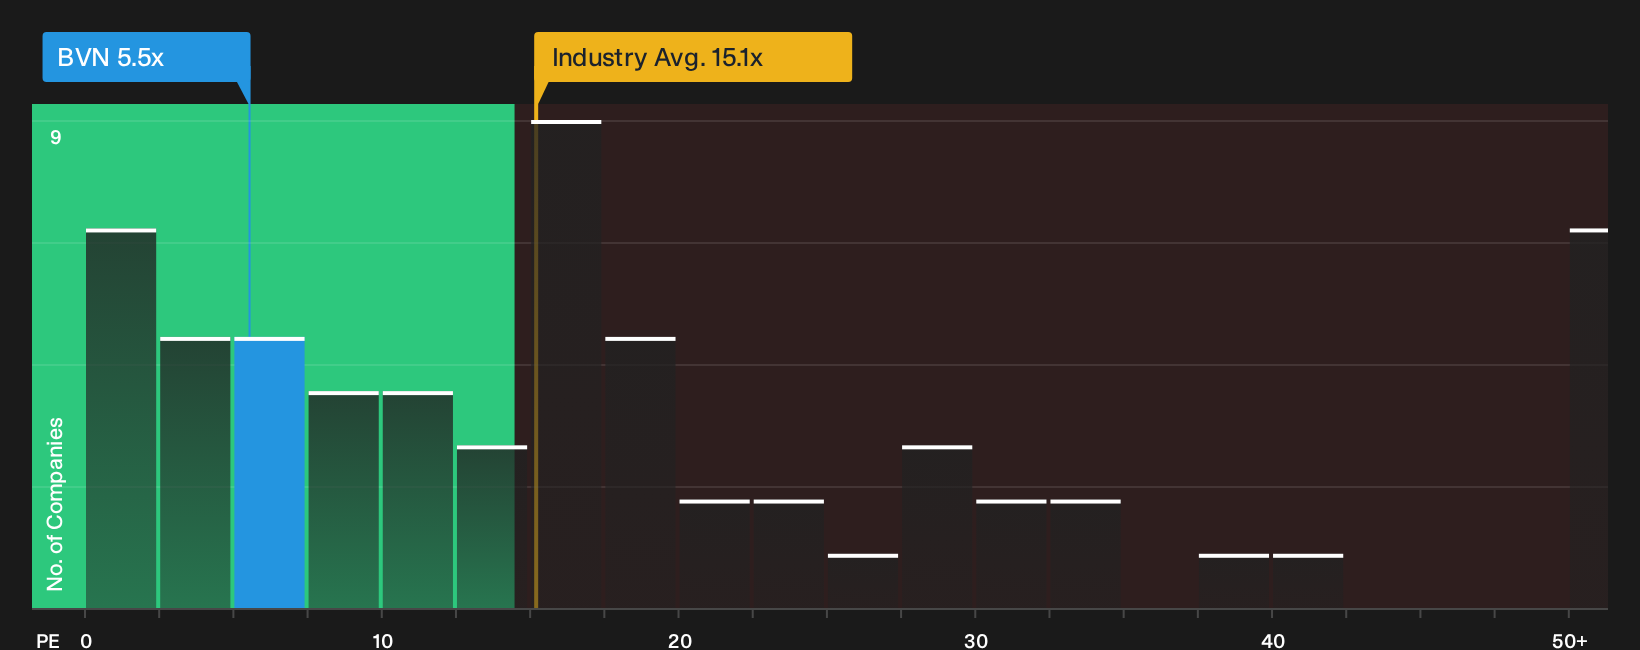
P/E suits Compañía de Minas BuenaventuraA because earnings are a key anchor for how investors judge a miner with multiple producing assets. The current P/E of 5.5x sits far below the Metals and Mining industry average of 15.1x and also trails the broader peer group at 32.7x. On the Fair Ratio framework, which estimates the kind of P/E that might fit the company’s earnings quality, scale and risk profile, the stock trades on the low side.
Because the 2026 Investor Day laid out multi year production plans, the current discount on P/E suggests the market is still cautious about how that outlook will translate into sustained profits. For you as a shareholder or potential investor, the gap between Compañía de Minas BuenaventuraA's earnings multiple and these benchmarks underlines that the market is not pricing it as a premium miner today, even after a strong 5 year share move. Explore the numbers behind Compañía de Minas BuenaventuraA's P/E valuation.
The Compañía de Minas BuenaventuraA Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E puzzle for Compañía de Minas BuenaventuraA leaves off by explaining which paths for future growth, margins and earnings would need to occur for the stock to be worth meaningfully more or less than it is today in the market. Each narrative links its number to a specific view on how growth, profitability and risk could change next, giving you a reference point you can revisit as new information emerges.
One of the top narratives on Compañía de Minas BuenaventuraA: 9% undervalued
This Narrative is the bearish analyst Narrative on Simply Wall St, built on the most pessimistic analyst price target and forecasts, not one person's view.
"The current valuation suggests the share price already reflects a fairly valued, bearish view in which strong recent revenue, EBITDA, net income and dividend figures offset rising costs..."
Discover why this Narrative puts Compañía de Minas BuenaventuraA at 9% undervalued.
One more angle on Compañía de Minas BuenaventuraA that could change the story
Valuation is only half the picture, because the track record and pay structure of the people steering Compañía de Minas BuenaventuraA can heavily influence how that earnings profile actually plays out. See who runs Compañía de Minas BuenaventuraA and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com