


Did Strong Nine Month Earnings Just Shift Kao's (TSE:4452) Investment Narrative?
- Kao Corporation reported earnings for the nine months ended September 30, 2026, with sales of ¥1,319,305 million and net income of ¥105,051 million, and basic EPS from continuing operations of ¥116.12.
- The combination of higher sales and net income for this nine month period points to firmer underlying demand and cost discipline across Kao's portfolio, from daily consumer products through to specialty chemicals.
- The next step is to assess how Kao's stronger nine month net income performance could influence the existing investment narrative around product mix.
Compare Kao's earnings momentum with a curated group of consumer-focused businesses by scanning the 18 high quality undervalued stocks that currently pair solid fundamentals with compressed expectations.
Kao Investment Narrative Recap
For Kao, the big picture you need to buy into is that premium consumer brands, higher value chemicals and disciplined product mix can keep doing the heavy lifting on profitability. The nine month earnings report, with higher sales, net income and EPS versus a year ago, indicates that execution is currently on track. The key short term swing factor remains how firmly consumer demand and specialty chemicals orders hold up into upcoming reporting periods.
Raw material costs and overseas competition still sit as the biggest operational threats. The analyst consensus Narrative on Simply Wall St highlights pressure from inputs such as naphtha, oils and fats, along with scrutiny of Kao’s palm oil supply chain. The latest earnings do not remove those risks, but they show management handling cost and mix sensitivities reasonably well so far.
The most relevant reference point for this earnings release is the earlier period data embedded in the analyst consensus Narrative on Simply Wall St, which reported Kao’s first half 2026 gross margin at 39.8% and identified gains in categories such as laundry detergents and sunscreens. The new nine month numbers allow for an assessment of whether that margin quality is being maintained as the year progresses.
When that prior context is lined up with the current JPY 1,319,305 million in nine month sales and JPY 105,051 million in net income, it offers a clearer read on whether Kao’s push into higher value products, derma and cosmetics, and semiconductor chemicals is translating into steadier earnings. That link between execution and margins, set against the backdrop of raw material and sustainability pressures, is where the near term catalysts and downside risks now concentrate.
Kao's current analyst narrative points to forecast revenue of ¥1,960.3b and projected earnings of ¥164.1b by 2029, built on an assumed 3.8% yearly revenue growth rate and an earnings increase of about ¥28b from current earnings of ¥136.1b.
Uncover why Kao's fair value indicates a 3% potential upside to its current price that could narrow quickly.
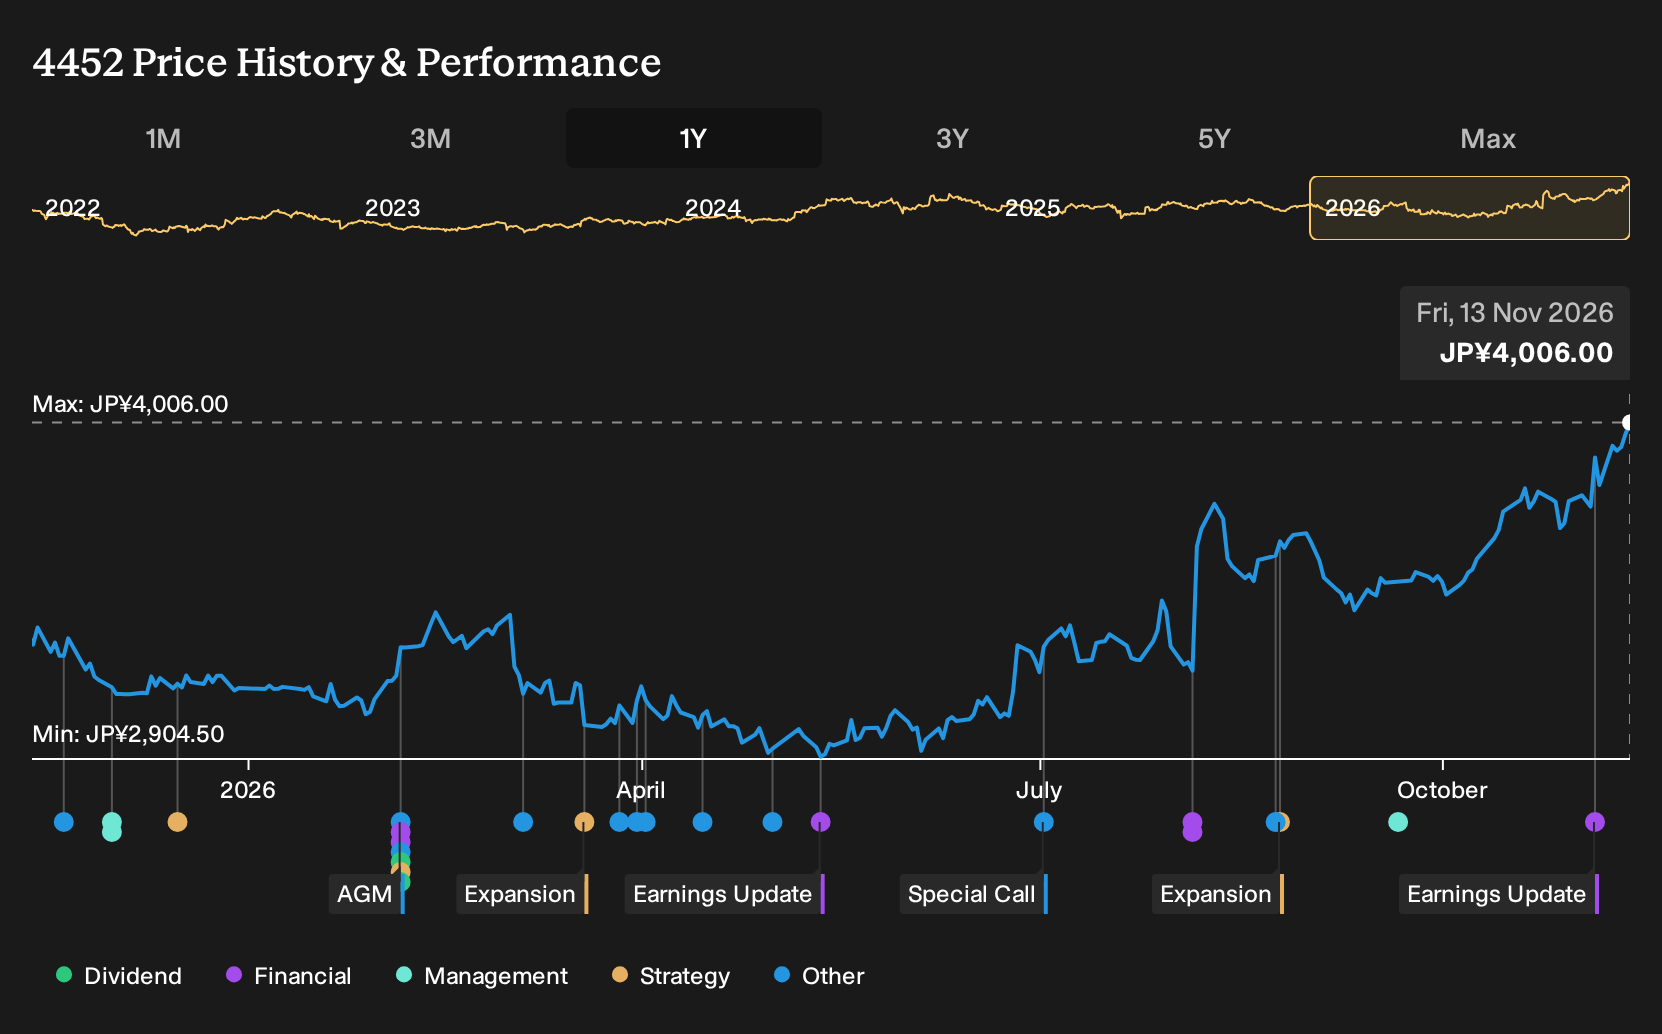
Exploring Other Perspectives
The three fair value estimates from the Simply Wall St Community cluster between ¥2,974 and ¥4,184, which already shows a wide band for Kao despite a small sample. That spread sits alongside risks around raw material costs and overseas competition, so you should expect sharply different opinions and explore multiple viewpoints.
Explore 2 other Kao fair value estimates, including one that suggests it could be worth as much as ¥4184.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Kao research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Kao. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kao's overall financial health at a glance.
Looking for more investment ideas beyond Kao?
If Kao's story has sharpened your view on quality and risk, broaden the search by using the Simply Wall St Screener to spot other businesses that might fit your approach on valuation, balance sheet strength, or income.
- For investors who care most about quality on sale, scan a 18 high quality undervalued stocks that combine solid fundamentals with muted expectations in the market.
- If capital preservation is your first filter, focus on a 19 resilient stocks with low risk scores that score well on resilience and financial risk metrics.
- When you want sturdier balance sheets to anchor a portfolio, start with a list of solid balance sheet and fundamentals (24 results) and see which companies pair low debt with robust fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com