


Delta Air Lines (DAL) Prices New Notes, Is The Stock Fully Priced?
Delta Air Lines (DAL) just tapped the bond market, completing a fixed income offering of US$499.275 million in 5.5% senior unsecured notes due November 2029, which puts its capital structure back in focus.
Delta Air Lines shares have cooled slightly in the past week, with a 7 day share price return that declined 1.09%, even after a strong 30 day share price gain of 14.44% and a year to date share price return of 24.89% from the latest close of US$86.25. Recent headlines have ranged from the new 5.5% senior notes to operational pressure from an FAA ground stop and upcoming Heathrow terminal changes. The longer lens tells a different story, with total shareholder returns of 49.24% over one year and more than doubling over three and five years, which suggests that longer term momentum has been strong even as shorter term sentiment has softened slightly.
Scan how Delta Air Lines stacks up against other carriers and capital intensive operators by reviewing our hand picked 34 high quality undervalued stocks that combine balance sheet strength with pricing pressure already in the share price.
Delta Air Lines now trades at a double discount, with the share price below average analyst targets and an even larger gap to estimated intrinsic value. Is that market caution about leverage and execution, or is it mispricing?
Most Popular Narrative: 36% Overvalued
Against the latest close of $86.25, the most followed narrative on Delta Air Lines pins fair value at $63.21, which implies the current bond-fueled momentum leaves the equity pricing ahead of that estimate. That view comes from a discounted cash flow style approach that uses an 11% discount rate and sees today’s share price as rich relative to the cash generation profile.
According to PittTheYounger, an investor in the Simply Wall St Community who wrote the narrative, Delta remains a high quality operator but the cycle it is in matters for what you pay.
Atlanta's home airline still shines bright, and indeed brighter than most in a notorious low-margin, low-profit industry. In its Q2 trading update, Delta once again trounced analysts' expectations both top and bottom line. Yet there is a snag: The legacy carrier comes from all-time high profitability. Hence, the risk distribution is skewed to the downside as long as there's no final and reliable re-opening of the Strait of Hormuz. That is why I stick to my valuation even in the face of shares trading some 38 per cent in excess of my calculations, because the latter is just that: excess. A current PE at some 14.5 and a forward PE at around 12 are simply too rich against this macro and geoeconomic backdrop. Delta would have to increase its current profit margins considerably to justify these multiples, which is a well nigh impossible order. If you seek exposure to the airline industry, Delta is a mandatory buy without doubt, but not at these levels. Once the froth is out of the price, however, I''m certain to increase my holding.
See why 23 investors see Delta Air Lines as 36% overvalued.
Result: Fair Value of $63.21 (OVERVALUED)
Still, that overvaluation story could unravel quickly if Delta Air Lines sees travel demand stabilize faster than expected, or if tariff related economic risks ease meaningfully.
Find out about the key risks to this Delta Air Lines narrative.
Another View On Delta Air Lines Valuation
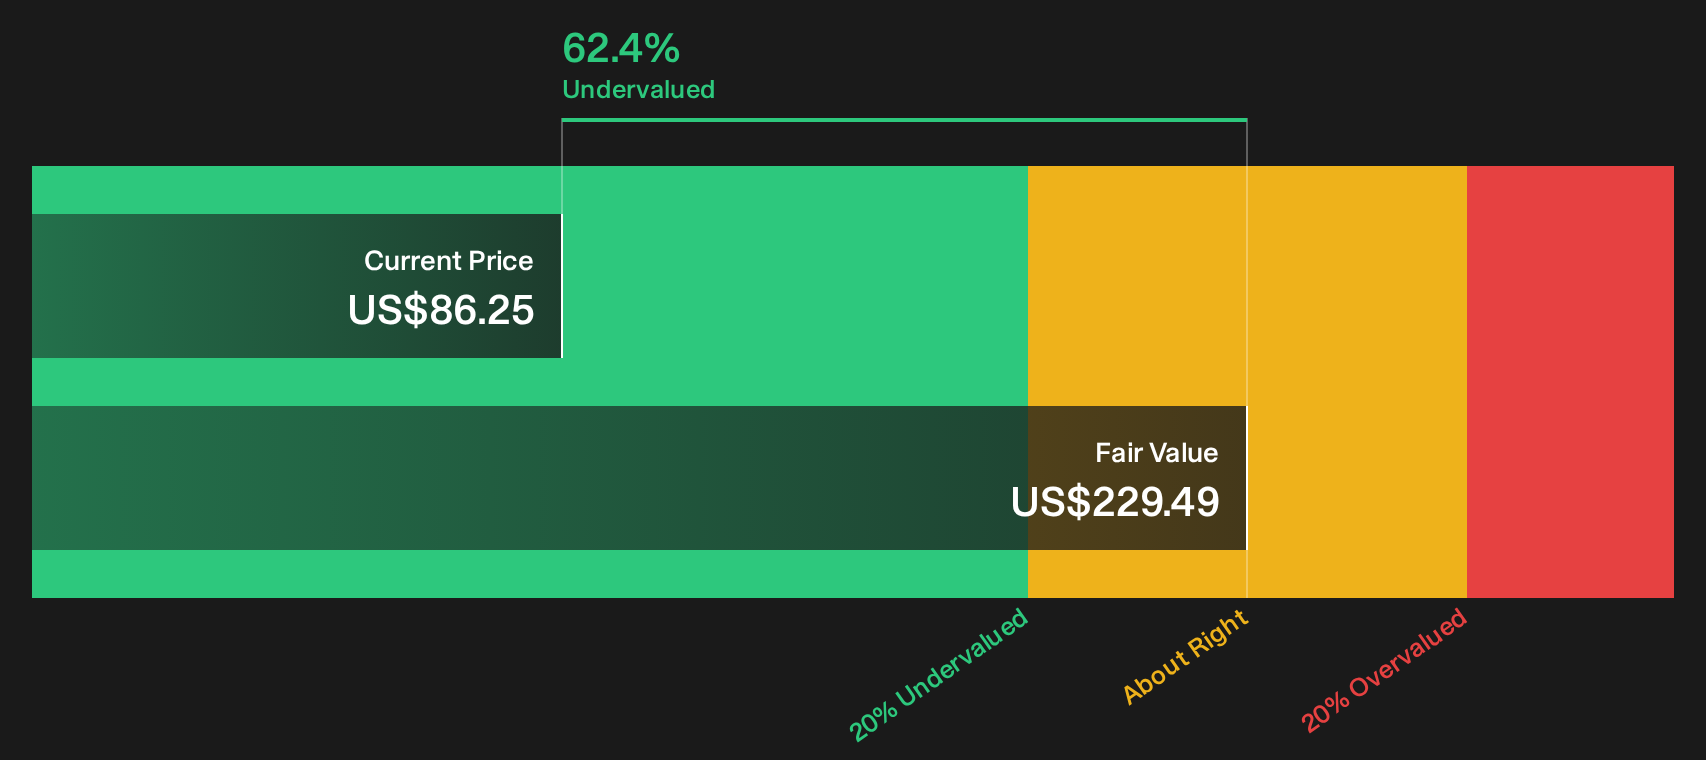
The SWS DCF model supplies a very different answer. On that framework, Delta Air Lines at $86.25 is trading 62.4% below an estimated future cash flow value of $229.49, which screens as significantly undervalued. If the cash flow assumptions hold, is the market pricing in too much risk, or are the model inputs too optimistic?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Delta Air Lines for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Delta Air Lines is split, with strong gains on the board and sharply different valuation stories arguing over what comes next. Act quickly, review both the caution flags and the upside signals, and weigh them against your own risk tolerance by checking the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Delta Air Lines?
If you only stop at Delta Air Lines today, you risk missing other opportunities that could fit your goals even better across risk, income, and value.
- Target potential mispricing by scanning for quality companies that trade below their estimated worth using the 34 high quality undervalued stocks.
- Lock in potential income streams by reviewing the 6 dividend fortresses and focus on businesses that combine yield with financial resilience.
- Dial down portfolio stress by filtering for companies with robust finances and steady fundamentals through the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com