


SI-BONE (SIBN) Reaffirms Outlook After Q3 Results, Is It Still Below Fair Value?
SI-BONE (SIBN) just released third quarter 2026 results, reporting higher sales and a smaller net loss, and supported that by reaffirming its full year revenue outlook in early November.
The share price reaction has been mixed, with SI-BONE stock down 2.9% on the day of the latest close and 3.3% over the past week, yet still showing a 19.1% 1 month share price return and a 25.4% 3 month share price return as traders weigh the narrower loss and reaffirmed guidance.
Scan for other medical device stocks showing similar post earnings momentum with our hand picked 36 healthcare AI stocks, which blend healthcare exposure with AI driven potential.
After that sharp three month rerating, SI-BONE trades below the average analyst target and well under some intrinsic value estimates. So where does a reasonable fair value range land now?
Most Popular Narrative: 7.9% Undervalued
On the analyst consensus Narrative on Simply Wall St, SI-BONE screens as modestly undervalued, with a fair value of $25.44 against the latest close at $23.44. That gap rests on specific growth and reimbursement assumptions.
Favorable reimbursement changes, including the finalized complex spinal fusion DRGs that can add up to US$50,000 per Granite case from October 2026 and proposed higher payments for SI joint fusion codes from January 2027, reduce economic friction for hospitals and may support higher revenue per procedure and stronger net margins.
See why 5 investors see SI-BONE as 8% undervalued.
Result: Fair Value of $25.44 (UNDERVALUED)
Still, SI-BONE’s story leans heavily on U.S. reimbursement staying supportive and on the ongoing iFuse TORQ recall not causing deeper procedural or relationship disruption.
Find out about the key risks to this SI-BONE narrative.
Another View: SI-BONE Screens As Expensive On Sales
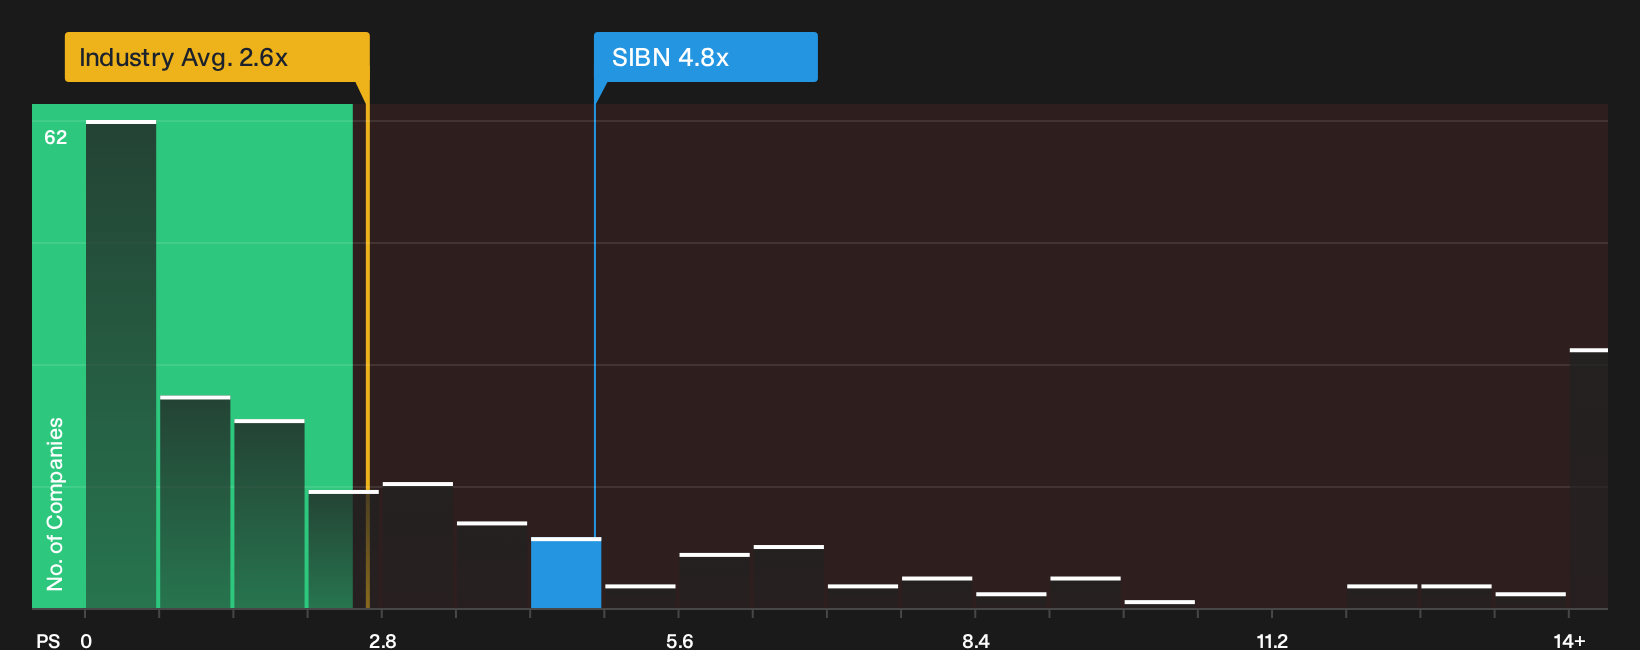
The DCF work points to SI-BONE trading at a steep discount to estimated future cash flows, yet its 4.8x P/S ratio looks rich next to the US Medical Equipment industry at 2.6x, peers at 4.2x, and even its own 4.3x fair ratio. Is the stock pricing in more success than the cash flow model assumes?
To pressure test that sales based view against a different framework, take a closer look at how our valuation work ties price to fundamentals through See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and caution around SI-BONE feels familiar, consider acting while the details are fresh and review the numbers for yourself. To frame both sides clearly, start with the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond SI-BONE?
Once you have formed a view on SI-BONE, do not stop there. Use the same toolkit to hunt for other opportunities that fit your style and risk tolerance.
- Target resilient compounders by scanning companies on the 30 resilient stocks with low risk scores that balance measured volatility with steadier fundamentals.
- Hunt for quality at a discount by running through the 34 high quality undervalued stocks and spot businesses trading below their implied worth.
- Zero in on financial strength with the list of solid balance sheet and fundamentals (24 results) and filter for enterprises backed by cleaner debt profiles and sturdier cash positions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com