


Almonty Industries Stock What Changed After Strong Earnings And Sangdong Restart
- Almonty Industries reported third quarter 2026 sales of C$41.89 million and net income of C$50.24 million, while nine month sales reached C$110.28 million with net income of C$226.77 million, alongside completion of a share buyback of 3,617,792 shares for C$59.98 million.
- The shift from a nine month loss of C$59.64 million in the prior year to substantial profit, supported by Sangdong production and an expanded offtake agreement, highlights how Almonty Industries is now monetising its tungsten assets and long term contracts rather than relying only on project optionality.
- We will now look at how Almonty Industries' investment narrative could be reshaped by the strong third quarter profit and Sangdong ramp.
Scan how Almonty Industries fits into the tungsten and critical metals story by comparing it with a curated list of 33 best rare earth metal stocks.
Almonty Industries Investment Narrative Recap
Almonty Industries now asks you to believe in a fully operating tungsten portfolio, not just a collection of projects. The analyst consensus Narrative on Simply Wall St hinges on Sangdong hitting design capacity while Los Santos tailings and Rwanda feed scale up. The latest C$226.77 million nine month profit leans in that direction, but the key short term catalyst is still consistent Sangdong ramp performance.
The biggest near term risk remains operational hiccups at Sangdong, or delays in turning contracts and projects into steady tonnes and cash. Recent results do not remove that risk, although strong C$110.28 million nine month sales and positive earnings provide more breathing room if equipment, permitting or ESG issues slow progress.
The earnings release for the third quarter looks most relevant. C$41.89 million in quarterly sales and C$50.24 million in profit show Almonty Industries generating cash from mining and concentrate production rather than depending only on future scenarios. That directly ties into the catalysts around Sangdong throughput and expanded long term agreements.
For you as a shareholder, the C$0.17 basic EPS in the quarter and C$0.80 over nine months, combined with the completed C$59.98 million buyback of 3,617,792 shares, sharpen the focus on execution. Strong reported income raises the bar on consistency, while the reduced share count increases exposure to any future swings in tungsten prices, project delivery, or offtake performance.
Almonty Industries' narrative projects C$1.7b revenue and C$983.1 million earnings by 2029. This assumes revenue grows at 171.4% per year and earnings rise by about C$875.6 million from C$107.5 million today.
Uncover why Almonty Industries' fair value indicates a 187% potential upside to its current price that could narrow quickly.
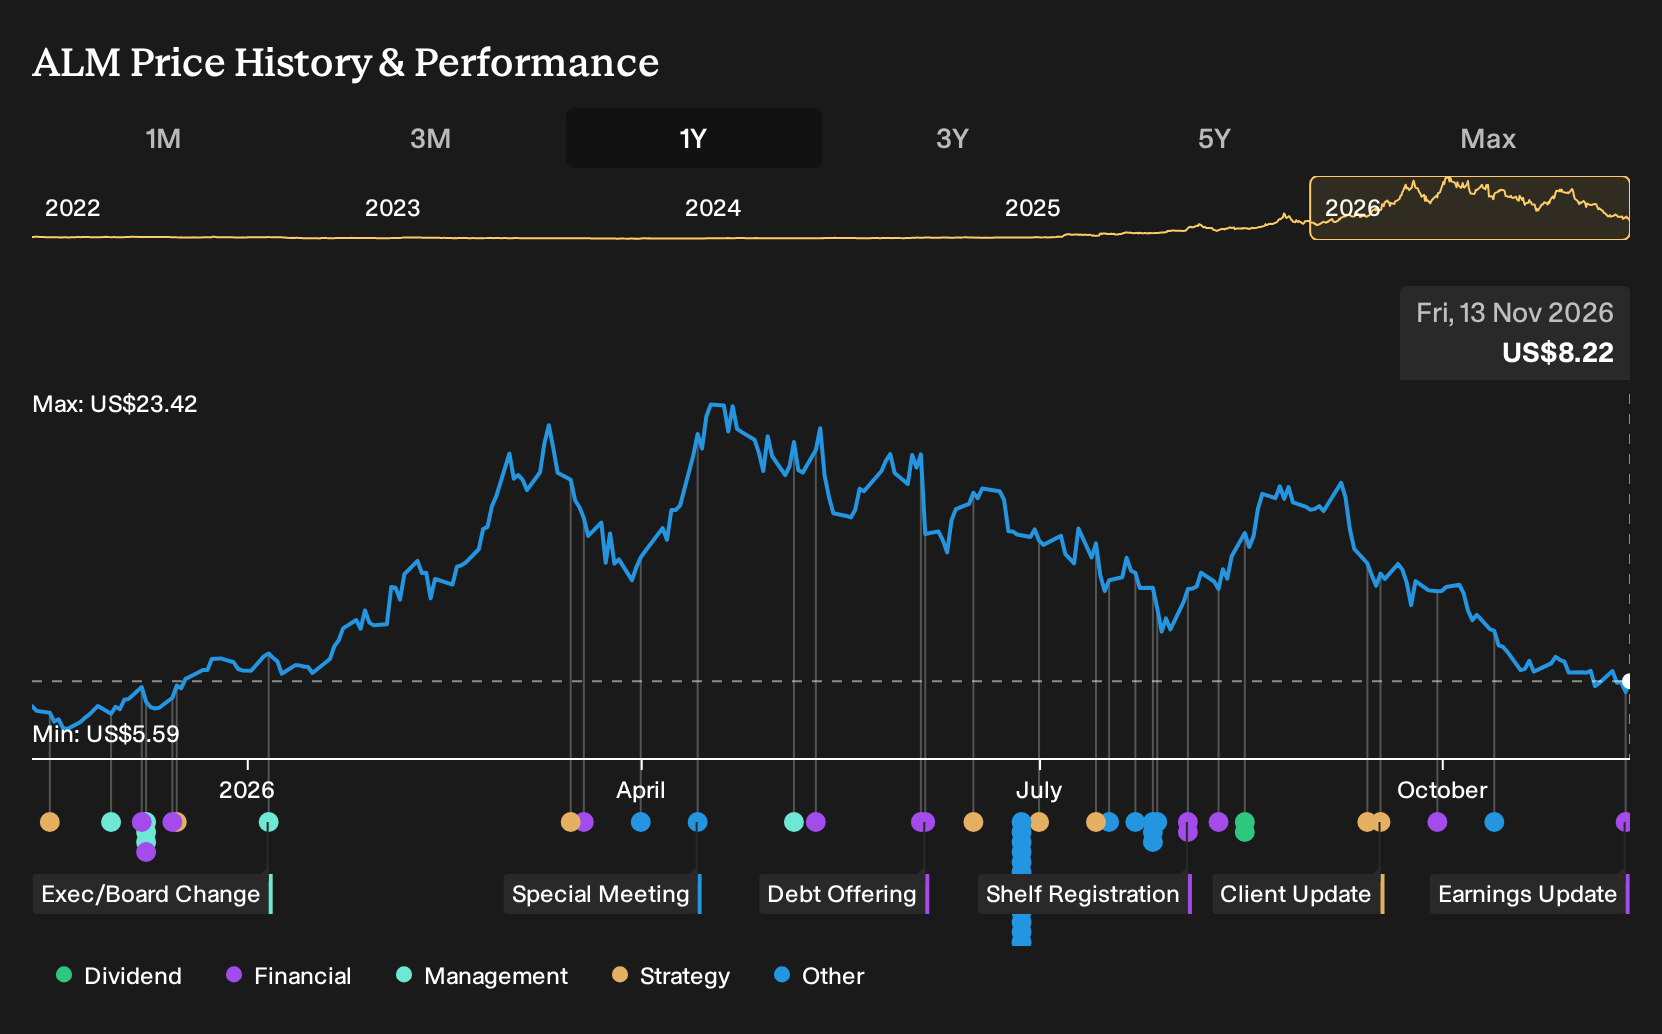
Exploring Other Perspectives
One bearish twist on Almonty Industries focuses on how the C$800m of convertible notes are used. The lowest analysts worried that if Sangdong and Los Santos ramped slowly, future returns on that capital could look thin, even with 93.8% annual revenue growth and C$508.0 million in 2029 earnings in their models. Those figures were set before this earnings and buyback update, so you may want to compare them with the new numbers and decide whether that cautious script still fits your view.
Explore 4 other Almonty Industries fair value estimates, including one that suggests it could be worth just $10.78!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Almonty Industries research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Almonty Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Almonty Industries' overall financial health at a glance.
Looking for more Almonty Industries sized investment ideas?
If Almonty Industries has sharpened your interest in tungsten and critical metals, it can help to widen the lens and compare it with other listed businesses that share similar qualities in cash flow, resilience, or upside potential. The Simply Wall St Screener gives you a structured way to do that, so you are not just reacting to one stock but weighing it against a broader bench of opportunities that suit your style and risk tolerance.
- For investors who want quality and value in the same place, scan a curated set of companies trading below estimated worth and supported by solid fundamentals through the 32 high quality undervalued stocks.
- If capital preservation and steadier profiles matter most to you, filter for businesses with stronger balance sheets and fewer red flags by using the list of solid balance sheet and fundamentals (24 results).
- When you prefer to get in early on underfollowed stories with robust accounts, focus on a hand picked pool of quieter opportunities with the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com