


What Eurobank Shareholders Got Right
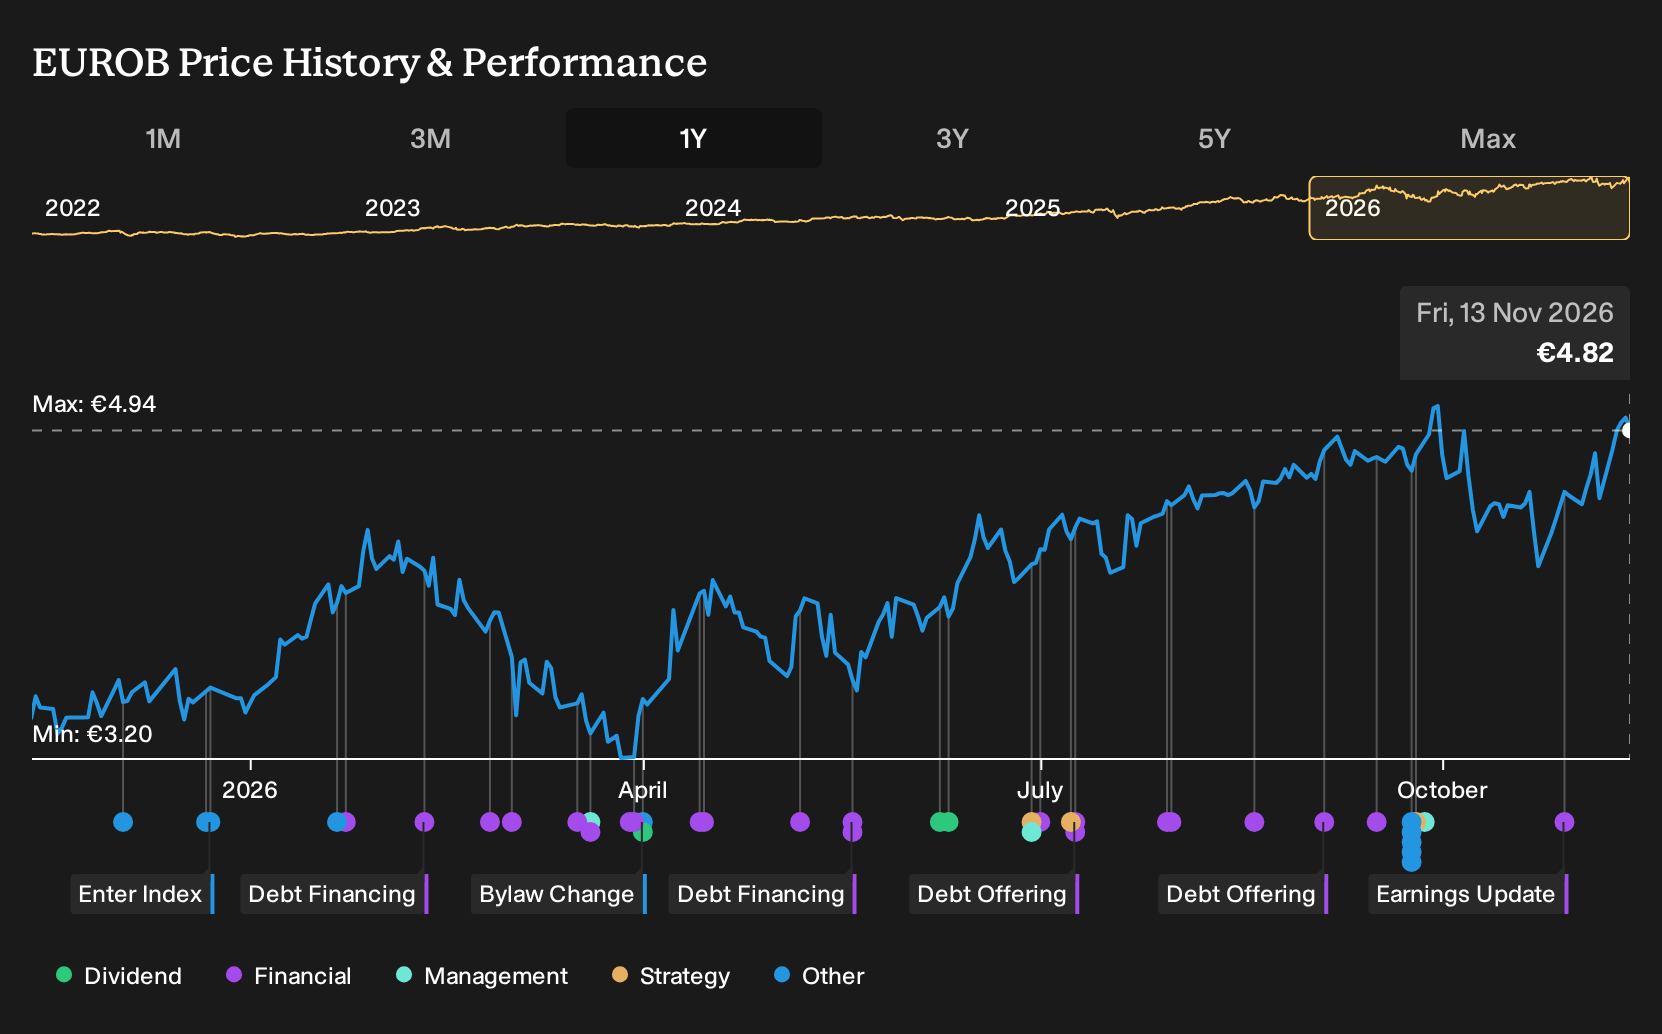
Eurobank’s move to acquire full ownership of Eurolife Life Insurance gave investors a very specific development to latch onto: a clear expansion of its bancassurance footprint rather than a vague digital story. For Eurobank shareholders, the return over the past year was 42.3%, including dividends. If you were deciding back in November 2025 whether to buy, what did you need to believe about this kind of deal and its earnings impact before any of that payoff appeared?
If the move has made Eurobank harder to judge, start where the gap is still open and scan 198 high quality undervalued stocks.
Two Competing Stories Investors Had To Weigh On Eurobank
The shares cost €3.5 at the start of the period, and Eurobank sat between two very different stories about what might come next.
The bullish view saw digital projects and ESG positioning as levers for resilience, with a Fair Value near €4.36 that reflected a price implied by assumptions such as revenue rising 8.1% a year and earnings reaching €1.7b by 2028.
The bearish case focused on demographics and fintech rivalry, with a Fair Value around €2.7 and concerns that profit margins could slip from 48.0% to 38.9% over three years.
What The Eurobank Evidence Put On The Scales
The completed acquisition of the remaining 80% stake in Eurolife Life Insurance gave clear support to the optimistic story that assumed stronger bancassurance earnings. Reported numbers pointed in the same direction, with total revenue at €890m and net income at €424m in Q3 2026, and the net margin rising to 47.6%. The evidence mainly backed the bullish case.
The useful takeaway is simple: when a bank leans on an acquisition thesis, track whether revenue mix and reported net margin actually move in the direction that deal supporters were counting on.
What Eurobank's Share Price Already Bakes In
Eurobank now trades at €4.82, and the bearish analyst Narrative on Simply Wall St sees its Fair Value as below that level, even after a 42.3% gain over the past year from €3.5.
At this price you are effectively assuming Eurobank turns loan demand, higher fee income and heavy IT spending into lasting operating leverage. How do rising wage and technology costs affect that bet according to this Narrative?
"The main thing that has to go right is that Eurobank converts strong credit demand, higher net interest income guidance, and growing fee income into sustained operating leverage while keeping asset quality and cost of risk close to current targets. The numbers imply that Eurobank's share price already reflects a fairly valued and bullish case in which loan growth, fee expansion, and disciplined capital returns continue broadly in line with current plans."
One Narrative disagrees with today's price. → See where this Narrative says Eurobank should trade
Which Company Could Surprise You Next?
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 34% below our estimate - sells cloud and AI infrastructure for converged software and workloads.
- Company 2 - 33% below our estimate - builds fee-based revenue from renewable energy, infrastructure and tax-efficient vehicles.
- Company 3 - 20% below our estimate - expands surgeon adoption of antibiotic-eluting bone grafts for infection-prone procedures.
Three companies from the same screener. Open the full list of 198 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com