


Earnings Growth Could Be A Game Changer For CTS Eventim KGaA (XTRA:EVD)
- CTS Eventim KGaA reported third quarter 2026 sales of €809.12 million and net income of €50.26 million, with nine month sales of €2,321.96 million and net income of €170.63 million from continuing operations.
- The business showed higher nine month earnings per share of €1.78 from continuing operations, supported by growth in ticketing revenue and improved Live Entertainment profitability.
- We will now explore how CTS Eventim KGaA's nine month earnings momentum, especially in ticketing, may shape its investment narrative.
Compare CTS Eventim KGaA's ticketing driven momentum with a curated set of peers by scanning our hand picked 559 high quality undiscovered gems, which also pair strong fundamentals with growing earnings stories.
CTS Eventim KGaA Investment Narrative Recap
For CTS Eventim KGaA, the core belief is that ticketing scale, international integration and a broader venue footprint can support earnings through different event cycles. The latest report shows ticketing driving nine month growth in revenue and net income even though third quarter sales and EPS from continuing operations were lower than a year ago. That mixed picture keeps the near term focus firmly on execution rather than headline momentum.
In the short run, the key swing factor is whether ticketing can keep offsetting cost pressure and profit volatility in Live Entertainment, which the analyst consensus Narrative on Simply Wall St highlights as a risk. Rising artist fees, loss making festivals or heavier project spending could squeeze margins. If operational excellence and Amplify costs stay elevated without clear efficiency gains, that would be an additional headwind.
The recent earnings release for the third quarter and nine months to 30 September 2026 is the announcement that matters most here. Ticketing revenue for the period grew more than 13%, with management pointing to price mix, higher retail activity and Olympic related sales, while Live Entertainment improved adjusted EBITDA despite startup and portfolio effects. That mix indicates where the current economic engine sits within the business.
At the same time, CTS Eventim KGaA reiterated its full year outlook and flagged the new Unipol Dome in Milan as a contributor from the fourth quarter. That venue joins LANXESS Arena, Waldbühne and others in a growing asset light network that the analyst consensus Narrative on Simply Wall St views as a medium term earnings driver. Execution risk remains, especially on costs and festival profitability, so an investor’s view on those projects is likely to influence their stance on the shares.
CTS Eventim KGaA's current narrative ties analyst expectations of €3.8b revenue and €428.3 million earnings by 2029 to an assumed 4.4% yearly revenue growth rate, along with an earnings increase of about €120 million from €308.0 million today.
Uncover why CTS Eventim KGaA's fair value indicates a 36% potential upside to its current price that may not last much longer.
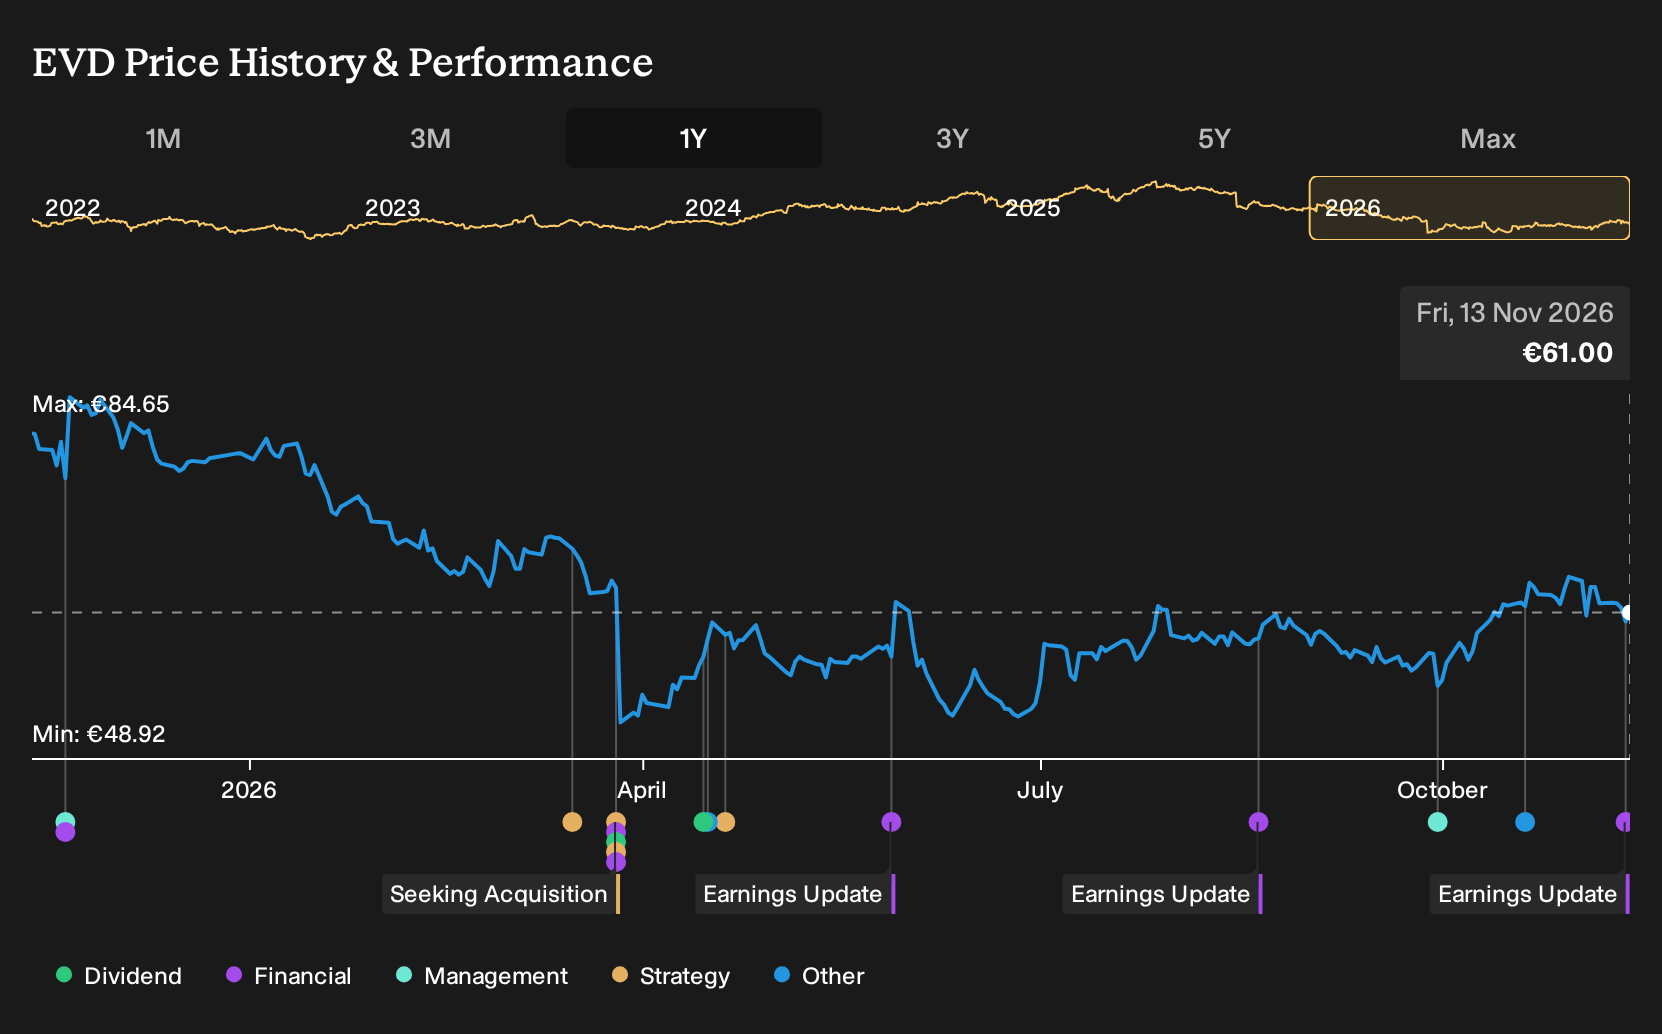
Exploring Other Perspectives
One alternate view on CTS Eventim KGaA puts the Amplify and operational excellence programs front and centre as a drag, not a future benefit. The most cautious analysts were pencilling in revenue of about €3.6b and earnings near €353.5 million by 2029, well below consensus. This shows how sharply opinions can differ and why it can help to compare several narratives that may shift after this earnings update.
Explore 5 other CTS Eventim KGaA fair value estimates, including one that suggests as much as 21% downside from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your CTS Eventim KGaA research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for CTS Eventim KGaA. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CTS Eventim KGaA's overall financial health at a glance.
Looking for more investment ideas beyond CTS Eventim KGaA?
If the CTS Eventim KGaA story has sharpened your thinking but you want a broader watchlist, it can help to scan structured stock lists that flag different types of opportunities across the market.
- For potential mispriced opportunities with solid fundamentals, check out a curated 198 high quality undervalued stocks that may offer a useful comparison point to CTS Eventim KGaA.
- If resilience and balance sheet strength matter most to you, start with a list of solid balance sheet and fundamentals (198 results) to see which businesses pair financial stability with room for future decisions.
- Income focused investors who want yield with a quality filter can look through a set of 220 dividend fortresses and use them as candidates for deeper dividend research.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com