


Delek Logistics Partners (DKL) Just Gave Investors Something To Think About
What Delek Logistics Partners’ latest earnings tell you
Delek Logistics Partners (DKL) just posted third quarter 2026 results, with sales and revenue at US$372.44 million compared with US$261.28 million a year earlier, while net income and earnings per unit stayed relatively steady.
On the market side, Delek Logistics Partners has seen mixed momentum, with a 7-day share price return of 2.96% but a decline of 5.51% over 30 days. However, a 13.40% year-to-date share price gain and 87.46% five-year total shareholder return suggest longer term holders have been rewarded, even as sentiment cools near the recent US$53.30 level.
Scan how Delek Logistics Partners compares with other energy plays showing resilient returns and solid fundamentals in our curated list of list of solid balance sheet and fundamentals (24 results).
Delek Logistics Partners shows a long run of solid total returns and steady earnings per unit. Yet the recent cooling in the share price raises a tougher question: Are investors now paying a fair price for that resilience or stretching for it?
Most Popular Narrative: 0% Overvalued
On the Simply Wall St analyst consensus Narrative, Delek Logistics Partners screens as slightly over its narrative fair value of $53.17, with the last close at $53.30. This puts the focus squarely on whether future projects justify that gap under a 7.5% discount rate.
The main factor that has to go right is successful execution on high return midstream and sour gas projects, including the Libby gas complex expansions, acid gas injection infrastructure and water system integrations, so that these assets support third party volume growth and help manage leverage around management’s stated target.
See why 4 investors see Delek Logistics Partners as 0% overvalued.
Result: Fair Value of $53.17 (ABOUT RIGHT)
Still, if Delek Logistics Partners keeps missing earnings expectations or carries leverage above its 3.5x target for a longer period, the fair value story could come under pressure.
Find out about the key risks to this Delek Logistics Partners narrative.
Another View on Delek Logistics Partners’ Valuation
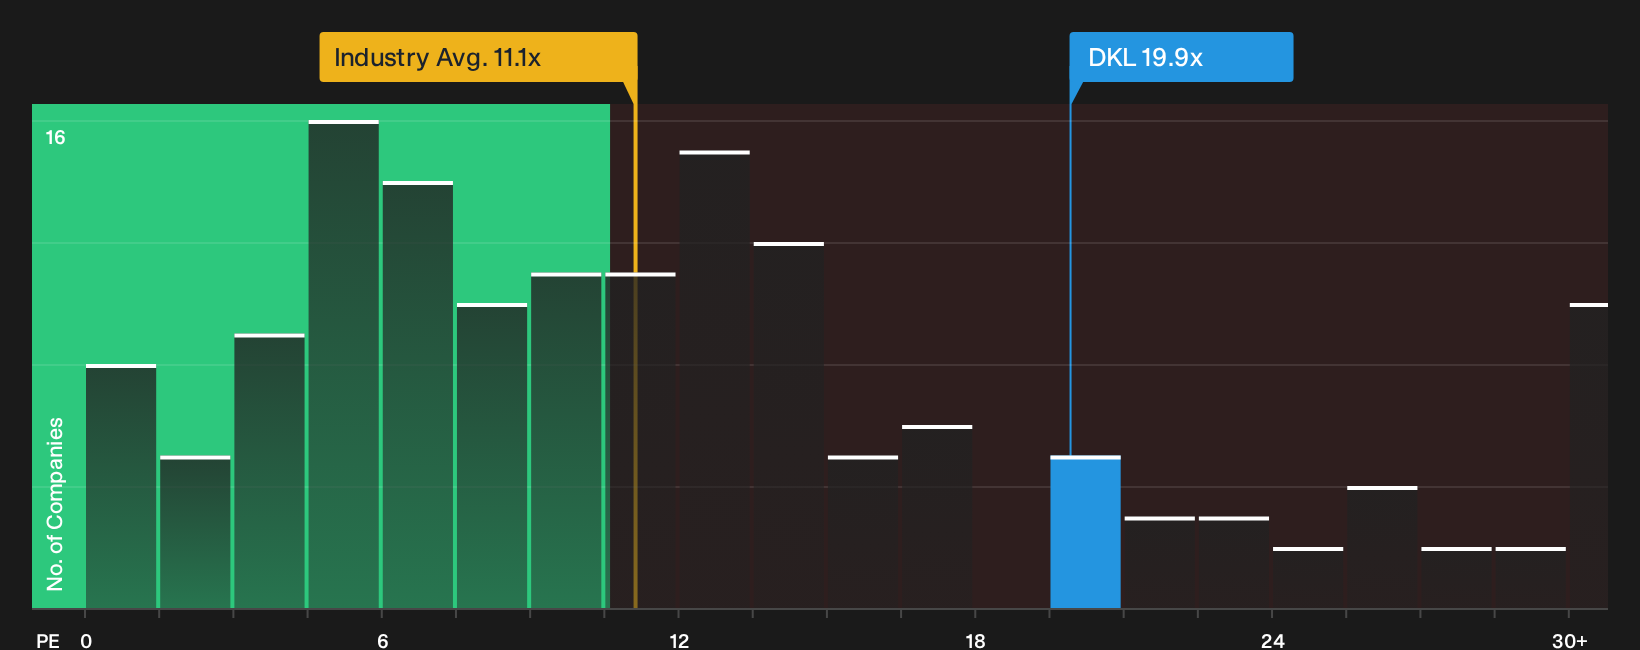
Analyst narratives suggest Delek Logistics Partners is trading close to fair value around $53 per unit. The P/E ratio tells a different story. At 19.8x, DKL trades at a clear premium to both the US Oil and Gas industry on 11.1x and direct peers on 9.6x, and even above its own 18.8x fair ratio.
That kind of gap can signal investors are paying up for perceived resilience. This raises the risk that any stumble in earnings, balance sheet progress or project delivery could see the multiple drift back toward the fair ratio. The question is simple for you as a unitholder: how comfortable are you owning something that already prices in this much good news?
See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Delek Logistics Partners for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Delek Logistics Partners’ valuation and risk profile can make the picture feel blurred, so move quickly on your own homework and consider both sides. To see the key issues investors are debating, including 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Delek Logistics Partners?
If Delek Logistics Partners feels fully priced to you, broaden your watchlist now, because the next opportunity rarely waits around for long.
- Target higher potential upside by scanning a focused set of 20 high quality undiscovered gems with strong fundamentals that the crowd may have overlooked.
- Prioritise resilience by running through 31 resilient stocks with low risk scores that score well on financial strength and business stability.
- Strengthen your income playbook by checking 6 dividend fortresses built around payout levels that may appeal to yield focused investors.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com