


Dave (DAVE) Stock Jumped, What Is Behind The Fresh Attention?
Dave (DAVE) just released new third quarter numbers and raised its 2026 revenue outlook, putting the focus squarely on how this fast growing fintech is turning headline figures into durable earnings power.
That guidance bump followed a choppy stretch for Dave’s stock, with a 1-month share price return down 22.3% and a 3-month share price return down 15.7%. Even so, the year-to-date share price return is up 28.5%, and the 3-year total shareholder return is extremely high, signaling strong long-term momentum that recent volatility has not entirely shaken.
Scan beyond Dave for other fintech and financial platforms showing strong revenue traction and fresh guidance upgrades by checking our hand picked 19 high quality undiscovered gems.
The share price slump, alongside higher revenue guidance and steady profitability, leaves a simple tension: Are investors reassessing Dave’s fundamentals, or does the valuation now reflect sentiment more than the underlying business?
Most Popular Narrative: 36.5% Undervalued
On the analyst consensus Narrative on Simply Wall St, Dave screens as materially undervalued, with a fair value of $444.21 against a last close of $281.96. This puts the valuation debate squarely on whether the growth and margin profile can sustain that gap.
Structural shift toward capital-light funding, as the Coastal Community Bank facility moves ExtraCash receivables off balance sheet, has already turned receivables into a US$30.5 million cash source in Q2 2026 and is expected to unlock over US$200 million of incremental liquidity that can support higher volume growth, lower funding costs and potentially stronger earnings.
See why 47 investors see Dave as 37% undervalued.
Result: Fair Value of $444.21 (UNDERVALUED)
Still, two pressure points could flip the Dave story fast: the unresolved DOJ matter and any stumble in CashAI driven credit performance or funding.
Find out about the key risks to this Dave narrative.
Another View: What Dave’s P/E Is Saying
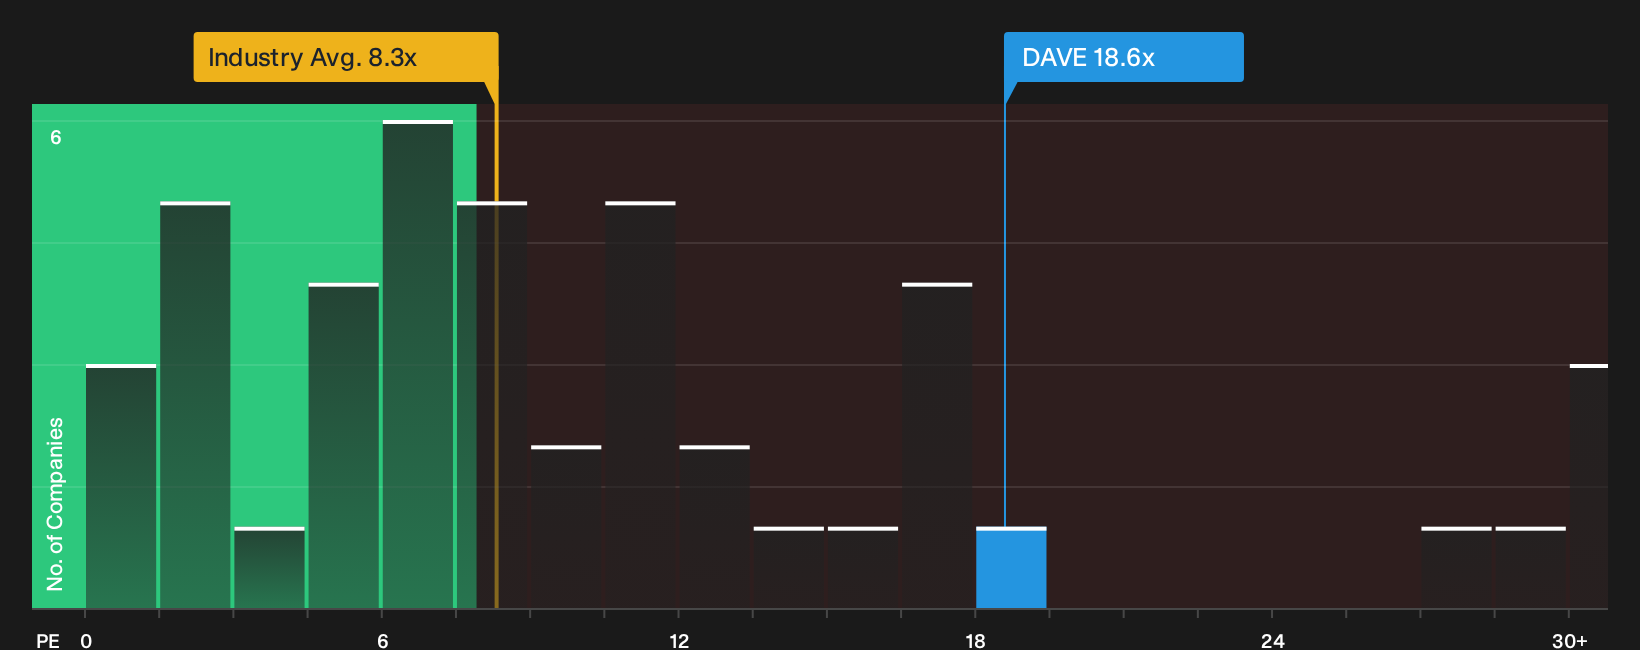
The DCF narrative presents Dave as 36.5% undervalued, yet the earnings multiple sends a cooler message. The stock trades on a P/E of 18.6x versus a peer average of 16.3x and a Consumer Finance industry level of 8.3x, even though the fair ratio sits at 19.2x. That mix of slight discount to the fair ratio but premium to the sector leaves a simple question: How much multiple risk are you willing to take for this growth profile?
For a closer look at how this earnings-based view compares with the broader peer set, including where the fair ratio might move next, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
With sentiment split across fair value, earnings multiples and risk headlines, it helps to pressure test the data yourself and move quickly to your own conclusion. To see what optimism in the market is already flagging, start with the 4 key rewards.
Looking for more investment ideas beyond Dave?
Do not stop your research with a single fintech. Broaden your watchlist with focused stock ideas that match your risk tolerance and income goals.
- Target potential mispricing by scanning for quality companies trading below estimated value with the 32 high quality undervalued stocks.
- Strengthen the defensive side of your portfolio by reviewing a list of solid balance sheet and fundamentals (23 results) that can better handle financial stress.
- Boost potential portfolio income by checking a curated group of 6 dividend fortresses offering higher yields.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com