


Half Year Results Change The Bull Case For Autotrader Group (LSE:AUTO)?
- Autotrader Group reported half year results to 30 September 2026 with sales of £313.4m and net income of £143.6m, both slightly below the prior period.
- Basic and diluted earnings per share from continuing operations edged higher year on year, suggesting mix and capital structure had a supportive effect even as sales and profit eased.
- We will explore how Autotrader Group's investment narrative intersects with steadier EPS from continuing operations despite softer half year sales.
Scan how Autotrader Group's steady EPS story compares with other opportunities by reviewing our curated list of 16 high quality undervalued stocks that may be priced for a potential rerating.
Autotrader Group Investment Narrative Recap
To own Autotrader Group, you need to be comfortable with a story where high margins, strong digital reach and product adoption matter more than short term volume trends. The latest half year results show sales and net income slightly lower, while EPS from continuing operations edged higher. That points to efficiency, buybacks or mix offsetting softer trading.
The key near term catalyst remains execution on products like Deal Builder and Co Driver, highlighted in the analyst consensus Narrative on Simply Wall St, and whether retailers keep paying for higher quality leads. The biggest risk still sits in pressure on margins from taxes, regulatory costs or weaker retailer stock levels. This set of numbers does not materially change either side of that equation.
With no fresh announcements beyond these earnings, the most relevant reference point is still the earlier plan to accelerate share buybacks and keep about one third of net income as dividends. That capital return approach, funded by moving net debt towards 1x EBITDA, helps explain why EPS can stay resilient even when revenue is flat to slightly lower.
For you as a shareholder, the link between operations and that capital plan is crucial. Earnings power depends on retailer adoption of tools like Deal Builder and Co Driver and on managing risks from Autorama, the digital services tax and retailer stock trends. If those operational levers underperform, higher leverage and buybacks could amplify the impact of any downturn rather than cushion it.
Autotrader Group's current analyst story points to revenues of £718.7 million and earnings of £326.9 million by 2029, based on 5.0% yearly revenue growth and an earnings increase of about £40.3 million from £286.6 million today.
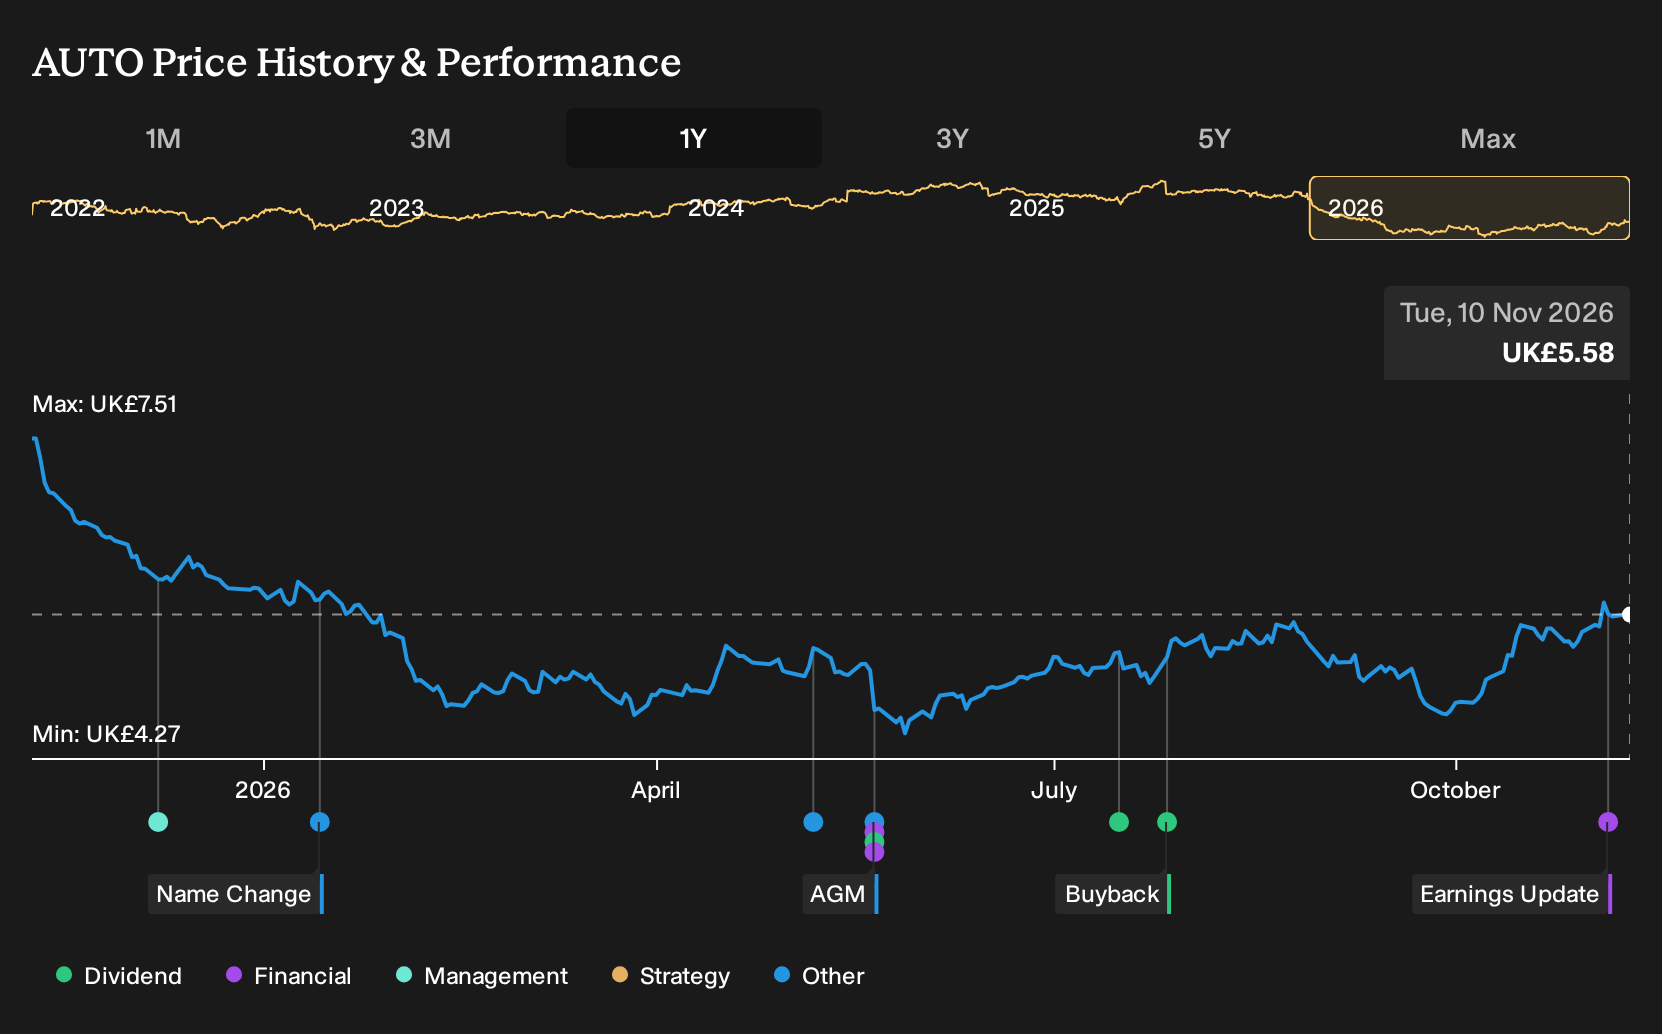
Discover why Autotrader Group's fair value indicates a 5% potential upside to its current price, a gap that could narrow quickly if sentiment shifts.
Exploring Other Perspectives
Higher conviction analysts focus on a different catalyst. They lean into Autotrader Group’s AI driven tools and had been pencilling in 7% annual revenue growth and earnings of about £363.3 million by 2029 before this half year report. You should expect more optimistic narratives to be revisited as this earnings data gets absorbed.
Explore 5 other Autotrader Group fair value estimates, including one that suggests up to 38% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Autotrader Group research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Autotrader Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Autotrader Group's overall financial health at a glance.
Looking for more Autotrader Group style ideas?
After weighing up Autotrader Group, it can help to widen the lens and compare it with other businesses that share similar qualities or offer something very different for your portfolio.
- If you want potential mispricing combined with strong fundamentals, scan our hand picked set of 16 high quality undervalued stocks that might suit a value focused watchlist.
- If capital strength matters most to you, concentrate on companies with cleaner finances using the list of solid balance sheet and fundamentals (9 results) as a starting universe.
- If you prefer quieter price swings and steadier profiles, narrow your search to the 4 resilient stocks with low risk scores and compare their traits side by side.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com