


Earnings Beat Might Change The Case For Renesas Electronics Stock
- Renesas Electronics reported third quarter 2026 sales of JPY 435,917 million and net income of JPY 372,193 million, with earnings per share from continuing operations well above the prior year.
- Profitability over the first nine months of 2026 reached JPY 589,526 million of net income after a loss in the same period a year earlier, underscoring a sharp swing in operating performance that investors are watching closely.
- This article examines how Renesas Electronics' sharp swing to profitability shapes its AI and software driven investment narrative from this point forward.
Renesas Electronics Investment Narrative Recap
To hold Renesas Electronics, you need to believe the analyst consensus Narrative on Simply Wall St that higher value AI, infrastructure and software lines can carry the weight of heavy R&D and SG&A while earnings forecasts point to declining profits over the next three years. The sharp swing to profitability and strong nine month net income give the balance sheet more room, yet high one off gains and earnings volatility keep quality and predictability in focus.
The near term catalyst is execution on AI infrastructure, data center power devices and digital power modules, as well as integrating timing business proceeds into capacity and platform expansion. The biggest risk is that high foundational spending, GaN litigation and slower than expected AI demand together stop operating margins from staying within management’s 25% to 30% framework and keep earnings below the narrative.
Among the recent moves, the RZ/T2N microprocessor launch looks most tied to that AI and industrial edge thesis. It puts real time motor control, industrial Ethernet and application processing on a single 64 bit platform that can be reused across articulated robots, multi axis servos and PLCs, which matters if automation customers want fewer chips and simpler software stacks.
The device’s support for EtherCAT, PROFINET, EtherNet/IP and TSN, plus integrated motor control for up to four axes, deepens Renesas Electronics exposure to factory modernization rather than only cloud data centers. That cuts both ways for catalysts and risk, since success would broaden compute content in industrial gear while any delay in adoption or software tooling around Renesas 365 would leave that hardware leaning more on price than on richer, recurring platform revenue.
Renesas Electronics is framed around analyst expectations that revenues reach ¥2,030.5b and earnings come in at ¥433.4b by 2029, based on a projected 11.0% yearly rise in sales and an earnings increase of about ¥92.5b from current earnings of ¥340.9b.
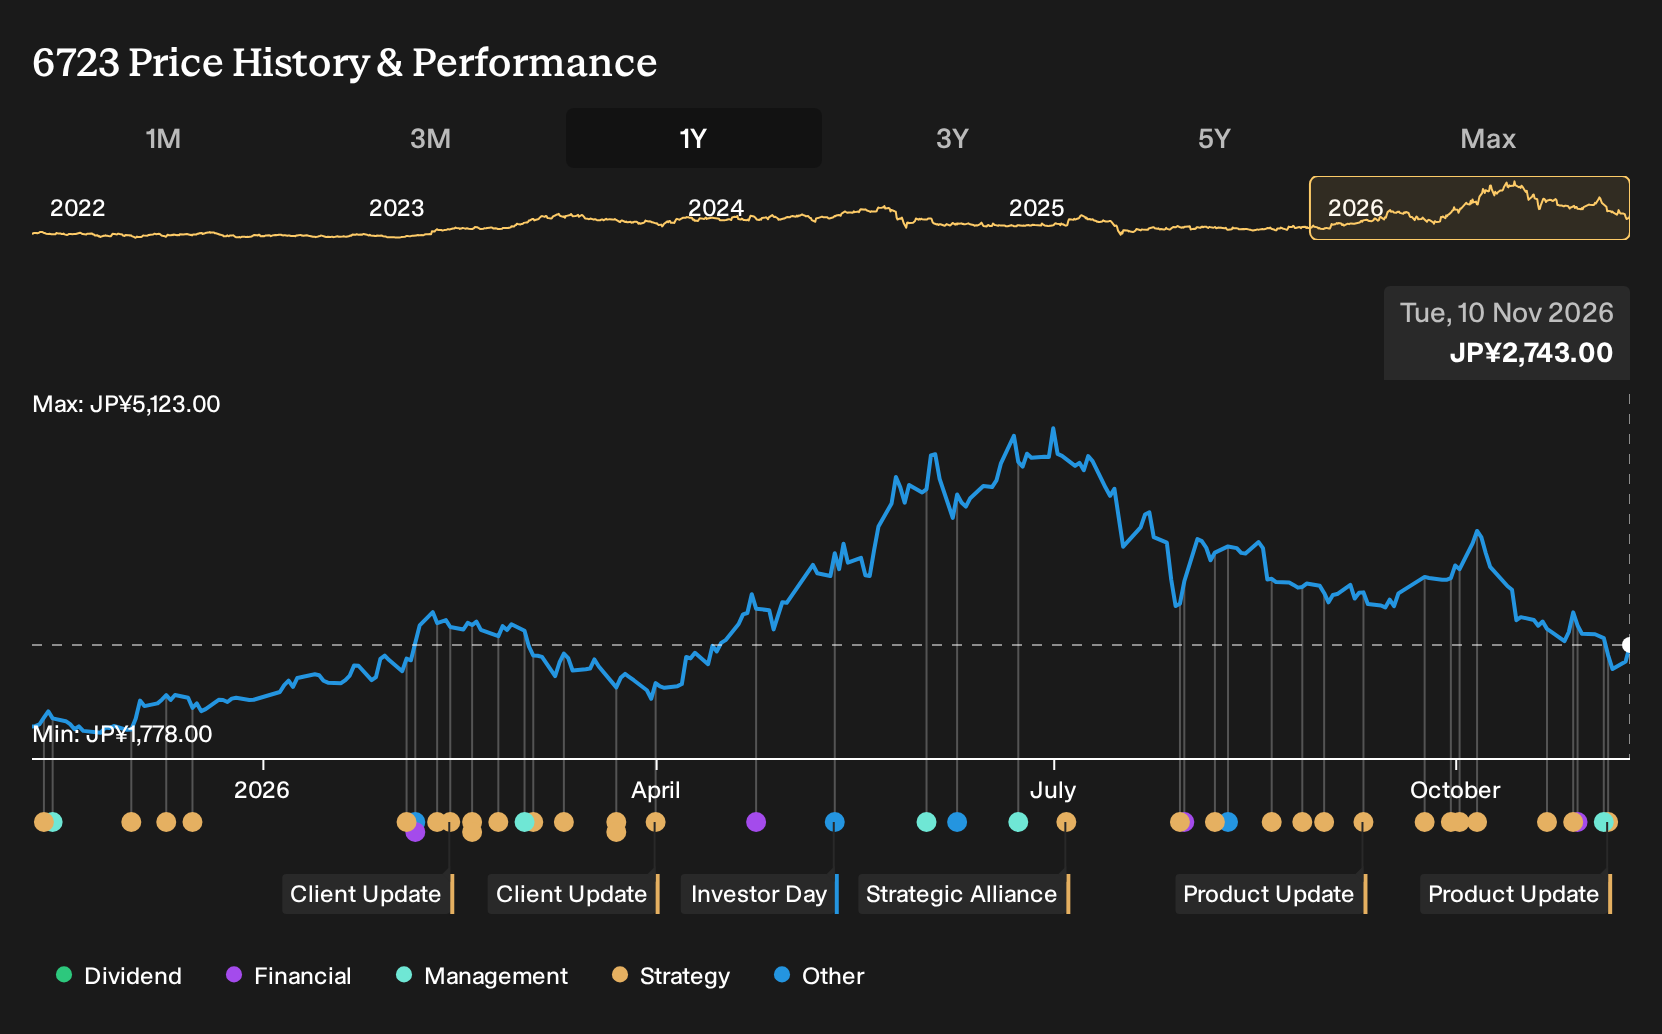
Uncover why Renesas Electronics' fair value indicates an 84% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the most optimistic analysts latch onto Renesas Electronics targeting higher semiconductor content in physical AI and humanoid robotics. Before this earnings surprise, the bullish cohort was already sketching out revenue of ¥2,357.1b and earnings of ¥594.6b by 2029. That is a far more upbeat story than consensus, and the RZ/T2N launch plus recent leadership changes could nudge forecasts again. Use that spread in expectations as a reminder to compare several viewpoints before deciding how this new information fits your own thesis.
Explore 2 other Renesas Electronics fair value estimates, including one that suggests there could be as much as 84% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Renesas Electronics research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Renesas Electronics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Renesas Electronics' overall financial health at a glance.
Looking For More Ideas Beyond Renesas Electronics?
If this Renesas Electronics story has sharpened your thinking, use that momentum to pressure test your watchlist against a broader universe of companies using the Simply Wall St Screener.
- For investors who care most about valuation support and balance sheet strength, consider scanning through 20 high quality undervalued stocks that pair earnings power with disciplined financial profiles.
- If capital preservation and a smoother ride matter more than chasing every swing, focus on 18 resilient stocks with low risk scores that score well on resilience and lower risk metrics.
- When you want to move earlier in the idea cycle without ignoring fundamentals, sift through 76 high quality undiscovered gems that combine quality markers with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com