


Did Undergrounding Power Lines Just Shift CMS Energy's (CMS) Investment Narrative?
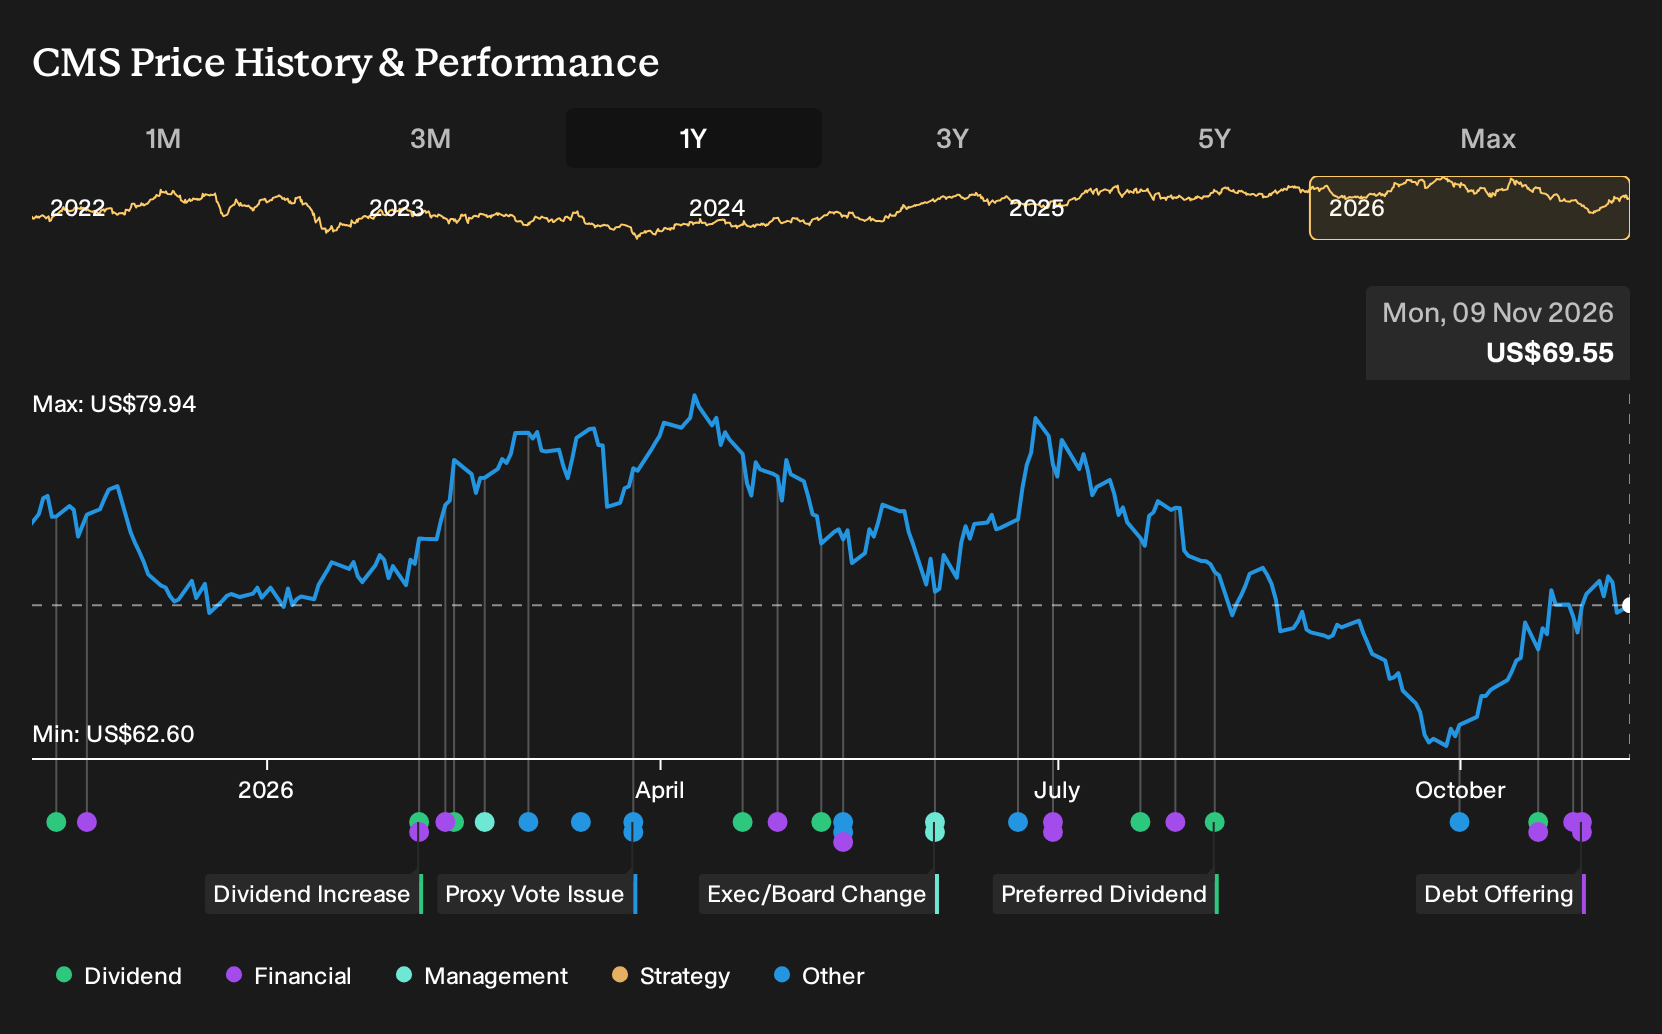
- CMS Energy has completed a US$1b fixed to floating rate subordinated note offering due July 1, 2057, and reported third quarter 2026 basic and diluted EPS from continuing operations of US$0.39, with nine month EPS at US$1.86.
- The plan to underground an additional 67 miles of outage prone lines in 2027, with an ambition to reach 400 miles per year by 2028 subject to regulatory approval, highlights how CMS Energy is tying reliability spending directly to long term grid hardening.
- The focus now shifts to what this larger undergrounding push could mean for CMS Energy's investment narrative around regulated grid reliability spending.
Scan for other regulated utilities pursuing major grid upgrades and potential undergrounding opportunities by reviewing our curated 42 power grid technology and infrastructure stocks alongside CMS Energy's latest bond and reliability plans.
CMS Energy Investment Narrative Recap
To own CMS Energy, you need to believe the regulated Michigan utility model can support heavy grid and clean energy investment while keeping earnings on a steady path. The analyst consensus Narrative on Simply Wall St leans on that roughly US$24b capital plan and long term reliability work, including undergrounding. The recent US$1b subordinated note issue does not change the core thesis; it keeps the funding engine running.
The more immediate swing factor is execution on reliability and rate cases after a year where storms added extra operations costs and EPS from continuing operations came in at US$0.39 for the third quarter. The biggest current risk is still funding intensive projects in a way that preserves balance sheet flexibility, dividend coverage and regulatory support, as interest payments already strain earnings coverage.
The new fixed to floating rate subordinated notes due 2057 look most relevant. This security is callable, junior, unsecured and carries a variable coupon. It therefore sits low in the capital structure and is not cheap money. It still gives CMS Energy long dated capital that can support undergrounding plans and the shift toward Michigan rate base assets.
This type of instrument also interacts directly with catalysts that focus on reducing parent funding needs and limiting common equity issuance through 2030. If management sticks to that track, undergrounding and broader reliability projects could proceed while keeping share count growth and interest expense contained. If funding needs rise more than planned, that balance becomes harder to maintain and could weigh on future earnings per share.
CMS Energy's current narrative assumes revenue grows at 4.7% per year and earnings rise from US$862.0 million today to US$1.6 billion by 2029. This would mean earnings increase by roughly US$738 million as the business scales toward about US$10.3 billion of revenue in that same year.
Uncover why CMS Energy's fair value indicates a 7% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
The three fair value estimates from the Simply Wall St Community cluster between US$56.18 and about US$74.69, so you are seeing a wide gap in what private investors think CMS Energy is worth. When you layer that onto storm related earnings pressure and the fresh US$1b subordinated notes, you get very different narratives on long term performance. Explore those competing views before anchoring on any single fair value.
Explore 2 other CMS Energy fair value estimates, including one that suggests as much as 19% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns often come from independent thinking, so consider your own analysis and instincts.
- A great starting point for your CMS Energy research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for CMS Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CMS Energy's overall financial health at a glance.
Looking For More Investment Ideas Beyond CMS Energy?
If CMS Energy has put regulated infrastructure back on your radar, it can be useful to line it up against a wider bench of potential opportunities. The Simply Wall St Screener lets you filter for different risk and return profiles so you can spot listed utilities and other sectors that better match your own preferences.
- If you want lower volatility and sturdier fundamentals, start by scanning a 30 resilient stocks with low risk scores that may appeal if capital preservation sits near the top of your priority list.
- If you care most about resilient finances, compare CMS Energy with a list of solid balance sheet and fundamentals (25 results) where companies tend to carry stronger cash positions and more conservative leverage.
- If you prefer under the radar situations with room for the story to mature, sort through a 19 high quality undiscovered gems that focuses on quality metrics rather than headline popularity.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com