


Ollie's (OLLI) Stock Looks Overvalued On Current Earnings
Ollie's Bargain Outlet Holdings has seen its share price move around in recent years, which puts fresh focus on whether the current valuation lines up with the earnings power of the discount retailer. With the stock recently closing at US$94.81, the question is how much of the business performance story is already reflected in that figure.
- Over the past 5 years the stock has gained 40.0%, which puts real weight on whether the current price can be backed up by the chain's profit profile.
- The company relies on a closeout and discount model, so its long term earnings outlook may depend on how consistently it can source low cost inventory and convert that into stable margins and cash flow.
- There is a second opinion on Ollie's Bargain Outlet Holdings worth weighing. See what analysts think Ollie's Bargain Outlet Holdings's shares could be worth.
The issue now is whether today's Ollie's Bargain Outlet Holdings share price is justified by the earnings the business is generating.
If you are weighing whether Ollie's Bargain Outlet Holdings justifies its current earnings multiple, it can help to compare it with a wider group of retailers using 33 high quality undervalued stocks.
Has Ollie's Bargain Outlet Holdings Run Too Far on Earnings?
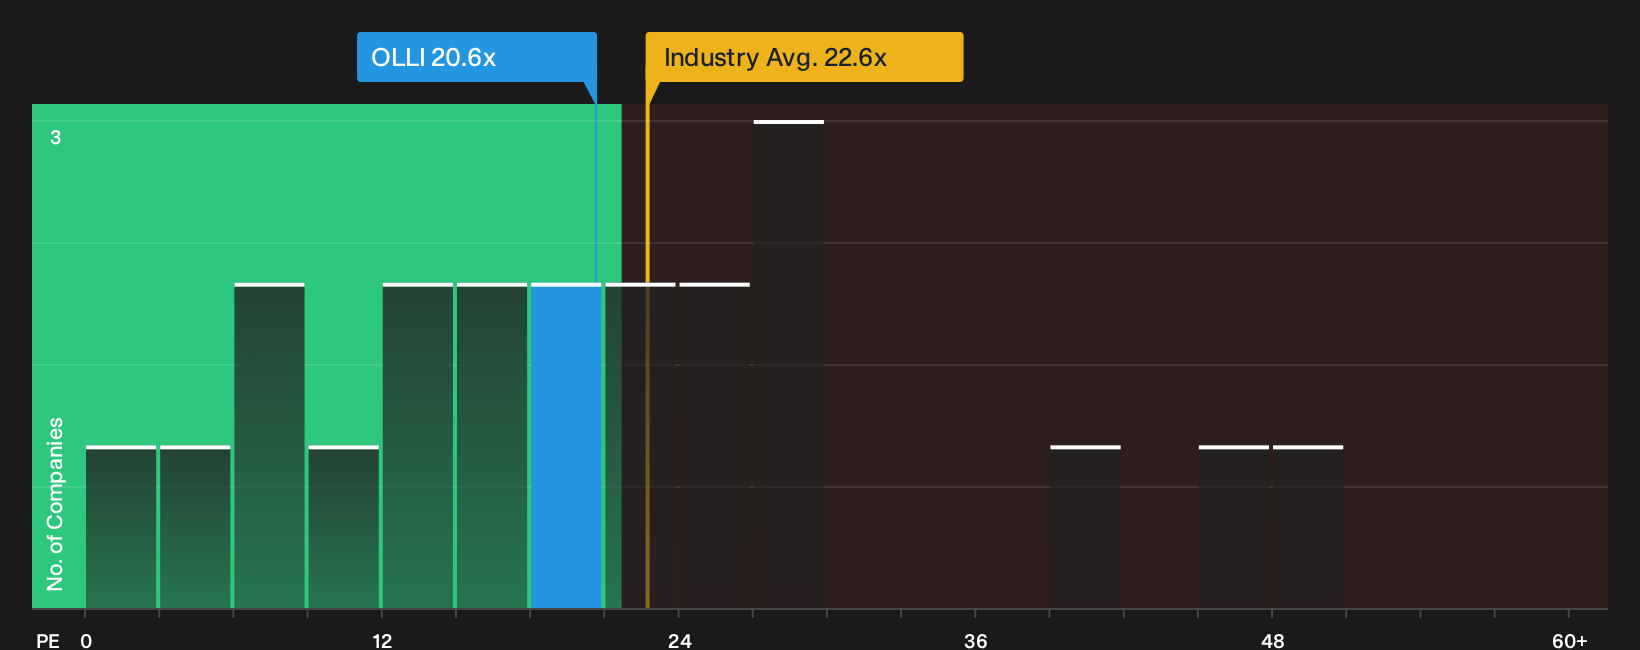
The P/E ratio suits Ollie's Bargain Outlet Holdings because earnings remain the main anchor for how investors frame the discount retailer's value. On this lens, the stock trades on about 20.6x earnings, which is slightly above both the multiline retail industry average of roughly 19.8x and the peer group on about 20.0x. That puts Ollie's Bargain Outlet Holdings on a modest premium to a broad set of comparable retailers, even before investors consider any company specific strengths or risks.
The tailored fair multiple implied by the valuation model comes in below the current 20.6x, which suggests the present price embeds a fuller view of the chain's earnings profile than that model would assign. For an investor, that means the market is already placing a relatively rich tag on each dollar of profit compared with what the Fair Ratio framework would point to. As a result, any case for upside from here needs to rest on factors beyond this single metric. Explore the numbers behind Ollie's Bargain Outlet Holdings's P/E valuation.
The Ollie's Bargain Outlet Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Ollie's Bargain Outlet Holdings bridge the gap between that P/E puzzle and the expectations baked into the share price by explaining what would need to happen to future growth, margins and earnings for the stock to be worth materially more or less than it is today. Rather than relying on a single multiple or one model output, each Narrative shows the assumptions behind its view of fair value so you can compare those inputs with the actual results as they are reported. They sit on Simply Wall St's Community page, where you can see different takes on the same set of financial possibilities.
Bulls see more embedded earnings power in Ollie's Bargain Outlet Holdings than bears give it credit for, even off the same set of recent results.
Bull case: roughly fairly valued
According to LunaRodas, a Simply Wall St Community investor who wrote the Narrative, the recent call hinges on how management handled competing forces.
"The beat is real, but Rob Helm flagged it immediately in prepared remarks, 'Earnings were better than expected, driven by IEEPA tariff refunds received in the quarter'…"
Discover why this Narrative puts Ollie's Bargain Outlet Holdings at roughly fairly valued.
Bear case: 25% overvalued
The bearish analyst Narrative on Simply Wall St frames the same business updates through a more cautious lens on what can be sustained.
"The closeout supply environment currently offers strong quantity and quality of deals, at the same time, reliance on suppliers with out-of-balance inventories and consolidation in retail could reduce deal availability or compress deal quality over time…"
Explore why this Narrative puts Ollie's Bargain Outlet Holdings at 25% overvalued.
One more Ollie's Bargain Outlet Holdings angle worth lining up
Analyst projections sketch out where profits and store economics might land a few years from now. This gives you a separate benchmark to compare with today's P/E and business story. Explore where analysts expect Ollie's Bargain Outlet Holdings to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com