


Crescent Energy (CRGY) Lifts Production And Keeps Its Dividend, Is It Still 39% Below Fair Value?
Crescent Energy (CRGY) just released a mixed third quarter update, combining sharply higher year-on-year revenue and production with a modest loss and a reaffirmed cash dividend that continues to draw interest from income-focused investors.
The market reaction has been cool in the near term, with Crescent Energy’s share price down 18.49% over the past week and 13.27% over the last month. However, the year-to-date share price return of 29.02% and 1-year total shareholder return of 27.84% suggest longer-term momentum has been positive as investors weigh stronger production and revenue against a small quarterly loss and the maintained dividend.
Look beyond Crescent Energy for other oil and gas producers showing resilient cash flows and shareholder returns using our curated 40 high quality undervalued stocks.
Crescent Energy now combines higher production, rising revenue and a maintained dividend with a share price that has pulled back sharply. That mix raises a simple issue: Is this business strength already fully reflected in the valuation today?
Most Popular Narrative: 39% Undervalued
Crescent Energy’s last close at $10.98 sits well below the analyst consensus Narrative fair value of $18.06, which points to a sizeable gap between price and modeled cash flows. The analyst consensus Narrative on Simply Wall St builds that view from aggregated analyst forecasts for revenue, earnings and margins, then runs them through a discounted cash flow framework using a 7.9% discount rate.
Crescent Energy’s programme of acquiring and integrating large positions in proven U.S. basins, illustrated by the approximately US$3.85b Devon Eagle Ford deal that adds about 68,000 Boe/d of production and more than 600 Tier 1 locations at roughly 3x EBITDA, is expanding the production base and reserve life in ways that can support higher revenue and earnings.
See why 19 investors see Crescent Energy as 39% undervalued.
Result: Fair Value of $18.06 (UNDERVALUED)
Still, the Crescent Energy story can break if the Devon Eagle Ford assets underperform, or if integration and synergy targets fall short and strain cash generation.
Find out about the key risks to this Crescent Energy narrative.
Another View On Crescent Energy’s Valuation
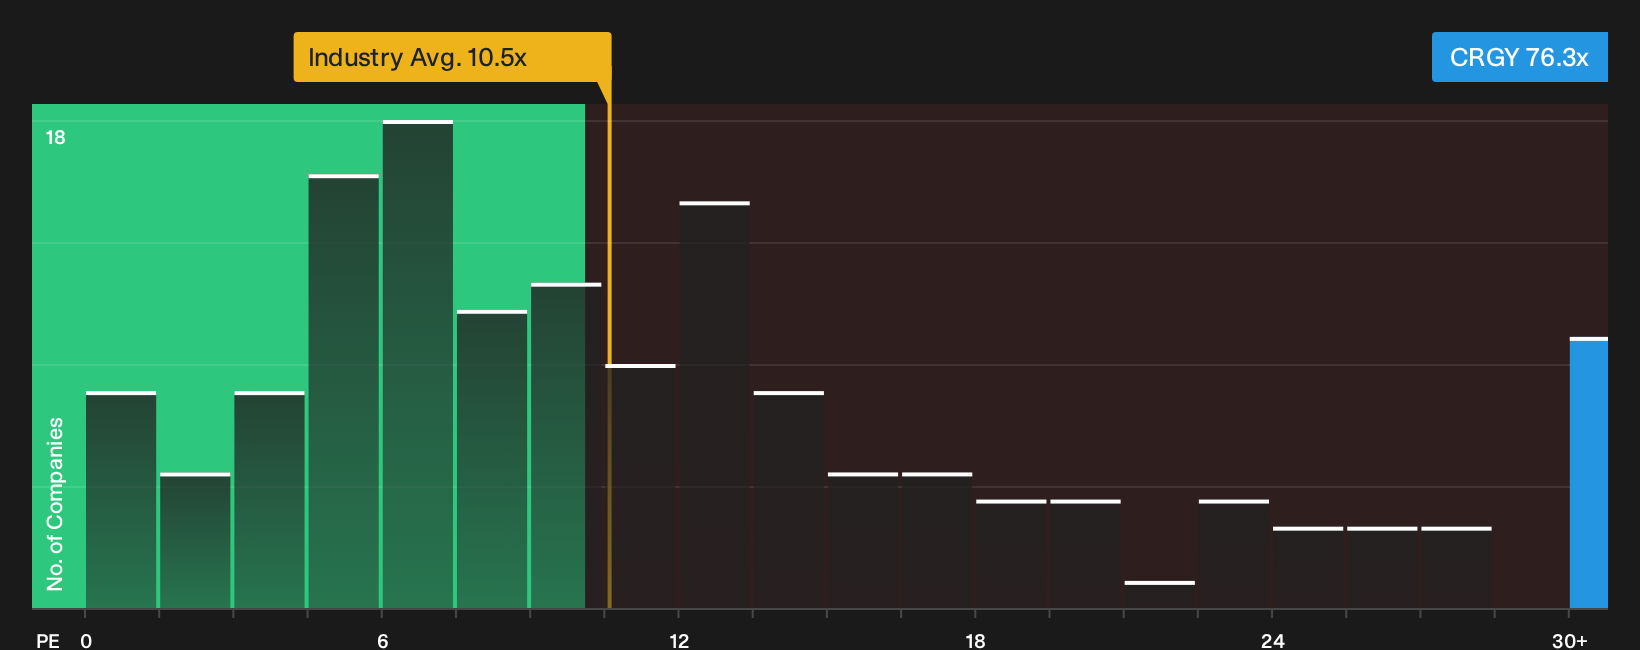
The first story around Crescent Energy leans heavily on discounted cash flows and analyst forecasts, but the simple earnings multiple tells a very different story. CRGY trades on a P/E of 76.3x, while the US Oil and Gas group sits near 10.3x and peers average 9.3x. The fair ratio points closer to 29x, which implies the share price already embeds a lot of execution success and leaves less room for disappointment if integration or cash generation fall short. Which lens do you trust more when the signals pull in opposite directions?
For investors who prefer to focus on how today’s price compares with earnings rather than cash flow models, the valuation gap is worth stress testing with your own scenarios, then weighing whether the premium multiple still feels acceptable once you factor in balance sheet risk, dilution and the pace of expected profit growth. See what the numbers say about this price — find out in our valuation breakdown.
To visualise how Crescent Energy’s earnings valuation compares with the sector, look at the current P/E against industry levels and ask whether a move toward the fair ratio feels more likely than not over your time horizon.
Next Steps
Mixed messages on Crescent Energy’s value and risk profile can be confusing, so move quickly from reading to testing the numbers yourself. Then pressure test both the upside and the downside by reviewing the 4 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Crescent Energy?
Do not stop at Crescent Energy. Fresh ideas often come from comparing it with other stocks that have different strengths, risks and income profiles.
- Target potential mispricing and compare Crescent Energy’s setup with a wider pool of quality opportunities through the Simply Wall St screener using 40 high quality undervalued stocks.
- Prioritise resilience by lining up Crescent Energy next to companies that pair conservative risk scores with steady fundamentals using the 31 resilient stocks with low risk scores.
- Hunt for overlooked opportunities by contrasting Crescent Energy with under-the-radar companies that still show robust financial quality using the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com