


Did Stronger Earnings Just Shift First Mid Bancshares (FMBH) Investment Narrative?
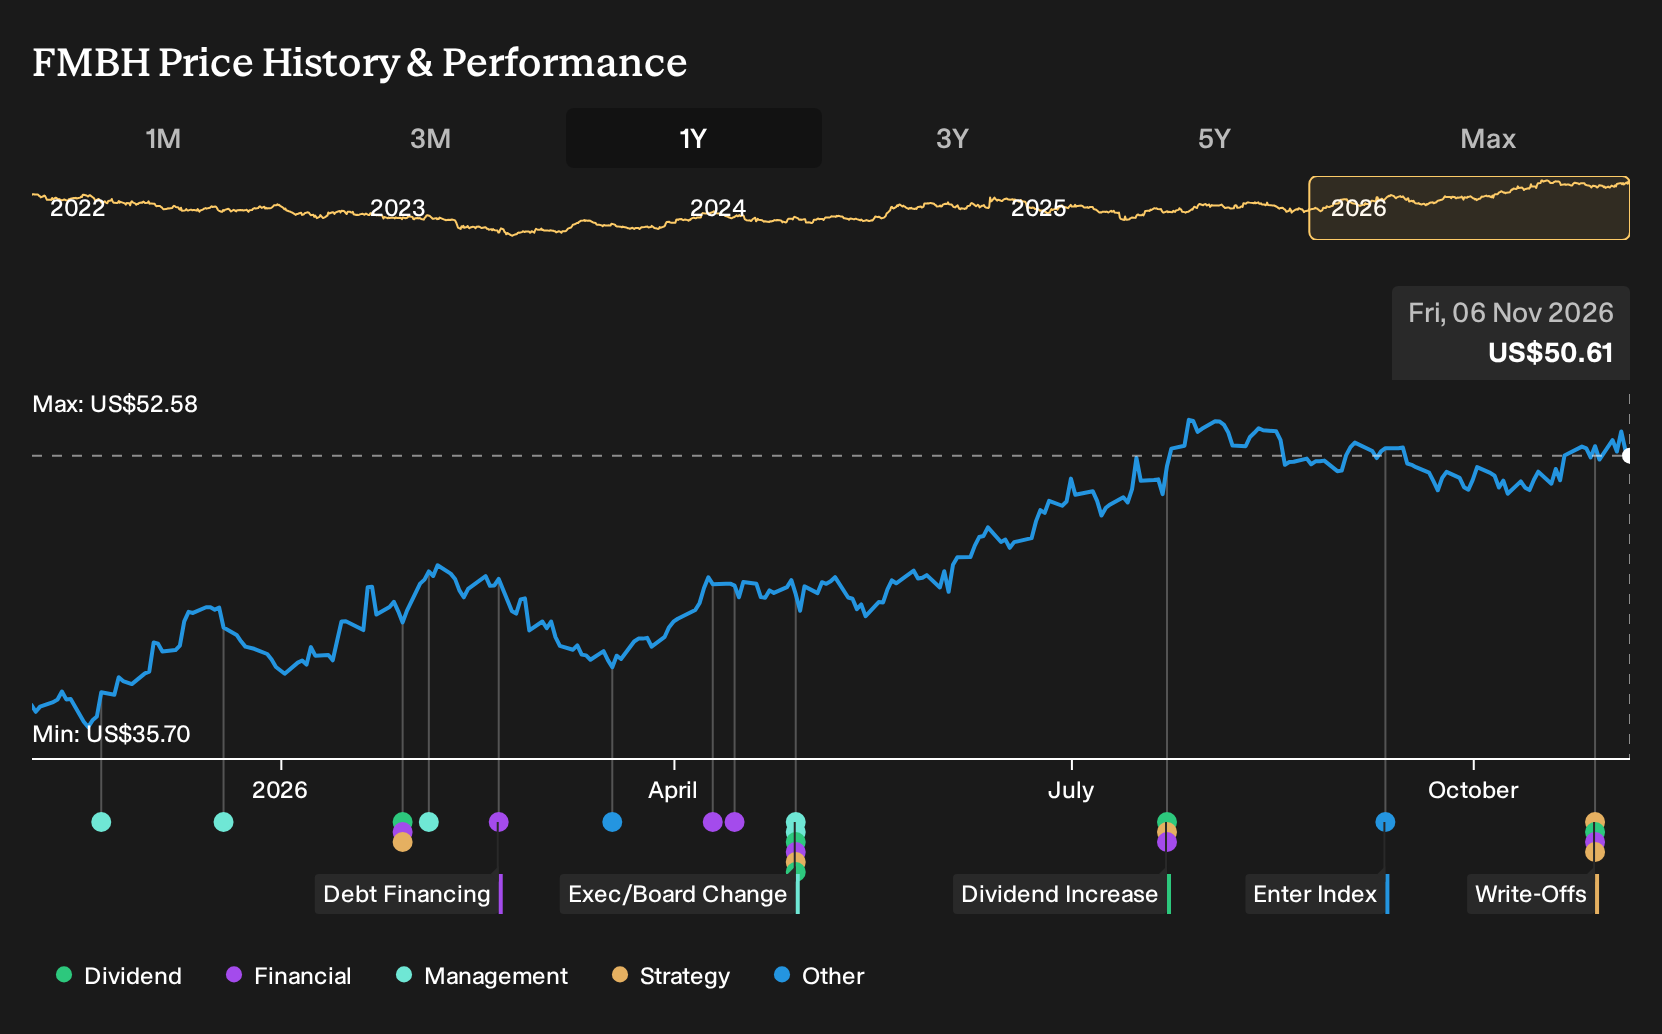
- First Mid Bancshares reported third quarter 2026 results with net interest income of US$79.38 million and net income of US$33.3 million, alongside affirmation of its regular quarterly dividend at US$0.26 per share, payable on December 1, 2026.
- Credit costs looked lighter as net charge offs for the third quarter came in at US$194,000, compared with US$1,588,000 in the same period a year earlier, which points to cleaner loans supporting the earnings line.
- The focus now turns to how First Mid Bancshares' investment narrative incorporates this profitability snapshot, particularly the reduced net charge offs.
Scan how First Mid Bancshares' latest dividend and cleaner credit profile compare with other income focused banks by reviewing the hand picked 7 dividend fortresses in the same space.
What Is First Mid Bancshares' Investment Narrative?
To own First Mid Bancshares, you need to be comfortable with a straightforward banking story. The bank leans on community focused lending, deposit gathering and fee services like wealth management and insurance. Recent quarterly earnings and net interest income figures show the engine currently throwing off solid profit, with net profit margins higher than last year. The regular US$0.26 dividend fits that picture, although the longer term record on payout stability has been described as uneven, so the latest affirmation does not fully settle that question.
In the short term, the cleaner net charge offs of US$194,000 take some pressure off credit quality worries and support the view that current earnings are backed by performing loans rather than heavy provisioning. The bigger swing factors still look tied to demand for loans, pricing on deposits and loans, and how much capital First Mid Bancshares needs to keep for growth versus returning cash. Forecasts point to earnings growth that is positive but not especially fast, alongside a P/E that is slightly above the wider US banks industry while still screened as good value versus some peers.
Yet the picture changes once you look at one awkward tension between that dividend profile and ...
There's only one way to know the right time to buy, sell or hold First Mid Bancshares. Head to Simply Wall St's company report for the latest analysis of First Mid Bancshares's Fair Value.
Exploring Other Perspectives
The Simply Wall St Community has only two fair value estimates for First Mid Bancshares, stretching from about US$100 to more than US$83,000 per share. This shows how far opinions can spread when private investors model their own scenarios. You can weigh those contrasting views against the recent dividend affirmation and cleaner charge offs to form your own read on future resilience.
Explore another First Mid Bancshares fair value estimate, including one that suggests as much as 164895% upside from the current price!
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so rely on your own judgment.
- A great starting point for your First Mid Bancshares research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for First Mid Bancshares. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate First Mid Bancshares' overall financial health at a glance.
Looking For More Investment Ideas Beyond First Mid Bancshares?
If the First Mid Bancshares story has you thinking about diversifying your watchlist, the Simply Wall St Screener can help you quickly surface other stocks that fit very specific checklists, from income resilience to balance sheet strength.
- For investors who want income with fewer surprises, filter for companies with stronger yield profiles and more robust payouts using the 7 dividend fortresses.
- If you are hunting for quality at a reasonable price, narrow the field to stocks that combine fundamentals with attractive pricing through the 40 high quality undervalued stocks.
- When capital preservation sits near the top of your priorities, focus on businesses that carry lower risk scores across key metrics using the 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com