


Should New Luxury Communities Require Action From Toll Brothers (TOL) Investors?
- Toll Brothers has recently opened or announced multiple upscale single family home communities in Georgia, Utah, and California, featuring large floor plans, premium finishes, and access to resort style amenities and well regarded school districts.
- The cluster of high price luxury launches, supported by Toll Brothers Design Studio personalization and model home showcases, indicates ongoing capital commitment to affluent buyers across several housing markets.
- We will now look at how Toll Brothers' accelerated luxury community roll out might influence the broader investment narrative around growth.
Scan Toll Brothers' luxury playbook against other high end housing developers by checking which builders feature on our hand picked list of solid balance sheet and fundamentals (25 results).
Toll Brothers Investment Narrative Recap
To own Toll Brothers, you need to be comfortable with a luxury focused builder that is still committing capital to new communities even after a quarter where earnings and margins came under pressure. According to Andrei_Niculescu, an investor in the Simply Wall St Community, the key swing factor is whether solid contract activity can eventually show up in deliveries and profitability.
In the near term, the main catalyst remains margin stabilization after the recent adjusted gross margin decline and higher SG&A burden. The biggest risk is that affordability and financing conditions keep weighing on profitability while Toll Brothers carries a large land and development pipeline and a newer management team executes on an expanded community base.
The new Kennemore community in Alpharetta is a good example of what Toll Brothers is leaning into. Large homes, premium finishes, resort style amenities and proximity to well regarded schools reinforce its focus on affluent buyers who may be less sensitive to mortgage pressure than the average buyer.
For investors, Kennemore links directly back to the near term catalysts. If communities like this convert existing demand and backlog into high value closings without further margin erosion, that supports the thesis Andrei_Niculescu laid out around contract strength. If incentives deepen or selling costs climb, the same expansion could magnify the margin risk instead.
On Andrei_Niculescu’s numbers, the narrative argues Toll Brothers reaches a fair value of $160.00 if revenue compounds at 7.9% a year and the business sustains a future profit margin of 11.7%. Together, these factors support higher earnings power on the current community and land base.
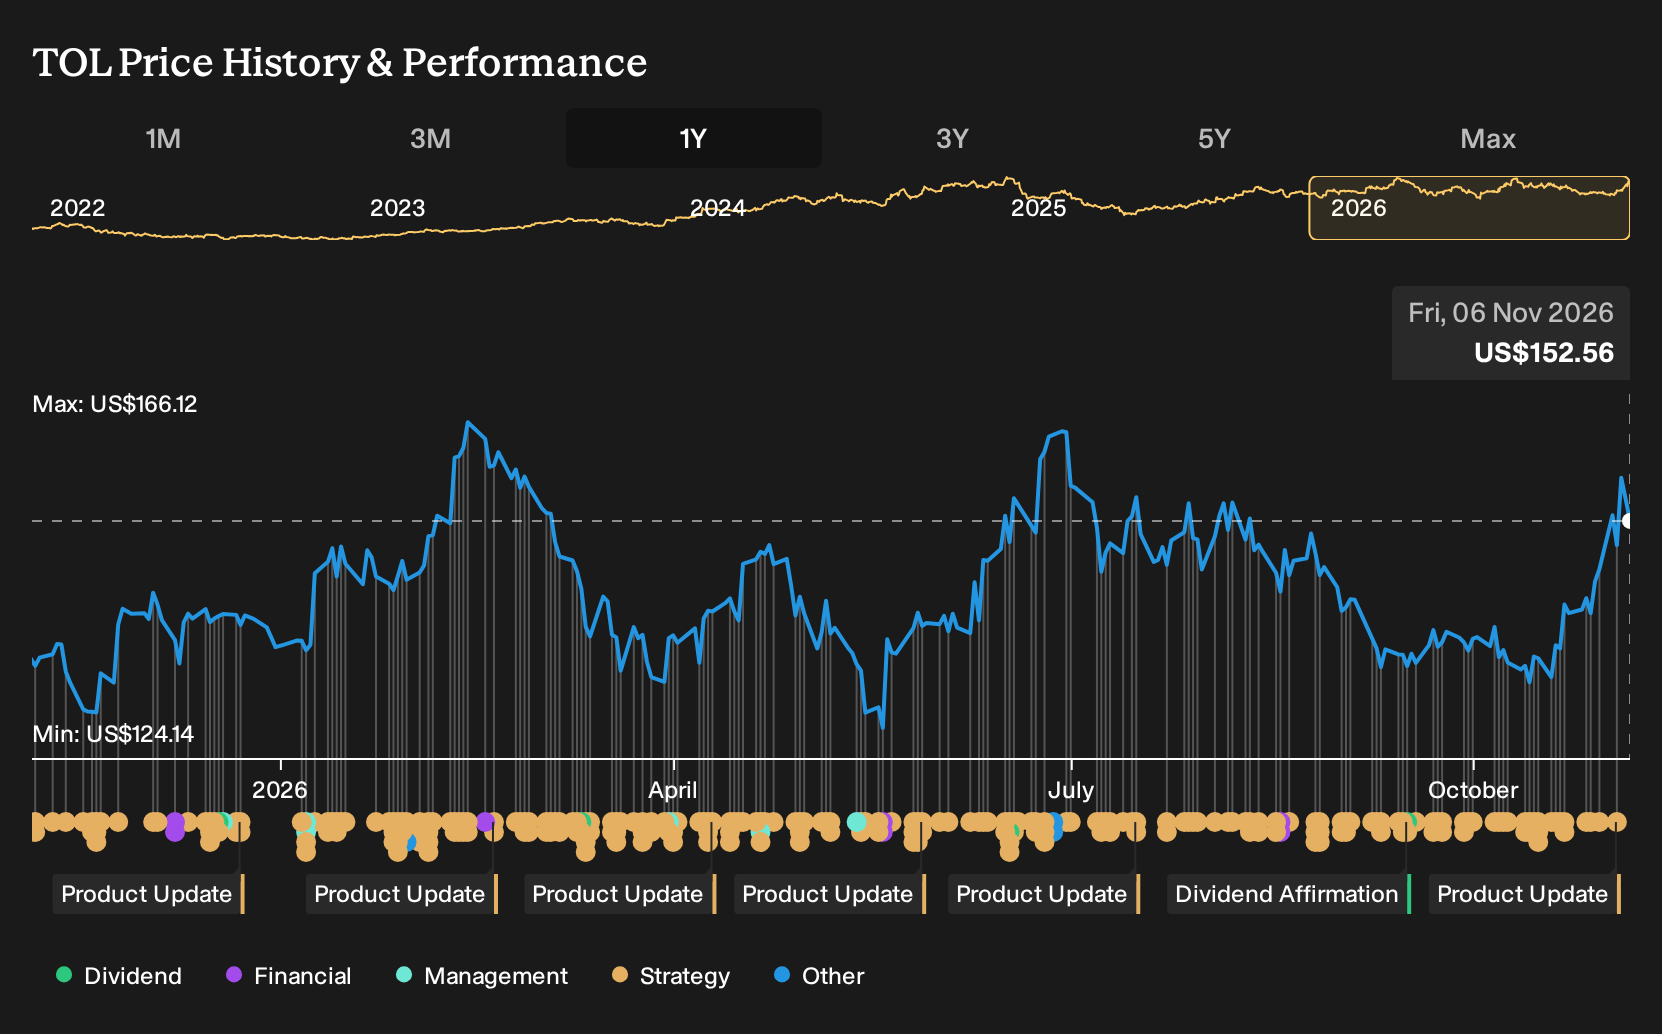
Discover why Toll Brothers' fair value indicates a 5% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the most optimistic analysts frame Toll Brothers very differently. Instead of fixating on margin pressure, they lean into the community expansion risk and assume it pays off, with revenue forecasts around US$13.4b and earnings near US$1.6b by 2029. These upbeat projections came before Kennemore and the new luxury launches, so you may see opinions shift as fresh information feeds into the models.
Explore 5 other Toll Brothers fair value estimates, including one that suggests as much as 63% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Toll Brothers research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Toll Brothers. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Toll Brothers' overall financial health at a glance.
Looking for more Toll Brothers style investment ideas?
If Toll Brothers has sharpened your focus on quality and resilience, it can help to line it up against other opportunities using the Simply Wall St Screener. That way you can see how different businesses stack up on factors that matter to you, whether that is balance sheet strength, income potential, or lower perceived risk.
- If capital preservation sits high on your priority list, start with companies that score well on stability metrics through the 31 resilient stocks with low risk scores.
- If dependable income is the main attraction, focus on businesses that pair higher yields with coverage checks by reviewing the 7 dividend fortresses.
- If you want to filter for financially robust operators beyond Toll Brothers, compare it with peers that combine solid finances and fundamentals using the list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com