


Did Adobe AI Partnership Just Shift Disney (DIS) Stock's Investment Narrative?
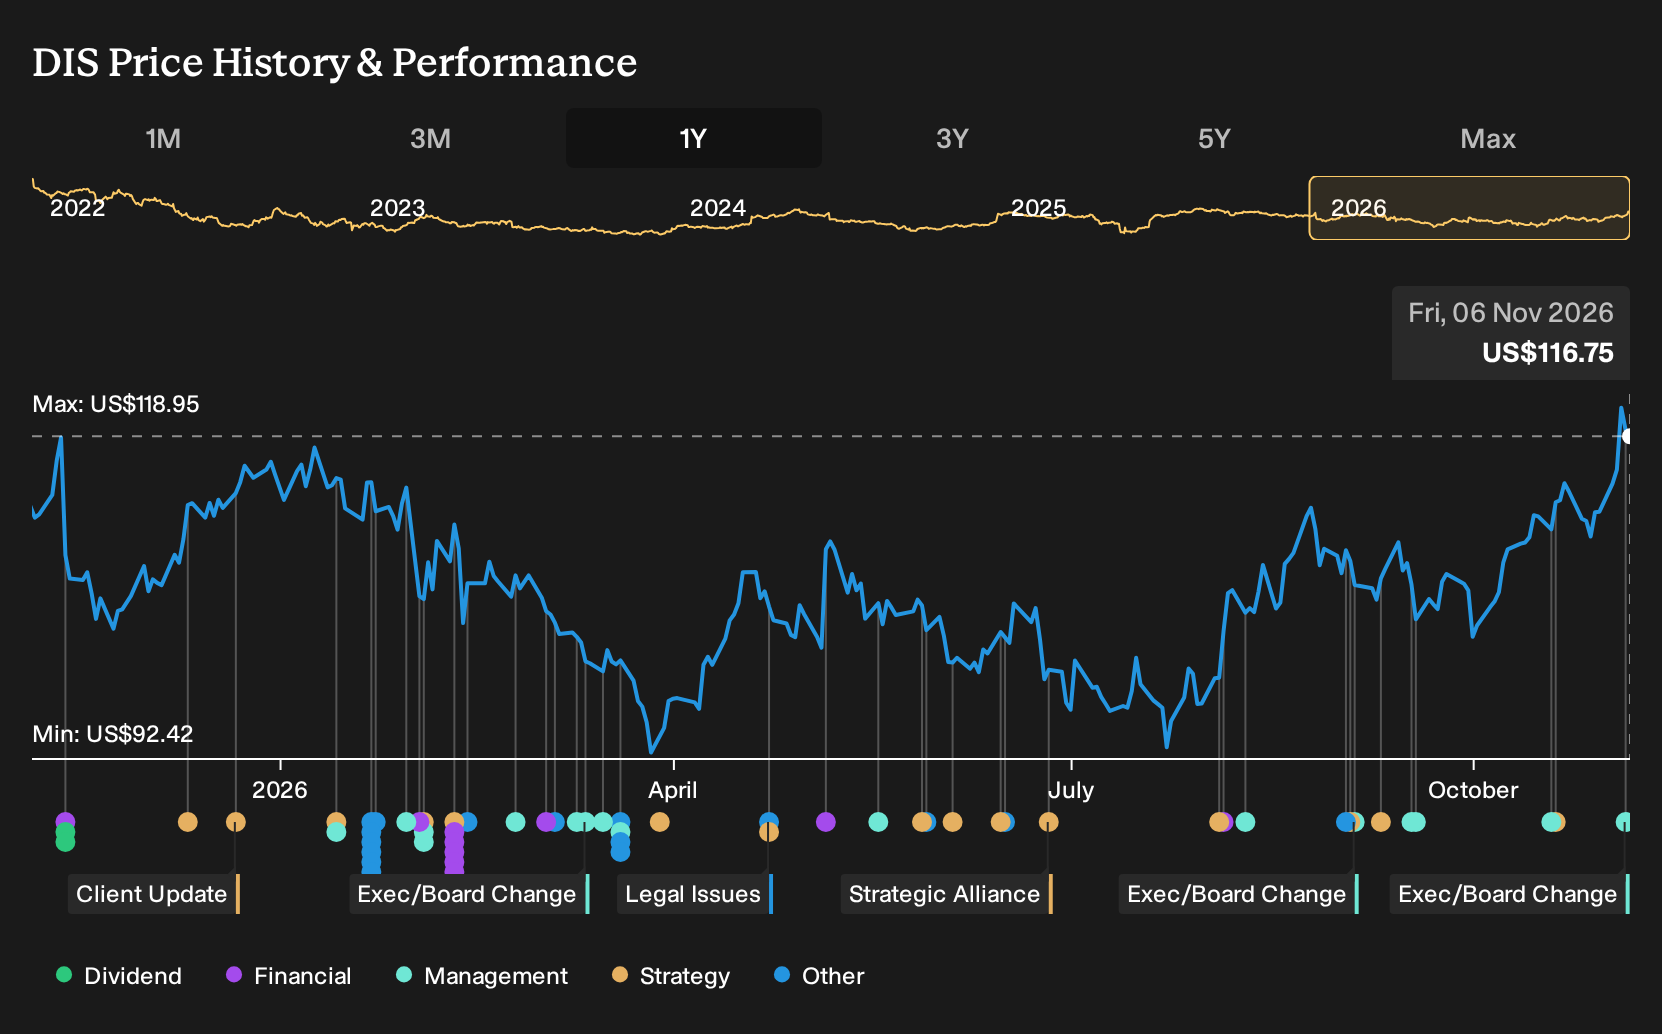
- Adobe and The Walt Disney Company have entered a multi year alliance that deploys custom AI tools like Adobe Firefly across Disney’s content production, parks planning, cruise development and internal innovation labs.
- The deal gives Disney early access to Adobe’s AI media technology, which could affect how efficiently the group develops shows, attractions and guest experiences across its existing intellectual property portfolio.
- We will now look at how Disney’s Adobe AI alliance could influence the broader investment narrative around earnings power and efficiency.
Walt Disney Investment Narrative Recap
Owning Walt Disney means believing its Experiences segment, live sports and direct to consumer platforms can keep turning well known franchises into cash flow, even as streaming and park cycles shift. The analyst consensus Narrative on Simply Wall St leans on Experiences expansion and SVOD profitability. The biggest short term swing factor remains how effectively the unified Disney+, Hulu and ESPN apps support ad and subscription revenue.
The key operational risk still sits in streaming ad softness and potential consumer weakness in Asian parks, which could drag on earnings despite cruise and park investments. The Adobe AI alliance and recent concert programming look incremental for now. They appear more like execution tools and marketing levers than major near term earnings drivers.
The most relevant recent development for this story is Amit Ziv’s promotion to CFO of Disney Entertainment Television. That role sits close to where streaming economics, content spending and ad revenue all intersect. A financially focused leader in that seat can influence how aggressively Disney leans into content budgets, bundling and pricing tests across TV and direct to consumer.
Those choices feed directly into the main catalysts and risks already flagged. Cost discipline and smarter monetisation can support efforts to achieve double digit SVOD margins and maintain Experiences reinvestment. On the other hand, if ad markets remain weak or legal costs from streaming disputes rise, Ziv’s remit could focus more on protecting profitability and prioritising projects that clear a higher financial hurdle.
Walt Disney's current analyst story points to about US$113.7b in revenue and US$13.5b in earnings by 2029, based on an assumed 4.8% yearly revenue growth rate and a move from roughly US$8.6b in earnings today to that 2029 consensus level, which represents an earnings increase of about US$4.9b.
Uncover why Walt Disney's fair value indicates an 8% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
The Simply Wall St Community supplies five fair value views for Walt Disney, clustering between about US$122.27 and US$134.63. Retail opinions already span a tight but meaningful band. Those estimates were formed before the Adobe AI alliance, the new entertainment TV CFO and the latest parks and streaming trends, so explore multiple viewpoints before deciding how this fits your own thesis.
Explore 4 other Walt Disney fair value estimates, including one that suggests potential upside of as much as 15% from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Walt Disney research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Walt Disney. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Walt Disney's overall financial health at a glance.
Looking for more Walt Disney style investment ideas?
If the Walt Disney story has sharpened your thinking about media, cash generation and balance sheet quality, use that momentum to widen your watchlist with companies that fit clear financial themes through the Simply Wall St Screener.
- For investors who want potential mispricing backed by solid fundamentals, scan a curated set of 40 high quality undervalued stocks that may warrant a closer look.
- If income is your focus and you care about reliability, check out a group of 7 dividend fortresses that combine high yields with an emphasis on resilience.
- When capital preservation matters most, narrow your search to 31 resilient stocks with low risk scores and see which businesses align with a more defensive approach.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com