


Is Omnicell (OMCL) A Bargain As Higher Guidance Resets Its Valuation?
Why Omnicell’s latest guidance move matters
Omnicell (OMCL) reset expectations on 29 October, pairing higher full year revenue guidance with stronger earnings per share from continuing operations. The update followed its third quarter report and focused attention on recurring software and services.
Omnicell’s share price has been choppy, with a 4.24% 1 month share price return and a small 7 day gain, yet the year to date share price is still down 17.28% while the 1 year total shareholder return of 4.65% hints at gradually improving sentiment around the turnaround in recurring software and services.
Look beyond Omnicell’s reset guidance and see how other healthcare technology stocks with recurring revenue stories compare in our curated 35 healthcare AI stocks.
Omnicell now trades at a clear discount to both analyst targets and intrinsic value estimates after its guidance reset. Is that a genuine mispricing, or a fair penalty for execution and regulatory risk, given the recent move in recurring software and services?
Most Popular Narrative: 35% Undervalued
On the widely followed narrative, Omnicell’s fair value sits at $57.43, well above the recent $37.34 close. This view puts a lot of weight on its recurring software and services story actually playing out.
The continued rollout and adoption of the cloud-native OmniSphere platform across Omnicell's customer base will simplify enterprise-wide medication management, make adding new features and integrating advanced analytics much easier, and accelerate the company's transition to higher-margin, recurring SaaS-based revenues, supporting improved revenue predictability and net margins.
See why 6 investors see Omnicell as 35% undervalued.
Analysts behind this view are using a 7.69% discount rate, with revenue growth assumptions of about 2.7% a year and a long term profit margin near 4.7%. They then capitalize those earnings on a future P/E of roughly 55.8x to arrive at that $57.43 figure. That implies a meaningful gap between today’s P/E in the high 30s and the richer multiple the narrative requires on projected 2029 earnings.
For you as an investor, the key judgment is whether Omnicell’s push into SaaS, services and the OmniSphere platform, along with its 3.6% net margin and positive earnings growth over the past year, can reasonably support those earnings and multiple assumptions in a market where its expected revenue and earnings growth are both slower than the broader US market. The market is currently pricing in a discount of about 36% to Simply Wall St’s own future cash flow estimate of $58.39 per share, which still leans on the same core idea that recurring software and services make Omnicell’s cash flows more dependable over time.
Result: Fair Value of $57.43 (UNDERVALUED)
Still, Omnicell’s story can break if tariff costs squeeze margins harder than expected or if hospitals delay large automation projects and slow new contracts.
Find out about the key risks to this Omnicell narrative.
Another View on Omnicell’s valuation
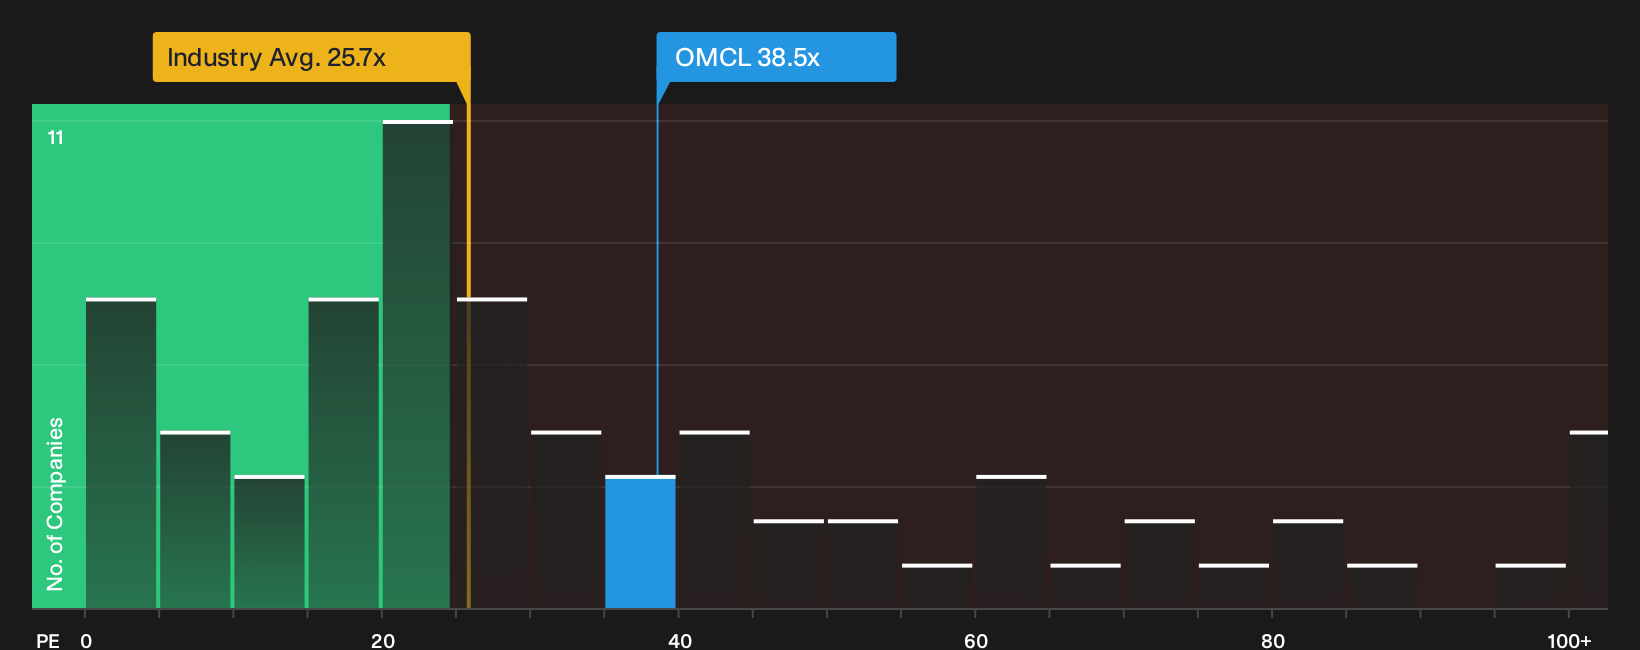
Omnicell might look cheap against a $57.43 fair value built from analyst earnings forecasts, yet the current P/E of 38.5x tells a tougher story. That multiple is higher than both peers at 37.2x and the US Medical Equipment industry on 25.7x, and it also sits above a fair ratio of 23.8x.
Put simply, the share price already embeds a richer earnings multiple than those comparison points. This raises the risk that any stumble in the recurring software or services ramp is punished quickly. Which version of “value” do you trust more when the profit growth path is still being rebuilt?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Opinions on Omnicell’s reset are split. This makes it an important moment to move quickly, review the underlying data yourself, and decide whether the optimism around its potential rewards matches your risk appetite by checking the 4 key rewards.
Looking for more Omnicell investment ideas?
Do not stop with Omnicell alone, because broadening your watchlist with a few focused screeners can help you spot opportunities you might otherwise miss.
- Target resilience by checking a list of solid balance sheet and fundamentals (25 results) that can handle tougher conditions without stretching their finances.
- Hunt for potential bargains through a 38 high quality undervalued stocks that combines quality fundamentals with discounted prices.
- Prioritize sleep-at-night holdings by reviewing a 31 resilient stocks with low risk scores that aims to limit unpleasant surprises.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com