


Is Madison Square Garden Entertainment (MSGE) Undervalued After Its Return To Profit?
Madison Square Garden Entertainment (MSGE) just opened fiscal 2027 with a Q1 earnings report that turned a prior loss into a profit, giving investors fresh numbers and clearer visibility on upcoming event-driven revenue.
Recent trading tells a mixed story. The share price rose 2.20% on the day of the Q1 release but is down 4.68% over 30 days and 1.29% over 90 days, while the year-to-date share price return of 41.81% and a 3-year total shareholder return of 164.18% point to momentum that has been building over a longer horizon as investors react to Madison Square Garden Entertainment’s swing back to profitability, strong event calendars, headline-grabbing artist disputes and ongoing share repurchases.
Scan how Madison Square Garden Entertainment’s Q1 rebound compares with other live entertainment and media plays showing strong fundamentals in our curated list of 19 high quality undiscovered gems
Madison Square Garden Entertainment just flipped back to profit, and the stock has already run hard this year. Yet analyst targets and intrinsic estimates still sit meaningfully higher. Which reference point looks closest to fair value?
Most Popular Narrative: 16% Undervalued
On the most followed narrative, Madison Square Garden Entertainment’s fair value of $91.63 sits well above the last close of $77.06. This puts the recent rally in context and raises the question of whether the market is fully pricing its venue economics.
Improved utilization and a stronger event pipeline at key Madison Square Garden Entertainment venues, including management being nearly 90% to its fiscal 2027 bookings goal for the Garden and about 60% for theaters, along with the cash component of arena license fees that is expected to be about US$47 million in fiscal 2027 with annual 3% escalators through 2055, can increase visibility on earnings and support future free cash flow that could fund additional buybacks.
See why 1 investors see Madison Square Garden Entertainment as 16% undervalued.
Result: Fair Value of $91.63 (UNDERVALUED)
Still, the story can break if legal fallout from the data breach inflates costs, or if premium hospitality and sponsorship spending proves less repeatable than analysts expect.
Find out about the key risks to this Madison Square Garden Entertainment narrative.
Another View On Madison Square Garden Entertainment’s Valuation
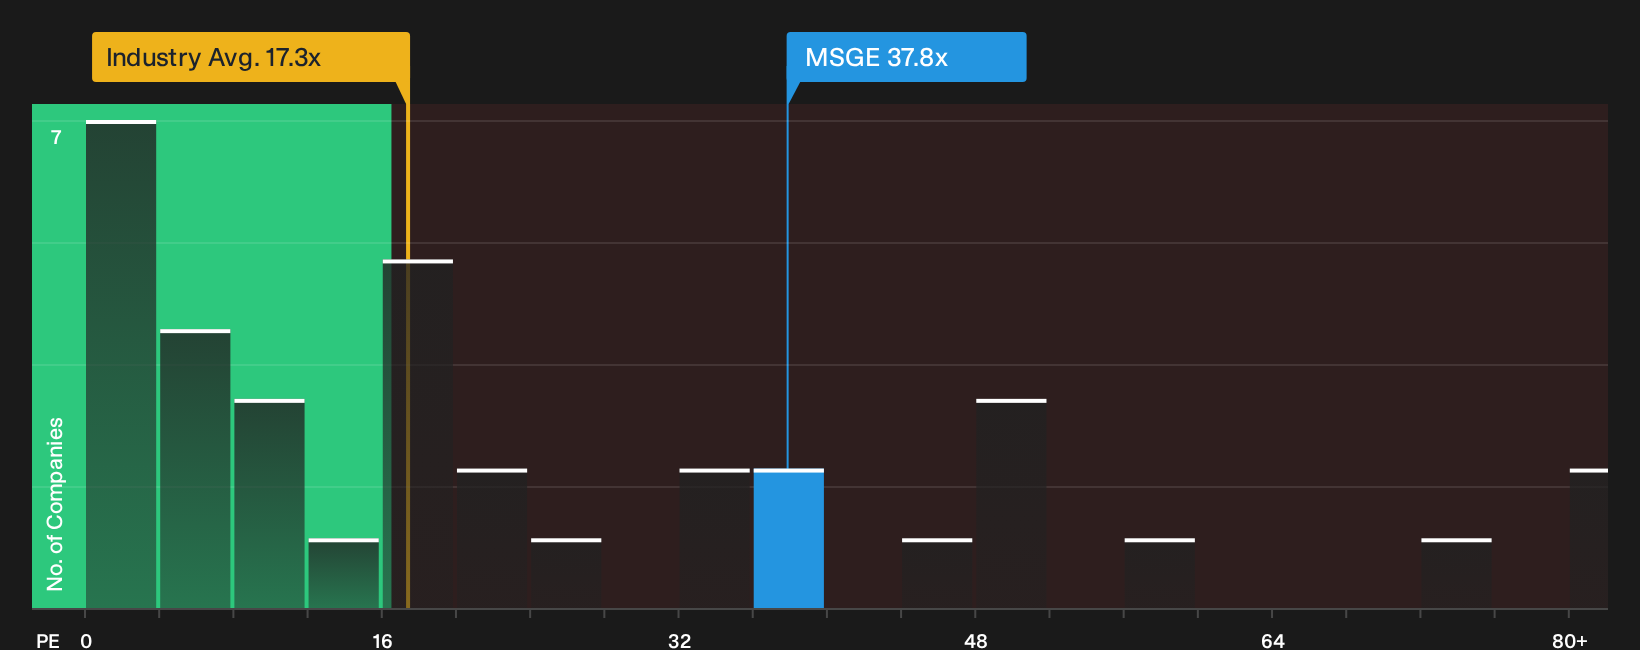
That 16% “undervalued” fair value hinges on future cash generation. A different lens, the current P/E of 37.8x, tells a tougher story. Madison Square Garden Entertainment trades at more than double the US Entertainment average of 17.3x and well above its 19x fair ratio. Is the market overpaying for momentum or correctly pricing its venue assets?
For a closer look at how this high earnings multiple compares with both peers and the fair ratio that the market could move toward over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Madison Square Garden Entertainment is split, with clear risks and meaningful potential rewards both on display, so move fast and test the numbers yourself. To see both sides set out in one place, review the 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond Madison Square Garden Entertainment?
If you stop with just Madison Square Garden Entertainment, you might miss other opportunities that better fit your risk tolerance, income needs, or valuation preferences.
- Target potential mispricing by scanning a curated set of high quality companies using the 38 high quality undervalued stocks.
- Strengthen the foundation of your portfolio by focusing on financially resilient businesses through the list of solid balance sheet and fundamentals (25 results).
- Dial down portfolio stress by concentrating on steadier opportunities with the 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com