


Earnings And Deal Pipeline Might Change The Case For Investing In Gallagher (AJG)
- Arthur J. Gallagher reported third quarter 2026 revenue of US$3,976 million and net income of US$403 million, while confirming an active mergers and acquisitions pipeline and declaring a regular US$0.70 per share dividend payable in December 2026.
- The appointment of Tom Doyle as future CEO of the Benefits & HR Consulting Division signals planned leadership continuity in a unit exposed to employer demand for data informed benefits and HR advice.
- Next is an examination of how Arthur J. Gallagher's earnings profile could influence the existing investment narrative around growth and M&A.
Scan how Arthur J. Gallagher's acquisitive playbook compares with peers hunting for growth through dealmaking by reviewing our hand picked 19 high quality undiscovered gems in the insurance and financial services space.
Arthur J. Gallagher Investment Narrative Recap
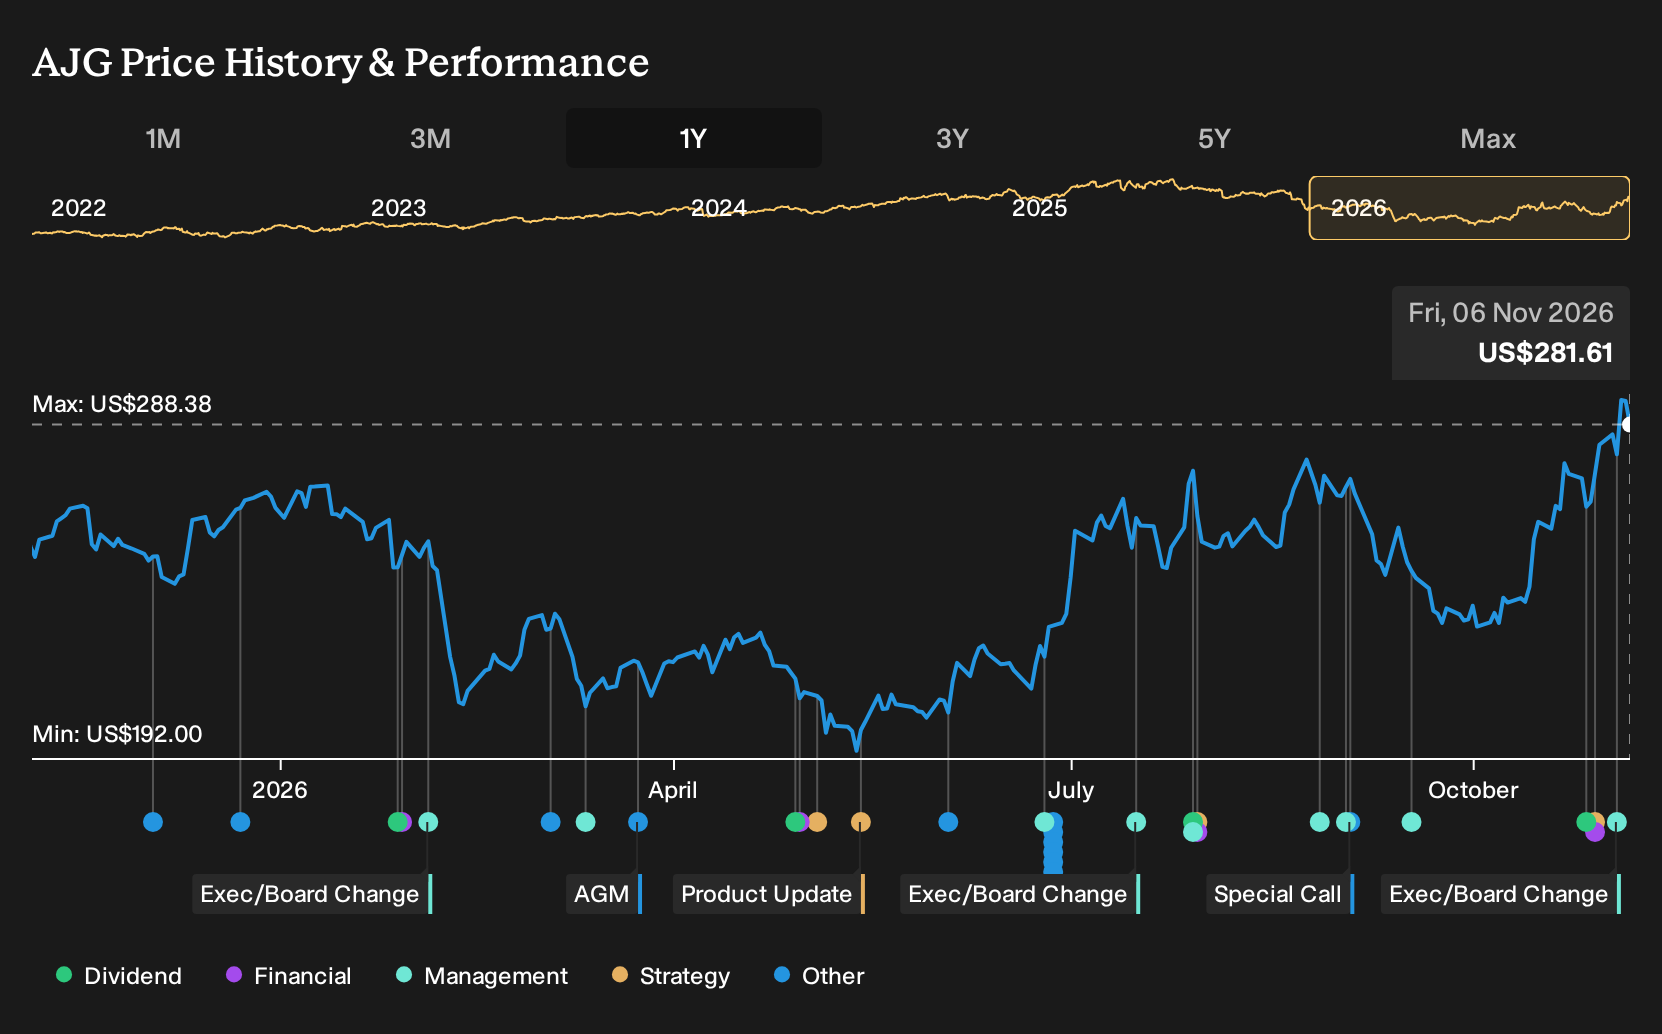
To own Arthur J. Gallagher, you need to be comfortable with a broker that leans heavily on steady fee income, cost efficiency projects and a busy acquisition program. The latest quarter showed higher revenue and profit versus a year earlier, which supports that thesis, but easing property pricing and a high P/E mean expectations already sit high in the short term.
The most important near term swing factor is execution on M&A and integration work, including AssuredPartners and the smaller tuck ins. The biggest operational risk is that softer property pricing and any delay in AI and automation savings leave earnings tracking below what the current valuation implies.
The recent update on mergers and acquisitions looks most relevant here. Management reported 5 tuck in deals in the third quarter, representing about US$100 million of estimated annualized revenue and 21 deals year to date with roughly US$225 million, plus an active pipeline at around US$300 million of revenue.
For you, that pipeline acts as a clear catalyst, because the whole Arthur J. Gallagher story leans on adding revenue and EBITDAC through disciplined dealmaking alongside organic growth. The risk sits in integration complexity and purchase discipline, especially with a high level of debt and explicit cost saving targets already embedded in many investor expectations.
Analysts expect Arthur J. Gallagher's revenue to reach US$20.7b and earnings to come in at US$2.9b by 2029, which implies revenue growing at 9.5% per year and an earnings increase of about US$1.2b from US$1.7b today.
Uncover how Arthur J. Gallagher's fair value indicates a 3% potential upside to its current price that may be short-lived.
Exploring Other Perspectives
One alternative view focuses less on M&A risk and more on the sheer scale of the AssuredPartners integration. The most pessimistic analysts were already assuming revenue of about US$20.3b and earnings of US$2.9b by 2029, yet still arrived at a lower price target. With Tom Doyle stepping up inside Benefits, those pre news assumptions may now face an update.
Explore 3 other Arthur J. Gallagher fair value estimates, including one that suggests as much as 14% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Arthur J. Gallagher research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Arthur J. Gallagher. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Arthur J. Gallagher's overall financial health at a glance.
Looking For More Investment Ideas Beyond Arthur J. Gallagher?
If you want to pressure test the Arthur J. Gallagher thesis against other opportunities, cast a wider net using the Simply Wall St Screener. Comparing this broker against a few different types of businesses can sharpen your sense of risk, return profile and balance sheet strength.
- For investors who care most about quality at a reasonable entry point, scan a curated 38 high quality undervalued stocks that combine solid fundamentals with more modest pricing.
- If capital preservation sits high on your list, stress test your options with a 31 resilient stocks with low risk scores that score well on resilience and downside protection.
- For a focus on financial robustness and staying power, broaden your watchlist using a list of solid balance sheet and fundamentals (25 results) that can better withstand tougher conditions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com