


Learn Why The Bull Case For Southside Bancshares (SBSI) Could Change Following Strong Quarterly Earnings
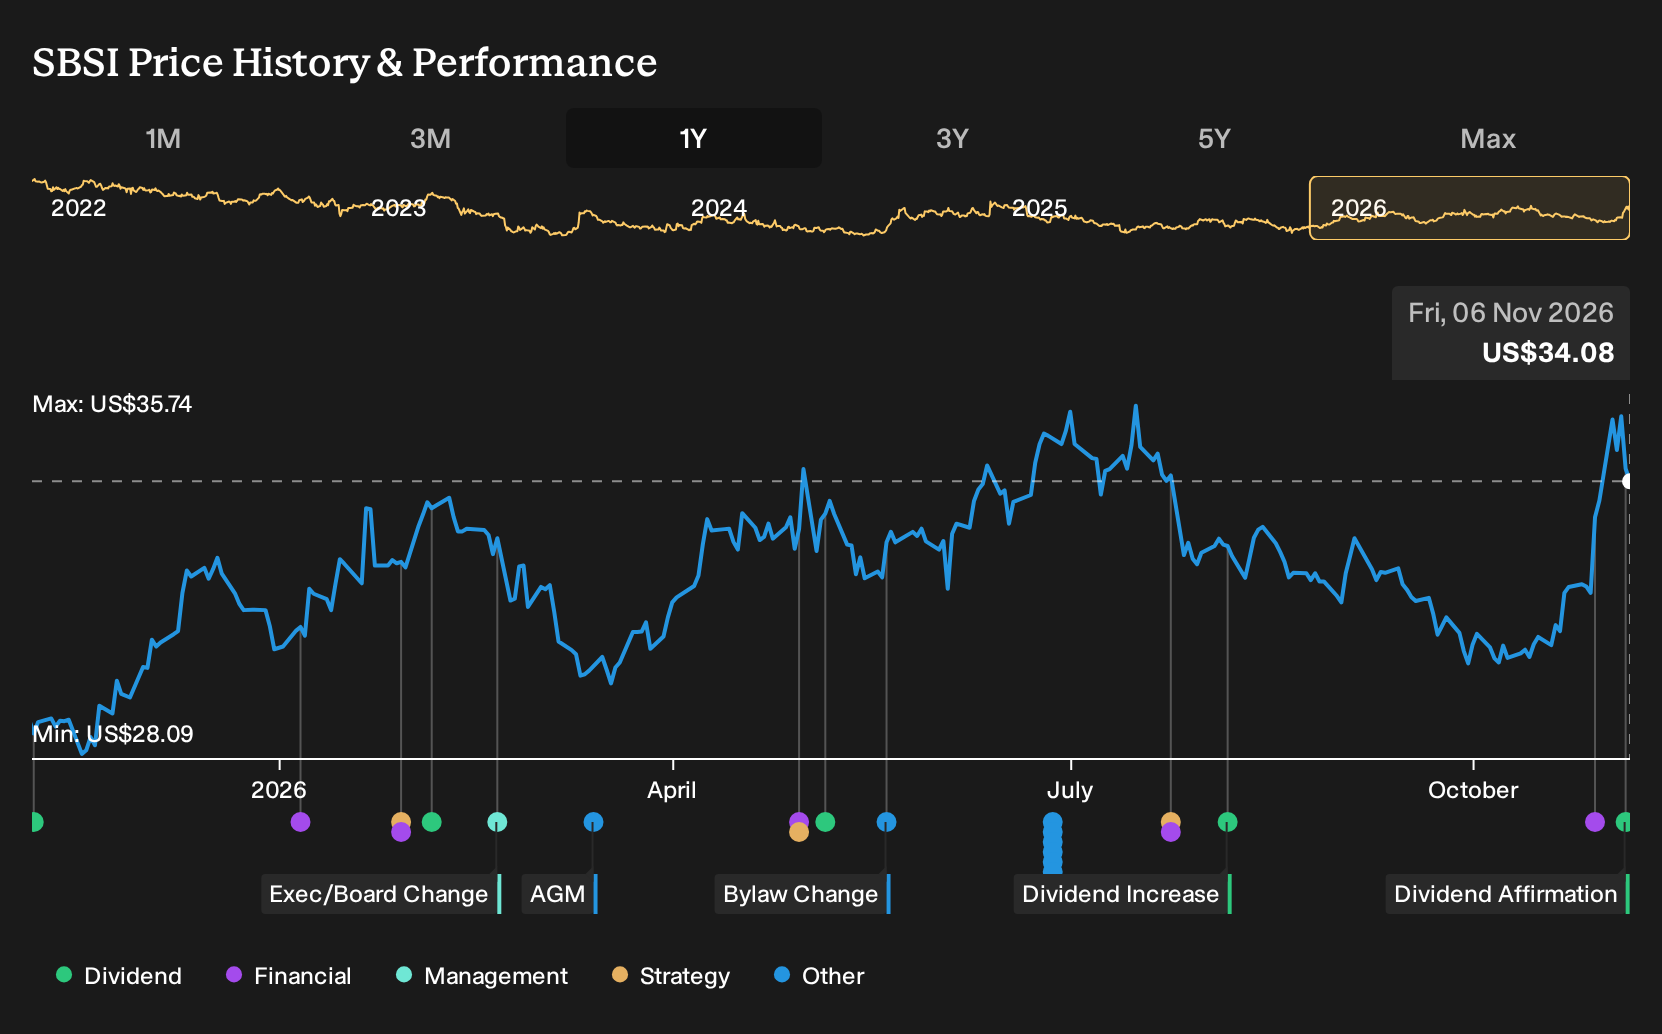
- Southside Bancshares reported third quarter 2026 net interest income of US$60.3 million and net income of US$27.98 million, with basic earnings per share from continuing operations of US$0.94.
- The board also approved a regular quarterly cash dividend of US$0.37 per common share, paid on December 9, 2026.
- Investors may now reassess how Southside Bancshares' quarterly earnings performance relates to the existing investment narrative around margin and balance sheet actions.
Scan how Southside Bancshares' mix of earnings power and regular payouts compares with other income-focused opportunities using our curated 7 dividend fortresses in the current market.
Southside Bancshares Investment Narrative Recap
To own Southside Bancshares, you need to be comfortable with a traditional Texas focused bank that is leaning on net interest income, loan repricing and securities repositioning while wrestling with funding costs. The latest quarter shows earnings power in place, but margin pressure, deposit competition and wholesale funding costs still sit at the center of the near term story.
The important near term swing factor remains whether management can protect net interest margin while redeploying into higher yielding assets. Recent results help that narrative but do not remove the risk from volatile deposits and swap funding costs. If those pressures persist or worsen, the earnings profile could face renewed strain.
The most relevant fresh data point is Southside Bancshares' third quarter 2026 earnings release. Net interest income of US$60.3 million and net income of US$27.98 million, with basic EPS from continuing operations of US$0.94, provide a clearer view of how balance sheet repositioning is flowing through the income statement at this point.
Those figures sit alongside the earlier actions to rotate out of lower yielding municipal bonds and redeem higher cost subordinated notes. Together, they allow an assessment of whether asset sensitivity and Texas loan growth are doing enough to offset margin compression, wholesale funding reliance around US$1.4b and recent deposit volatility that could still limit balance sheet expansion.
Southside Bancshares' current analyst narrative points to forecast revenue of US$336.4 million and earnings of US$110.6 million by 2029, based on an assumed 11.1% yearly revenue growth rate and an earnings increase of about US$34.6 million from US$76.0 million today.
Uncover why Southside Bancshares' fair value is essentially in line with its current price.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community sit between US$34 and about US$46.93, which already shows how far apart opinions on Southside Bancshares can land. Those views were formed before the recent dividend affirmation and quarterly earnings. Use them as a starting point, then weigh margin pressure, funding costs and Texas loan growth to test several alternative angles on future performance.
Explore another Southside Bancshares fair value estimate, including one that suggests it could be worth just $34.00.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Southside Bancshares research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Southside Bancshares. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Southside Bancshares' overall financial health at a glance.
Looking for more investment ideas beyond Southside Bancshares?
Once you have formed a view on Southside Bancshares, it can help to widen the lens and compare it with other listed businesses that match different income, value or risk profiles. The Simply Wall St Screener lets you do that quickly by surfacing focused sets of companies that share the traits you care about most.
- If you want to balance income with staying power, start with a list of solid balance sheet and fundamentals (25 results) that can help you focus on businesses with stronger financial footing.
- For investors hunting for value opportunities, use the 38 high quality undervalued stocks that filters for companies where fundamentals and price may be out of sync.
- If your priority is stability over excitement, consider a 31 resilient stocks with low risk scores that highlights companies with more resilient risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com