


Hut 8 (HUT) Stock Looks Stretched Despite Its 38% Monthly Slide
Hut 8 has dropped sharply over the past month, even as the business pushes deeper into AI data centers and large share repurchases, which puts a spotlight on whether the current share price lines up with what its sales can support. With the stock now trading at US$52.65, investors are asking how much of the recent news is already embedded in the valuation that is implied by its revenue base.
- Hut 8 shares are down about 37.5% over the past 30 days, which puts recent sellers and long term holders on opposite sides of the same question about what its sales are really worth.
- The company has been signing long dated AI data center contracts and funding expansion and buybacks with Bitcoin sales and new credit, which can reshape how quickly reported revenue might scale relative to the capital being put to work.
- There is a second opinion on Hut 8 worth weighing. See what analysts think Hut 8's shares could be worth.
The stock's next move may depend on whether Hut 8's current market value is justified by the sales it is already generating and the revenue investors expect those new data center contracts to produce.
If you want to stress test the same sales question you are asking of Hut 8 across other AI infrastructure plays, take a look at 53 AI infrastructure stocks.
Is Hut 8 Getting Expensive on Sales?
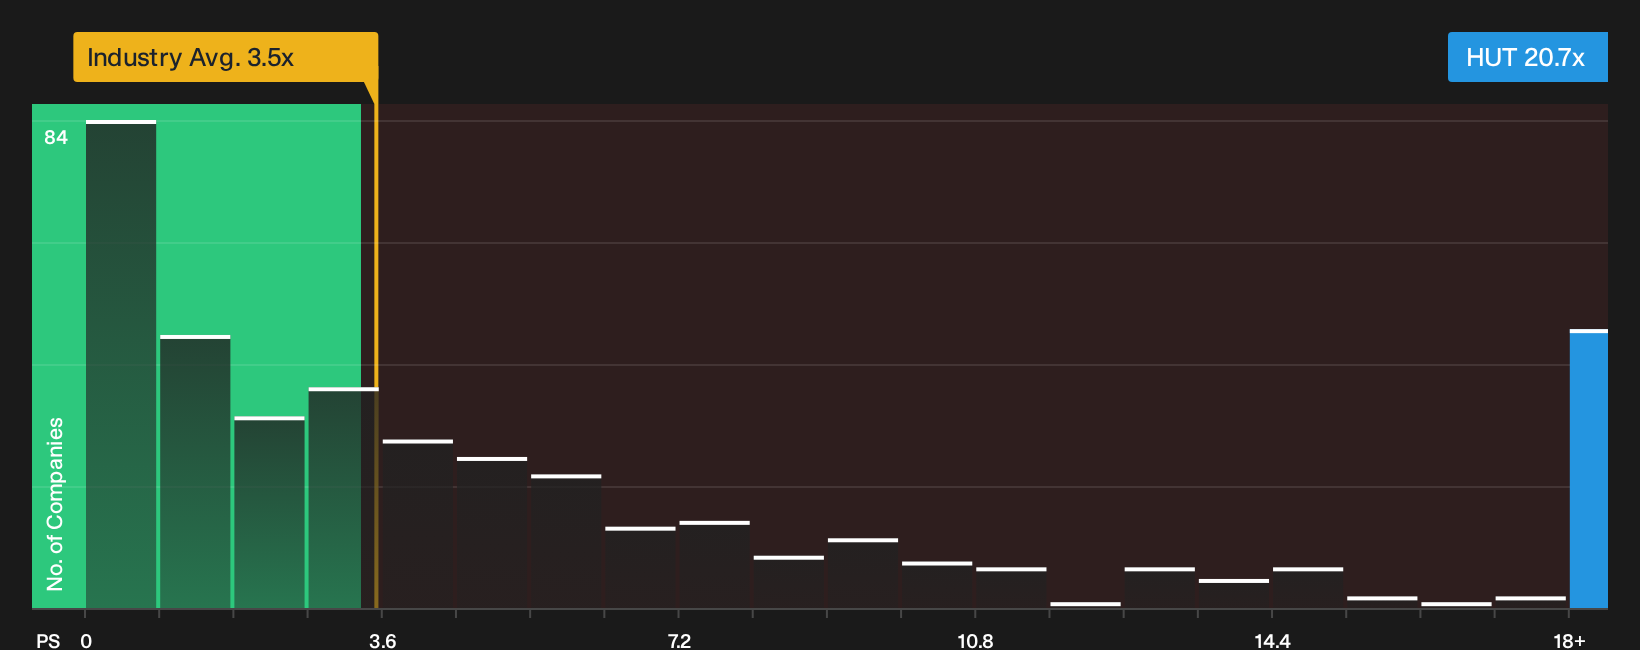
P/S is the cleaner lens for Hut 8 right now because the focus is on contracted revenue and AI data center capacity rather than current profitability. On this metric, the stock trades at about 20.7x sales, compared with a Software sector average of roughly 3.5x and a peer pack closer to 1.6x. That is a steep step up in what the market is paying for each dollar of Hut 8 revenue.
The Fair Ratio model, which blends factors like growth potential, margins, size and risk, points to a lower sales multiple than where Hut 8 changes hands today, so the shares screen as overvalued on this framework. Because the AI data center portfolio is still early and much of the US$26.6b Beacon Point contract value has not yet flowed into reported sales, investors are effectively paying now for revenue that is expected later. Despite the recent Q3 miss and the stock’s pullback after earnings, the current P/S still assumes a higher value per dollar of revenue than sector norms and tailored fair value signals suggest. Explore the numbers behind Hut 8's P/S valuation.
The Hut 8 Narrative: What Would Justify Today's Price?
Hut 8's valuation puzzle sets up the role of Simply Wall St Narratives, which spell out what future growth, margins and earnings would need to look like for the stock to be priced meaningfully higher or lower than it is today. Each one treats fair value as a thesis about the business that can be revisited over time rather than a single static number. These sit on Simply Wall St's Community page for investors who want to track how the story evolves against the actual results.
Community views on Hut 8 split between investors who see contracted AI capacity as underappreciated and others focused on policy and project timing risk.
Bull case: 42% undervalued
"The numbers imply that the current Hut 8 share price assigns limited value to the roughly $26.6b of contracted AI lease revenue and the large, largely nonrecourse project financing stack..."
Discover why this Narrative puts Hut 8 at 42% undervalued.
Bear case: 8% overvalued
"Beacon Point is 1,000 of the 1,330 MW Hut 8 has under construction, the most concentrated Texas position in the group..."
Explore why this Narrative puts Hut 8 at 8% overvalued.
Before acting on Hut 8's valuation, there is one more filter to run
Hut 8's pricing story only tells part of the picture, because Simply Wall St's broader checks have also flagged underlying risks that some investors may want to weigh just as carefully. Take a closer look at 3 warning signs (2 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com