


Why Did Guardian Pharmacy Services (GRDN) Shares Climb Today?
Guardian Pharmacy Services (GRDN) just released third quarter 2026 results, reporting earnings and sales above analyst expectations, net income roughly doubling year over year, and full year guidance raised alongside fresh pharmacy acquisitions and network expansion.
The earnings beat and guidance lift helped Guardian Pharmacy Services shares jump to US$42.39, with a 1-day share price return of 6.32% and a year-to-date share price return of 43.55%. The 1-year total shareholder return of 47.19% indicates strong recent momentum rather than a short-lived spike.
Scan more healthcare momentum stories such as Guardian Pharmacy Services by exploring our hand picked 19 high quality undiscovered gems that have been drawing rising investor attention this year.
Bulls see Guardian Pharmacy Services using raised guidance, expanding locations and higher earnings to support a richer valuation. Bears point to the sharp share price run. Which story do the current valuation markers back up?
Most Popular Narrative: 14% Undervalued
Guardian Pharmacy Services is framed as undervalued in the most followed narrative, with a fair value of $49.50 against the latest close of $42.39. That gap relies on a specific view of how long term care pharmacy demand and margins evolve over the next few years.
Growing senior and high acuity populations in assisted living facilities should support sustained mid to high single digit organic resident growth and increasingly complex drug regimens, expanding revenue per resident and total revenue.
See why 2 investors see Guardian Pharmacy Services as 14% undervalued.
Result: Fair Value of $49.50 (UNDERVALUED)
Still, Guardian Pharmacy Services relies heavily on integrating acquisitions and on reimbursement terms with payers, so any setback on either front could quickly challenge this undervalued story.
Find out about the key risks to this Guardian Pharmacy Services narrative.
Another View: Guardian Pharmacy Services Looks Expensive On Earnings
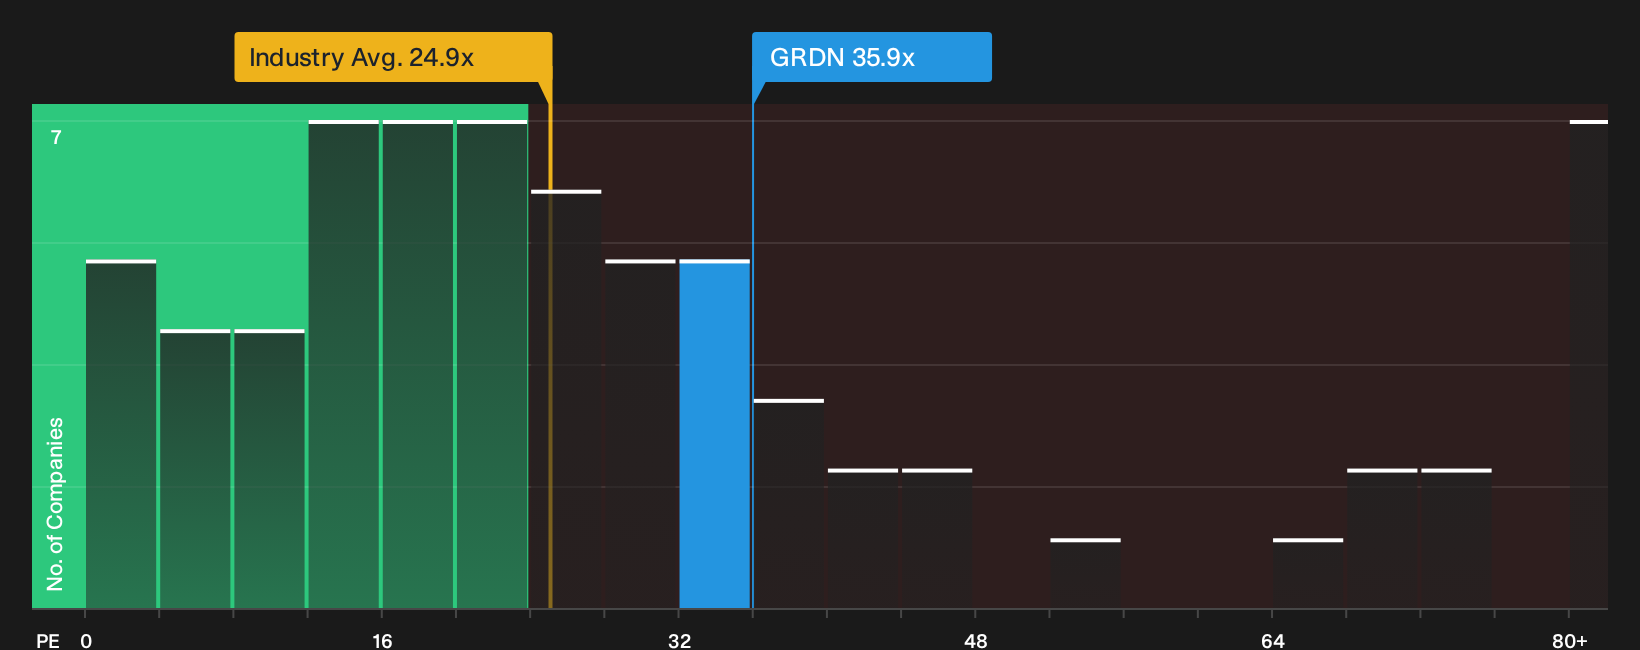
On a cash flow lens, Guardian Pharmacy Services screens as undervalued, yet the earnings multiple tells a different story. The stock trades on a P/E of 35.9x, which is richer than the US Healthcare sector on 24.9x and above a peer average of 34.2x.
The fair ratio for Guardian Pharmacy Services is 24.3x, a level the market could move toward if enthusiasm cools. That gap signals valuation risk if growth or margins underwhelm. Investors need to decide which signal carries more weight right now: the cash flows or the earnings multiple.
For a closer look at how this richer P/E stacks up against sector and peer benchmarks, and what the fair ratio implies for future pricing, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Reading all this, the bullish and bearish cases for Guardian Pharmacy Services might feel finely balanced, so move fast and check the underlying data yourself before opinions harden. To see which specific upside factors our work has highlighted and judge whether they outweigh the risks for your own thesis, review the 3 key rewards
Looking for more Guardian Pharmacy Services style ideas?
If Guardian Pharmacy Services has caught your eye, do not stop here. Broaden your watchlist and let data surface fresh opportunities before the crowd moves.
- Target quality at a discount by scanning companies that screen as mispriced on fundamentals through our 39 high quality undervalued stocks.
- Prioritise resilience by focusing on businesses with robust finances using the list of solid balance sheet and fundamentals (24 results).
- Seek a smoother ride by filtering for historically steadier performers via the 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com