


Murphy Oil (MUR) Stock Could Trade At A Discount On Its 50% Five Year Gain
Murphy Oil has delivered a 50.3% gain over the past 5 years, yet the share price has recently pulled back, which puts fresh focus on what investors are really paying for its earnings today. With the stock closing at US$35.96 and sentiment shaped by both recent news and a longer track record, the key question is how that price lines up with the profits the business is generating.
- The 50.3% return over 5 years puts real weight on whether the current valuation still lines up with Murphy Oil's earnings power or is asking too much of it.
- Recent profit outperformance and new offshore Mauritania contracts may support expectations for future cash generation, but they also raise the bar for what the earnings line needs to deliver over time.
- The analysts covering Murphy Oil have run their own numbers. See what analysts think Murphy Oil's shares could be worth.
For investors, the debate is whether Murphy Oil's current share price is adequately supported by its earnings when judged against the Fair Ratio benchmark.
If you are testing the same earnings question on other opportunities, it can help to compare Murphy Oil with a broader set of 39 high quality undervalued stocks.
Is Murphy Oil a Bargain on Earnings?
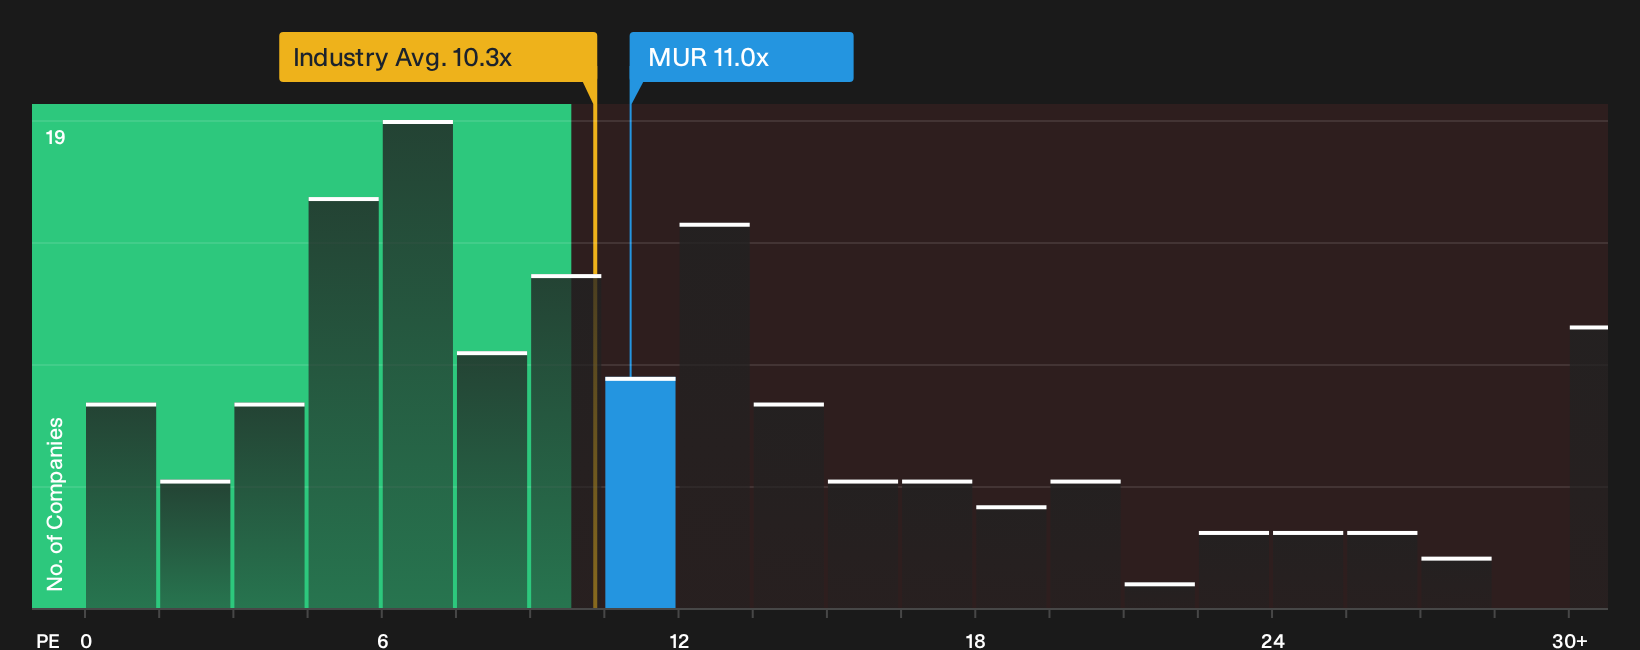
The P/E ratio suits Murphy Oil because earnings are a key driver for investors in established producers. At a current P/E of about 11.0x, the stock trades close to both the Oil and Gas industry average of roughly 10.3x and the peer group on around 10.5x. That keeps the headline valuation in a similar range as comparable businesses on this single metric.
Because the Fair Ratio points to a higher figure than where Murphy Oil trades today, the current earnings multiple screens as undervalued on this tailored yardstick that factors in the firm’s profile and risks. Despite the recent earnings beat lifting interest in the story, the P/E still prices Murphy Oil at a level that suggests the market is not fully extending the premium that this framework implies. As a result, the stock may warrant a closer look on an earnings basis. Explore the numbers behind Murphy Oil's P/E valuation.
The Murphy Oil Narrative: What Would Justify Today's Price?
Murphy Oil Narratives pick up where the P/E puzzle leaves off, by spelling out which expectations for future growth, margins and earnings would need to hold for the stock to be worth materially more or less than today’s price. Each one focuses on the assumptions behind its fair value so you can track those against Murphy Oil’s actual results on Simply Wall St’s Community page as new numbers arrive.
Community views on Murphy Oil are split between investors who see long term projects as underappreciated and others who think the current price already reflects a lot of execution success.
Bull case: 32% undervalued
"The 18 to 24 month appraisal program at Bubale in Côte d'Ivoire, with up to five wells planned after a discovery that encountered 100 feet of net oil pay…"
Discover why this Narrative puts Murphy Oil at 32% undervalued.
Bear case: 6% overvalued
"The uplift of 2026 capex to roughly US$1.55b and indications that 2027 spending will exceed the prior US$1.2b to US$1.3b range increase the chance that any commodity price softness or project setback forces either reduced shareholder returns or lower earnings quality…"
Explore why this Narrative puts Murphy Oil at 6% overvalued.
Murphy Oil's price is only one side of the story
Valuation tells you what the market is paying today, while analyst expectations for Murphy Oil a few years from now offer a different lens on where earnings and cash generation might head next. Explore where analysts expect Murphy Oil to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com