


What Delta Air Lines Bulls Got Right
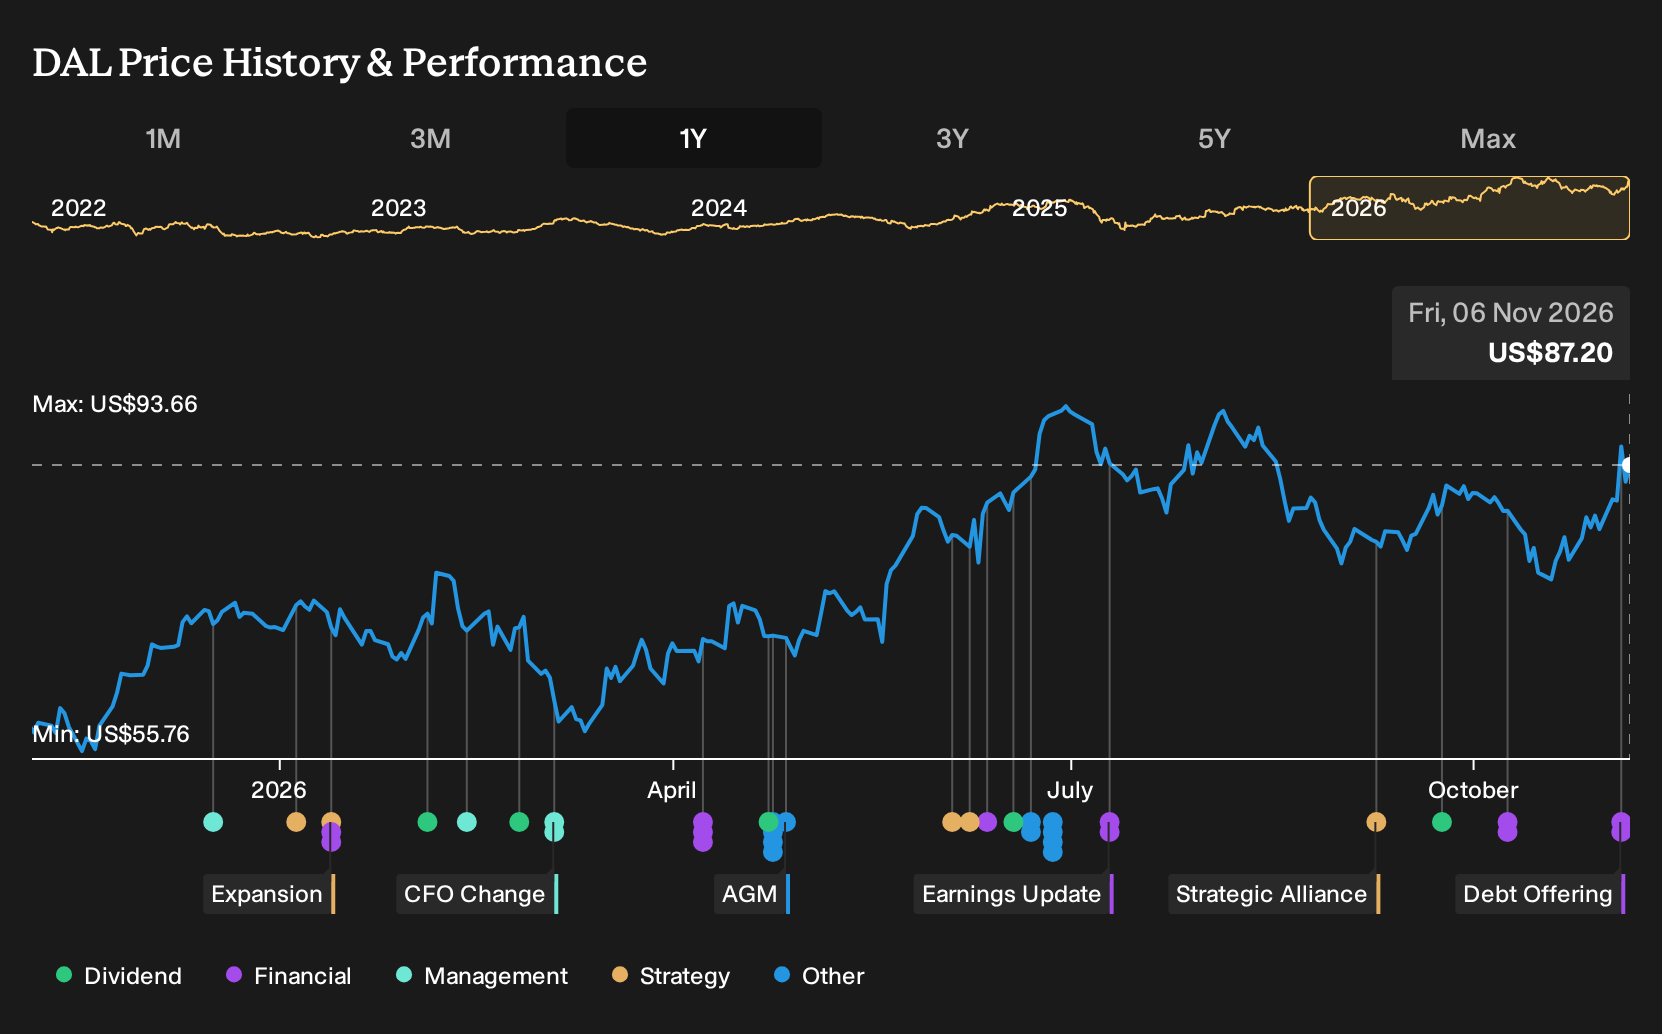
If Delta Air Lines was on your watchlist rather than in your portfolio, the result may feel like a missed call. Holding Delta Air Lines over the past year would have returned 49.7%, including dividends. That kind of move invites a simple question. If analysts were already split between premium-led resilience and margin pressure from weaker domestic cabins and higher non-fuel costs in late 2025, what business assumption about premium travel strength would have helped you spot the potential earlier?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
The easy part of this move is behind Delta Air Lines. Zero in on 39 high quality undervalued stocks for companies trading below our estimates.
The Two Stories Investors Were Weighing On Delta Air Lines
The shares cost US$57.81 at the start of the period, and anyone looking at Delta Air Lines had to choose between two very different but reasonable stories.
On the optimistic side, the bullish narrative put fair value at US$69.66. That view leaned on premium cabins, loyalty revenue and flat capacity growth, with analysts assuming 3.4% annual revenue growth and a 6.8% profit margin supported by cost control and new MRO income from a long-term UPS agreement.
The cautious camp saw a credible bear case with fair value at US$31. That scenario focused on pressure from weaker domestic main cabin demand, higher non-fuel unit costs growing 2.6% over the prior year, and the risk that tariffs on aircraft purchases could push expenses ahead of revenue.
What The Results Changed For The Delta Air Lines Case
Record Q2 and Q3 2026 revenue at Delta Air Lines, helped by premium cabins and loyalty income, lined up with the bullish story that saw premium strength as the swing factor. The challenge came on the bottom line. Net income in Q3 2026 was US$756m versus US$1,417m a year earlier and net margin fell from 8.5% to 3.7%, so the profitability leg of the optimistic case remained unproven. Overall, the evidence cut both ways.
The lesson is simple. When an investment rests on premium strength offsetting cost pressure, it is important to track both revenue mix and net margin in later reports. The test is whether richer cabins and loyalty cash are visible in segment revenue while overall profitability holds up, rather than just the top line alone.
What Delta Air Lines' Price Already Assumes
Delta Air Lines now trades at US$87.2 after a 49.7% gain over the past year, so any new buyer is paying up for the current story.
The selected Narrative’s Fair Value sits below the current price and leans on a tougher reading of fuel, margin ambitions and disclosure quality. A buyer today is effectively assuming mid-teens margins and premium monetisation hold together, so how does that square with a fuel shock used as explanation across the business?
"The framing shift between these two calls is less about what changed and more about who is doing the explaining. Bastian once described fuel as “the most powerful catalyst for change in our industry,” an external force Delta was navigating from a position of strength."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Go Straight To The Source
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 42% below our estimate - convert shorter brownfield tieback timelines into higher margin subsea contracts.
- Company 2 - 30% below our estimate - run higher cost gold mines balancing reserve life with geopolitical and balance sheet risks.
- Company 3 - 40% below our estimate - handle AI driven freight and compliance work for customs agencies prioritizing stricter enforcement.
Those are three of them. See every one of the 24 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com