


Earnings Growth Might Change The Case For Investing In Maire (BIT:MAIRE)
- Maire S.p.A. reported nine month 2026 results, with sales of €5,555.27 million, revenue of €5,636.72 million and net income of €208.93 million, alongside basic and diluted EPS from continuing operations of €0.638, all compared with the same period a year earlier.
- The small step up in net profit and per share earnings suggests Maire converted a larger top line into slightly higher profitability while keeping dilution in check.
- Investors may now assess how Maire's higher nine month net income fits into the broader investment narrative around its energy transition platform.
Scan how Maire's earnings story compares with peers in the energy and infrastructure space by reviewing our curated list of list of solid balance sheet and fundamentals (193 results).
Maire Investment Narrative Recap
Maire appeals to shareholders who believe its large engineering backlog and growing sustainable technology portfolio can support steady project delivery. The latest nine month figures show higher sales, revenue and net income, which keeps that core thesis intact rather than transforming it. The key near term catalyst still sits in how reliably the group converts its €15.6b integrated E&C backlog into cash and earnings.
The biggest operational risk remains execution on large, complex EPC contracts spread across regions such as Central Asia, Sub Saharan Africa and the Middle East. Any cost overruns, delays or disputes on those jobs could offset the benefit of the recent earnings uplift and keep margins tighter than expected in the short run.
The most relevant context for these earnings is the earlier update that Maire had a commercial pipeline above €61b and a record integrated E&C backlog of about €16.3b with completion dates stretching to 2031. The nine month 2026 results start to show how that pipeline converts into reported revenue and net income rather than staying on paper.
For catalysts, the backlog tied to Nextchem technologies of €702.6 million and the added portfolios from Ballestra and ETEK continue to matter. Investors watching Maire stock can use these earnings as a checkpoint on whether higher margin technology revenues are gaining weight against the larger E&C book and whether execution quality is holding up as projects ramp across more geographies.
Maire's narrative projects €8.7b revenue and €367.0 million earnings by 2029. This requires 6.1% yearly revenue growth and an earnings increase of about €95 million from €271.5 million today.
Uncover how Maire's fair value indicates a 31% potential upside to its current price, before a closing gap reshapes Maire's risk reward profile.
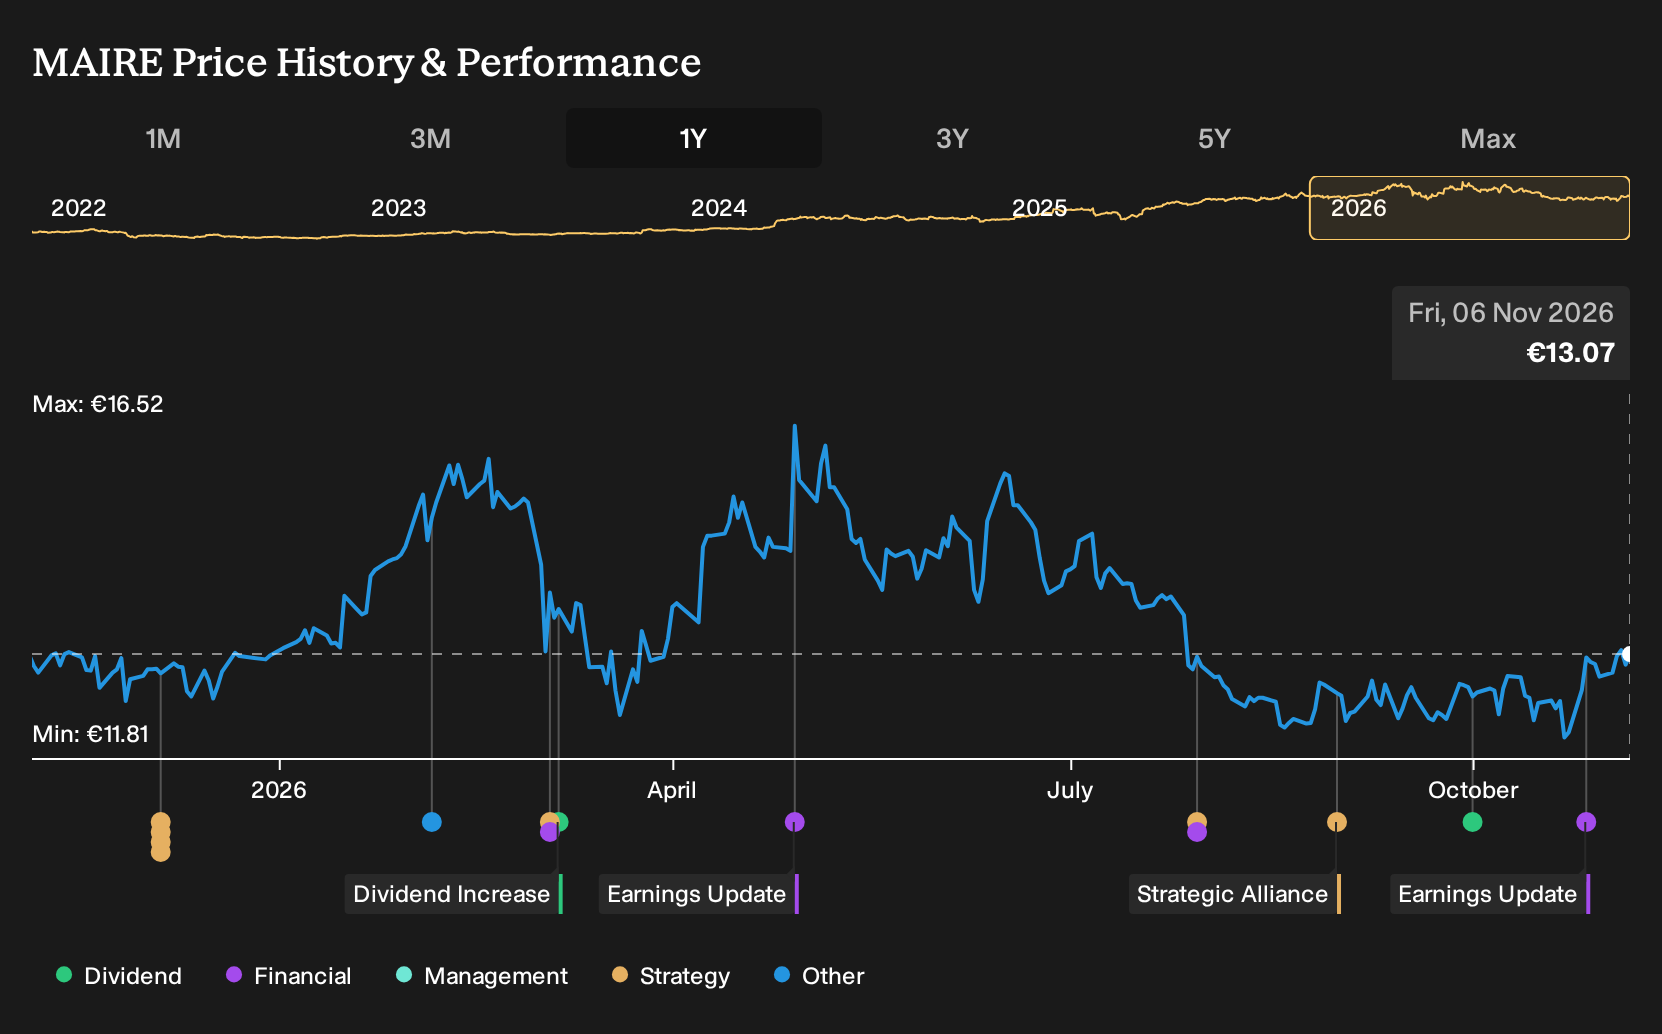
Exploring Other Perspectives
The four fair value estimates from the Simply Wall St Community cluster between €11.14 and €17.10, so retail views on Maire’s worth already span a wide band. Those opinions were set before the latest earnings, while execution risks on large EPC projects and the smaller Nextchem backlog keep future profitability outcomes quite open. Readers should weigh these contrasting viewpoints and explore several alternative angles before forming a stance on Maire.
Explore 3 other Maire fair value estimates, including one that suggests as much as 31% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Maire research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Maire. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Maire's overall financial health at a glance.
Looking For More Ideas Beyond Maire?
If you want to put Maire's story in context, it helps to line it up against other listed businesses with different risk and return profiles. The Simply Wall St Screener lets you scan the market quickly and focus on companies that actually fit your style rather than scrolling tickers at random.
- If capital protection sits high on your list, start with a set of resilient businesses by reviewing our 212 resilient stocks with low risk scores that keep risk scores in check while still offering equity upside.
- For readers hunting for quality at a fair entry point, compare Maire with a 224 high quality undervalued stocks that combine stronger fundamentals with attractive pricing based on our filters.
- Income focused investors can round out a watchlist by screening for 232 dividend fortresses that pair yields above 5% with an emphasis on stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com