


5% Undervalued? Solventum (SOLV) After Its Earnings Beat And Higher Outlook
Solventum (SOLV) just paired an earnings beat with a higher full year outlook after its third quarter report, as the company finished a large ERP cutover and advanced its supply and business separation plans.
Solventum’s recent news has arrived alongside a clear shift in how the market is pricing the story, with the share price at $90.38 after a 1-day share price return of 3.67% and a 7-day share price return of 11.13% following the earnings beat, raised outlook, ERP cutover progress, and updates on tuck in acquisitions. Over a longer stretch, momentum has been building as well, with a year to date share price return of 14.38%, a 90 day share price return of 8.92%, and a 1 year total shareholder return of 26.37% pointing to investors steadily reassessing both execution risk and perceived growth potential as the separation from 3M nears completion and the Acera acquisition outperformance is absorbed into expectations.
Scan how investors are repricing Solventum’s peers following earnings and guidance shifts by sifting through a curated set of 39 high quality undervalued stocks in similar situations.
Bulls point to Solventum’s ERP completion, raised EPS guidance and Acera momentum. Bears focus on declining reported revenue and a recent quarterly loss. Which side do the current valuation signals lean toward?
Most Popular Narrative: 5% Undervalued
On the most followed narrative, Solventum screens slightly undervalued, with a fair value of $94.69 against the latest close at $90.38. The difference reflects questions about how durable margins and growth will be after the separation work finishes.
Programmatic savings, the Transform for the Future initiatives, separation cost wind down, and a tariff refund that management expects to neutralize tariff headwinds in 2026 are collectively moving Solventum’s operating margins close to its long range target earlier than planned. This can translate into higher net margins and earnings power as these benefits are realized.
See why 36 investors see Solventum as 5% undervalued.
Result: Fair Value of $94.69 (UNDERVALUED)
Still, the Solventum story can break if the high margin Health Information Systems spin leaves MedSurg and Dental margins weaker, or if organic growth stays muted.
Find out about the key risks to this Solventum narrative.
Another View: Solventum Through the P/E Lens
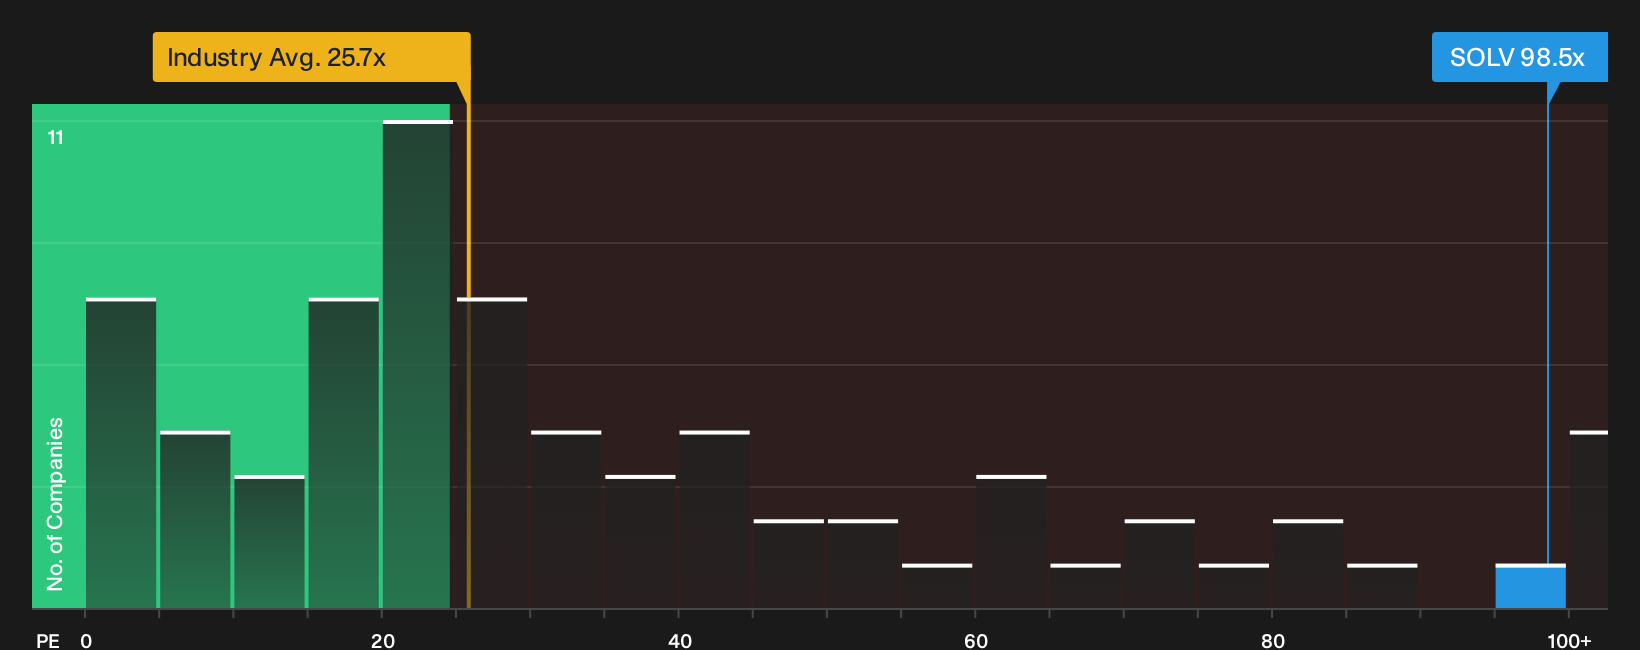
The DCF work suggests Solventum looks cheap relative to estimated future cash flows, yet the simple P/E picture tells a different story. At roughly 98.5x earnings, the stock trades at more than 3x the Medical Equipment industry on 25.3x and well above a fair ratio of 39.9x. This points to meaningful valuation risk if expectations reset.
See what the numbers say about this price in more detail in our valuation breakdown, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals in the Solventum story right now. Act while the information is fresh, review the underlying data yourself, then weigh 2 key rewards and 3 important warning signs.
Looking for more Solventum sized ideas?
You have fresh context from Solventum. Do not stop here. Put that perspective to work by lining up a watchlist of your next potential candidates today.
- Target potential upside by scanning a focused set of 19 high quality undiscovered gems that many investors are not watching yet.
- Prioritize quality first and hunt for companies with sturdy finances using the list of solid balance sheet and fundamentals (24 results) to anchor your research.
- Stack your income options and compare payouts across a curated pool of 8 dividend fortresses built for yield focused portfolios.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com