


PNC Financial Services Group (PNC) Could Be 15% Undervalued As 370 Branch Expansion Takes Shape
PNC Financial Services Group (PNC) is drawing fresh attention after outlining plans to add more than 370 branches by 2031. The company is concentrating new locations in South Carolina, Georgia, Texas, Florida and North Carolina.
Against that expansion plan, PNC Financial Services Group’s recent share price tells a mixed story. The stock is around US$225.38, with the share price up over the year to date but down over the past quarter, while the 1 year and 3 year total shareholder returns of 26.38% and 108.27% indicate stronger longer term momentum.
Compare PNC Financial Services Group’s branch expansion and digital push with other large banks by scanning our hand picked list of list of solid balance sheet and fundamentals (24 results)
PNC Financial Services Group trades at a discount to both analyst targets and an estimated intrinsic value, even after its branch and digital expansion headlines. Is that a sensible safety margin, or is the market sending a warning signal on risk?
Most Popular Narrative: 14.5% Undervalued
On the most followed view of PNC Financial Services Group, a fair value of $263.71 sits meaningfully above the recent $225.38 share price. This puts the bank’s heavy spending on branches and technology under a valuation spotlight.
Record technology investment of about US$3.5b a year, with tech spend planned to grow 10% and roughly one fifth of the increase tied to AI projects, is intended to keep expenses controlled relative to revenue and underpin operating leverage and profit growth.
See why 50 investors see PNC Financial Services Group as 15% undervalued.
Result: Fair Value of $263.71 (UNDERVALUED)
Still, the PNC Financial Services Group story depends heavily on fee based businesses and credit conditions remaining supportive. Weaker client activity or a deterioration in loan quality could quickly challenge this undervalued narrative.
Find out about the key risks to this PNC Financial Services Group narrative.
Another View: PNC Financial Services Group On Earnings Multiples
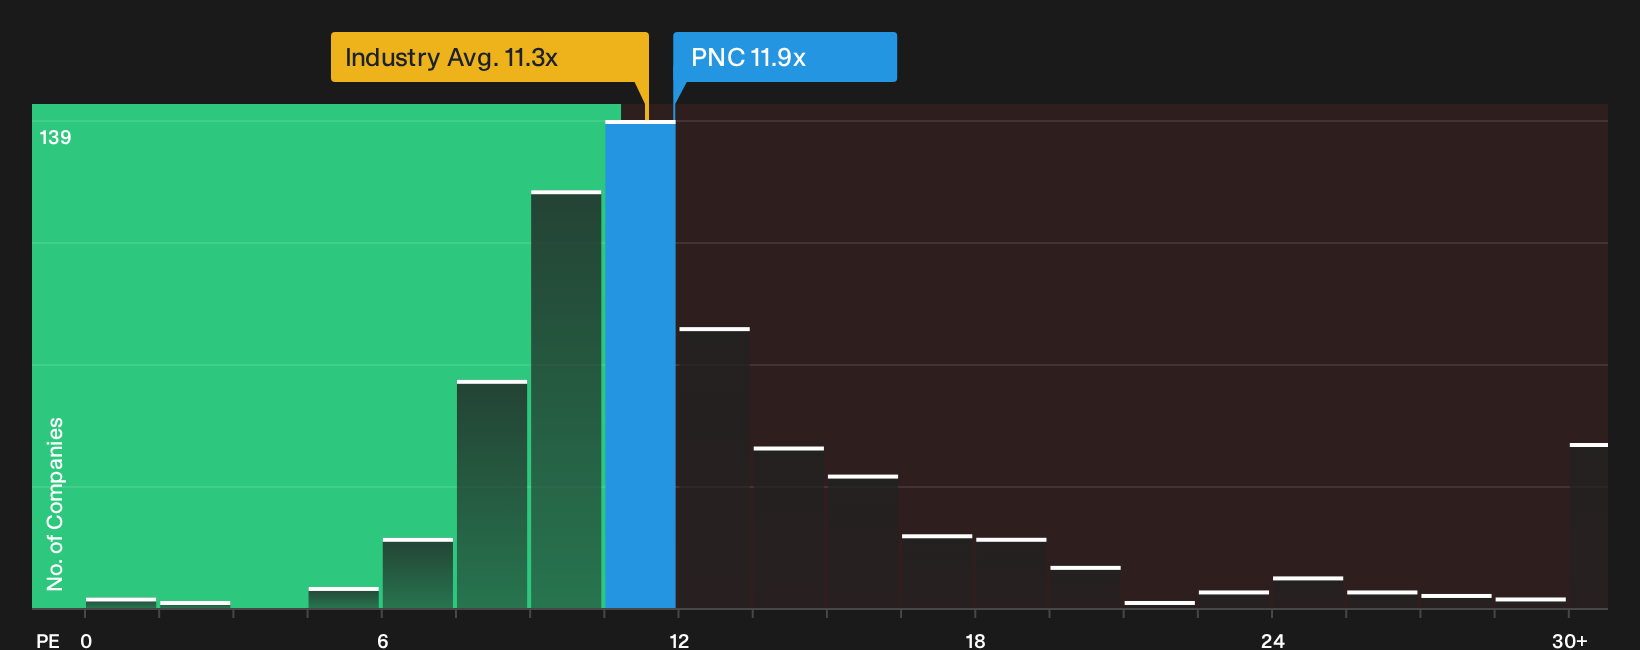
The first take frames PNC Financial Services Group as undervalued on future cash flows and analyst targets. Step back to a simple P/E check and the picture softens. The stock trades at 11.9x earnings, slightly above the US Banks industry at 11.3x, yet below peers at 14.6x and a fair ratio of 13.6x. That mix of mild premium to the sector and discount to peers raises a practical question. Is the real risk that expectations are already full for a large regional bank, or that investors are underpricing its branch and technology push?
For a closer look at how this earnings based view compares with a full intrinsic value estimate, take a look at the SWS valuation breakdown via See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
There are mixed messages on PNC Financial Services Group so far. If the story feels unfinished, move quickly and test the data yourself against the 4 key rewards.
Looking for more investment ideas beyond PNC Financial Services Group?
You have seen how one bank’s story can hinge on pricing, risk and balance sheet strength. Do not stop here when there are more opportunities one screen away.
- Target resilient compounding potential by scanning a curated 29 resilient stocks with low risk scores that aims to limit unwelcome surprises when markets turn choppy.
- Hunt for pricing gaps by reviewing the 39 high quality undervalued stocks, built to surface companies where quality and current market expectations appear out of sync.
- Lock in income ideas by searching the 8 dividend fortresses that focuses on higher yielding payers with the numbers to potentially support ongoing distributions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com