


What Bears Saw Before Lands' End Slid
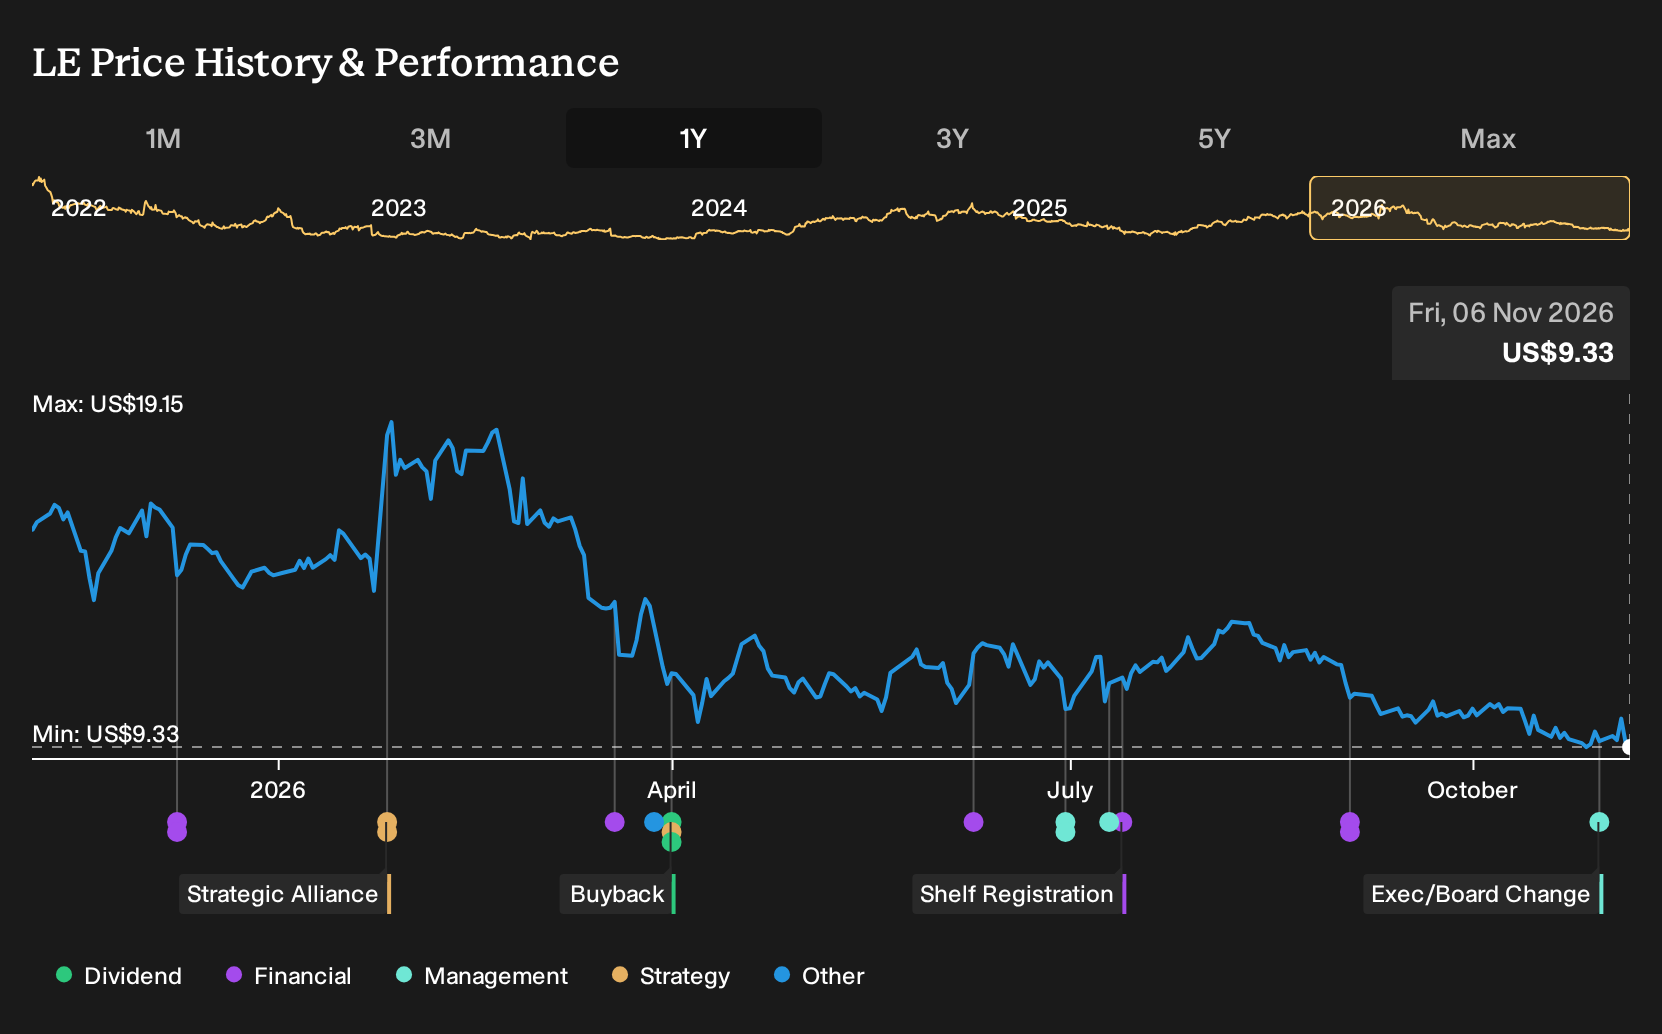
Lands' End just delivered a curious mix of better quarterly news and painful long term outcomes for holders. The latest filing showed revenue of US$302.038 million and a move from a net loss to a profit, yet the share price told a very different story. Holding Lands' End over the past year would have meant a 42.2% loss, including dividends. If you had been weighing a purchase a year ago, what signals were already on the table that could have hinted at this gap between business progress and shareholder outcome?
The easy part of this move is behind Lands' End. Zero in on 39 high quality undervalued stocks for companies trading below our estimates.
The Two Lands' End Stories Investors Had To Weigh
The shares cost US$15.9 at the start of the period, and anyone looking at Lands' End then had to choose between two very different stories for the next few years.
The bullish narrative pointed to a Fair Value of US$20, a price implied by assumptions that revenue could rise 3.0% a year and profit margins might reach 4.3% as licensing, digital initiatives, and international expansion gained traction.
The bearish view saw Fair Value closer to US$15, assuming revenue growth of 2.6%, margins of 4.0%, and ongoing pressure from digital competitors, tariffs, and an aging brand image.
What The Results Changed For Lands' End
The clearest new fact was the swing in Lands' End quarterly performance. Revenue was US$302.038 million and the firm moved from a loss of US$3.667 million in Q2 2026 to a profit of US$3.451 million in Q2 2027. Net margin shifted from a decline of 1.2% to a positive 1.1%. That supported the optimistic case on profitability, but only over a single quarter.
The useful takeaway is how narrow the hinge was. Both stories rested on profit margin improvement. For any other retailer, focus first on whether reported margins are actually tracking the scenario you are paying for. Then treat revenue and P/E expectations as secondary tests.
What You Would Be Paying For In Lands' End Today
Lands' End trades at US$9.33 today, after a 42.2% loss over the past year. The selected Narrative sees Fair Value above that level and roots the argument in balance sheet repair plus monetisation of the brand portfolio.
For that higher figure to be reached, a buyer today would need confidence that the leaner capital structure supports sustained profitability and cash generation.
"By monetizing its IP, Lands’ End significantly reduced its mountain of debt at the same time that rising interest rates were pressuring many competitors. Today, Lands’ End runs its daily operations and global e-commerce business while carrying a much less leveraged balance sheet."
One Narrative disagrees with today's price. → See where this Narrative says Lands' End should trade
Looking Past Lands' End
Lands' End still depends on selling physical goods. You feel that directly whenever you review its quarterly results.
Your wardrobe might start there, but your shopping journey rarely ends there. Another operator increasingly shapes how products are discovered, compared, and reordered.
This other business invests heavily in cloud tools, advertising platforms, and automated retail systems. Its attention stays on the rails that support online commerce.
As that infrastructure deepens, the balance of power can shift further. Brands like Lands' End keep working to stand out on rails they do not control.
One Narrative has already put a figure on it. → Uncover the company trading 42% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com