


How Raised Profit Guidance At Bittium Oyj (HLSE:BITTI) Has Changed Its Investment Story
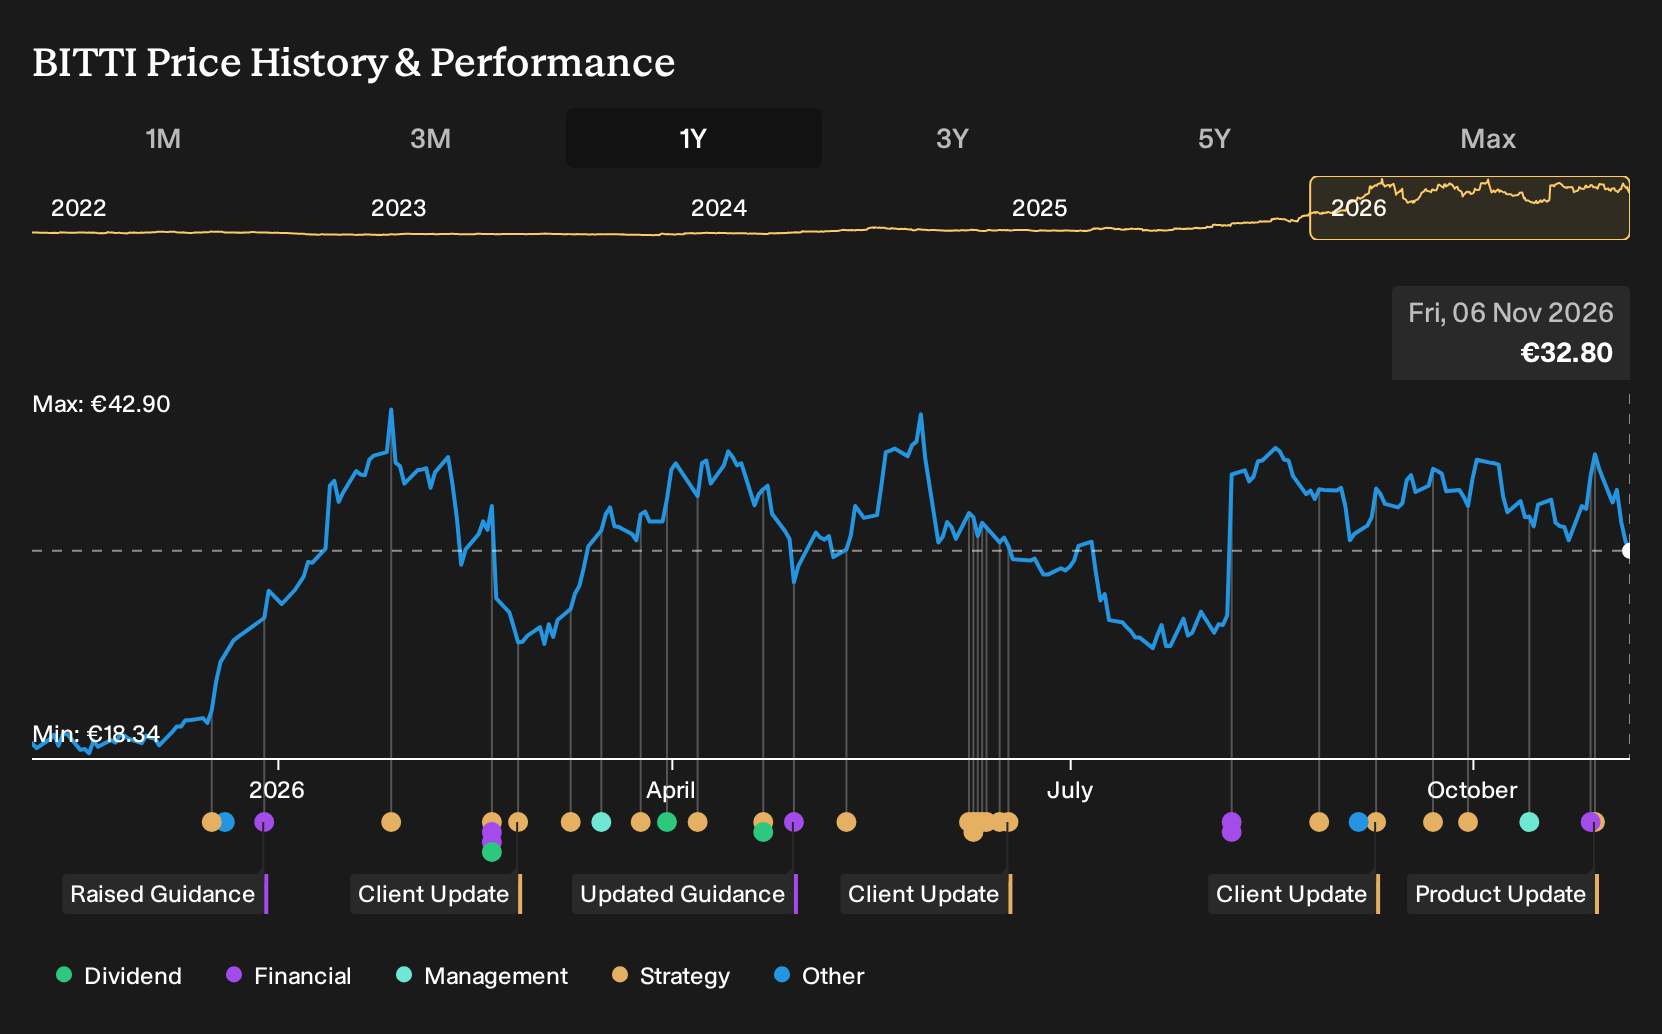
- Bittium Oyj has raised its 2026 operating profit guidance while keeping its net sales outlook range unchanged and recently showed Unikie’s intelligent drone technology running over its tactical communications network at NATO’s Innovation Range event in Oulu.
- The combination of higher profit expectations and a live trial of autonomous drones over Bittium’s Tough SDR Unmanned radios brings together earnings outlook and product capability in the defence communications arena.
- We will now examine how Bittium Oyj’s upgraded 2026 earnings guidance could influence the existing investment narrative for the business.
Scan other defence and autonomous systems players riding similar contract momentum with the curated list of 89 robotics and automation stocks.
Bittium Oyj Investment Narrative Recap
Bittium Oyj appeals to investors who believe the defence focused product portfolio and order book can support higher profitability, while Medical and Engineering Services contribute steadily. The raised 2026 operating profit guidance points to management aiming for stronger earnings from the same net sales range. This keeps execution in Defence & Security as the main short term catalyst.
The biggest operational risk still sits in Engineering Services, where weak demand and negative margins have already weighed on the group. If that segment remains under pressure or defence order timing shifts, the upgraded profit range could become harder to reach, even with current contract visibility and cost work already done.
The refreshed 2026 outlook, with net sales still guided at €140 million to €155 million and operating profit now guided at €29 million to €36 million, is the most relevant recent announcement. For a holder of Bittium Oyj, that update ties the defence contract momentum more clearly to near term earnings potential instead of just top line volume.
That said, the guidance also highlights sensitivity to the timing of individual orders and deliveries, and to depreciations linked to license income. For you as an investor, the key watchpoints are how smoothly those large defence framework agreements convert to revenue through 2026 and whether Engineering Services can stop dragging on the consolidated margin story.
What The Revenue And Earnings Assumptions Mean For Bittium Oyj
Bittium Oyj's narrative projects €247.9 million revenue and €45.8 million earnings by 2029. This implies analysts are incorporating 22.5% yearly revenue growth and an earnings increase of about €18.5 million from €27.3 million today.
Uncover why Bittium Oyj's fair value indicates a 23% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts already expected Bittium Oyj to reach €274.9 million in revenue and €58.7 million in earnings by 2029, largely on the back of defense contracts and licensing. The NATO drone trial adds a fresh angle to that product heavy story. You can now compare these older forecasts with your own view on how this new unmanned systems angle might reshape expectations.
Explore 3 other Bittium Oyj fair value estimates, including one that suggests as much as 40% potential upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis and instincts.
- A great starting point for your Bittium Oyj research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Bittium Oyj. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bittium Oyj's overall financial health at a glance.
Looking For More Investment Ideas Beyond Bittium Oyj?
If the Bittium Oyj story has sharpened your thinking but you want a wider field to compare against, the Simply Wall St Screener can help you line up other opportunities side by side and pressure test your thesis.
- If capital preservation ranks high for you, scan a set of 212 resilient stocks with low risk scores and see which businesses better match your comfort with volatility.
- For investors hunting for quality at a reasonable tag, review a curated 225 high quality undervalued stocks and weigh their fundamentals against Bittium Oyj.
- Income focused readers can size up dependable cash return potential by filtering through a targeted 232 dividend fortresses and comparing yield, payout ratios, and balance sheet strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com