


Noble (NE) Could Be 14% Below Fair Value As Guidance Tightens
Noble (NE) is back in focus after a mixed third quarter where revenue and earnings moved into loss territory, yet management tightened full year sales guidance and reaffirmed a sizeable cash dividend.
Noble’s share price has been choppy around the third quarter update, with a 7 day share price return of down 16.59% and a 1 day move of up 2.48%. However, the year to date share price return of 40.93% and 1 year total shareholder return of 46.58% point to momentum that has cooled recently rather than reversed outright.
Scan beyond Noble and explore offshore drilling peers with similar contract strength and dividend focus in our hand picked 41 high quality undervalued stocks list.
Bulls view Noble as a solid backlog and dividend story that just hit an earnings air pocket. Bears focus on the fresh losses and the recent share pullback. Which side does the current valuation appear to favor next?
Most Popular Narrative: 12% Undervalued
The most followed Noble valuation narrative puts fair value at $46.50, compared with the recent $40.87 close. This points to a moderate discount that leans heavily on long term contract visibility and earnings power rather than near term headlines.
The main thing that has to go right is Noble converting its multi-year, roughly $7.5b backlog and projected fleet reactivations into the EBITDA and free cash flow levels management has outlined for the second half of 2027, despite current operational issues, guidance cuts, and the Brazil-related investigation.
See why 71 investors see Noble as 12% undervalued.
Result: Fair Value of $46.50 (UNDERVALUED)
Still, that story can crack if operational setbacks in Brazil drag on, or if the fraud investigation around prior disclosures leads to heavier costs and weaker confidence.
Find out about the key risks to this Noble narrative.
Another View: Noble Looks Expensive On Earnings
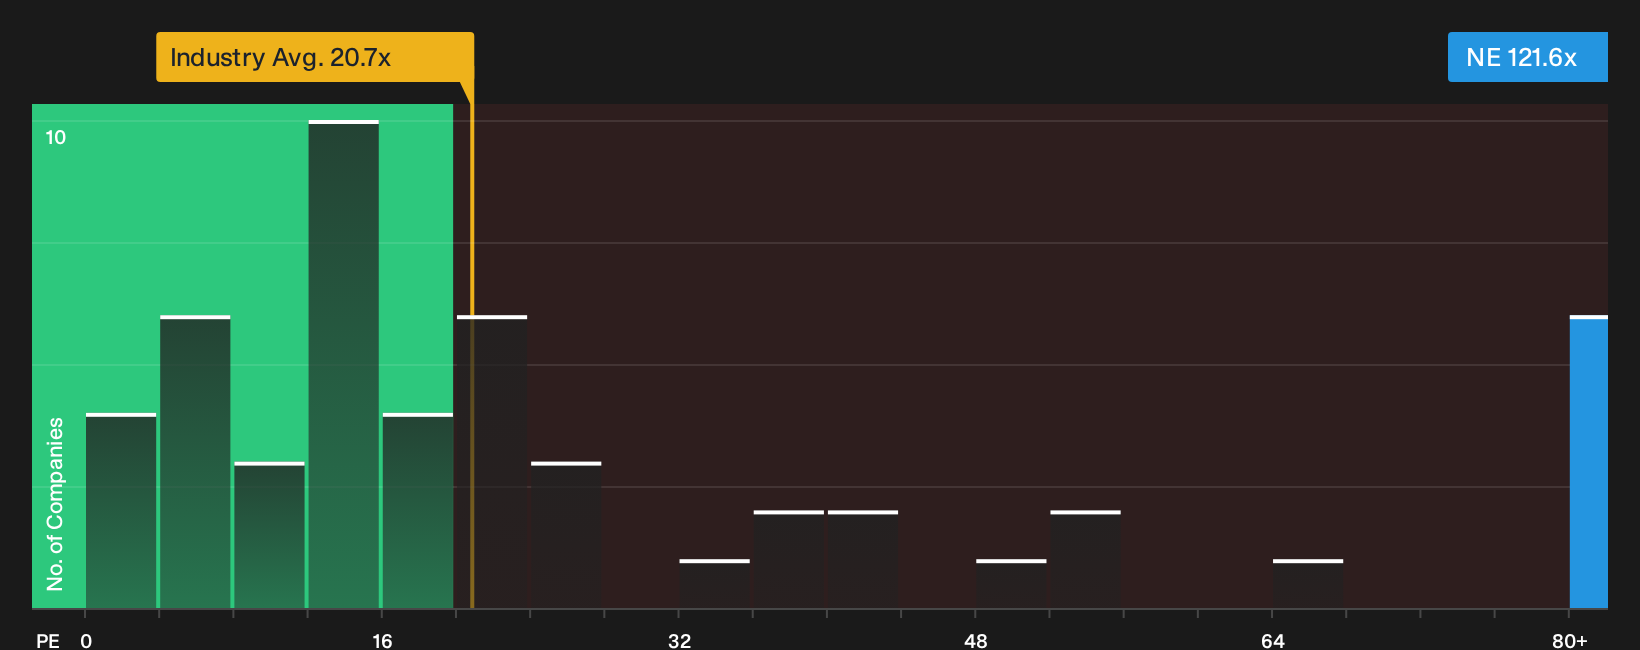
The first story around Noble leans on cash flow and backlog, yet the P/E picture tells something different. At 121.6x earnings versus 20.7x for the wider US Energy Services group and 5.3x for peers, the stock carries a rich earnings tag. Even the fair ratio of 97.9x implies a high bar that could leave little room for error. Which signal do you trust more when the narratives clash?
For a closer look at how that earnings multiple stacks up and what could have to change for it to compress or grow into expectations, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Noble’s outlook can be confusing, so move quickly to review the full dataset and pressure test both sides of the story using 2 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond Noble?
If Noble has your attention, do not stop here. Broader opportunities are only a few smart filters away when you put the Simply Wall St screener to work.
- Target resilient balance sheets by scanning our list of solid balance sheet and fundamentals (24 results) that highlights businesses combining financial strength with fundamental support.
- Spot mispriced potential by reviewing the 19 high quality undiscovered gems that surfaces under-the-radar companies with strong underlying metrics.
- Prioritise sleep-at-night holdings through the 30 resilient stocks with low risk scores that focuses on resilient stocks with lower measured risk.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com