


Molson Coors (TAP) Stock Looks Cheap After Its 19% Slide
Molson Coors Beverage shares have climbed in the short term even as the longer track record has been far less rewarding, which puts fresh attention on whether the current price around US$42 is properly supported by its sales base. With investors reacting to shifting expectations for the business, the key issue is how much sales power the market is really paying for today.
- The stock has declined 19.1% over the past three years, which raises the question of whether the share price now lines up cleanly with the pace and quality of Molson Coors Beverage's sales.
- The company recently lowered its medium term sales and earnings ambitions, which can influence how investors value its ability to convert each dollar of revenue into sustainable profit and cash generation.
- The analysts covering Molson Coors Beverage have run their own numbers. See what analysts think Molson Coors Beverage's shares could be worth.
The issue now is whether Molson Coors Beverage's current share price is appropriately linked to the level and trajectory of its sales.
If this reset in expectations has you reassessing Molson Coors Beverage, it may be useful to take a broader view and compare it with other companies using a focused screen of 42 high quality undervalued stocks.
Does Molson Coors Beverage Look Undervalued on Sales?
P/S works well for Molson Coors Beverage because the business is judged heavily on how much revenue it can generate from its brand portfolio rather than on short term earnings swings.
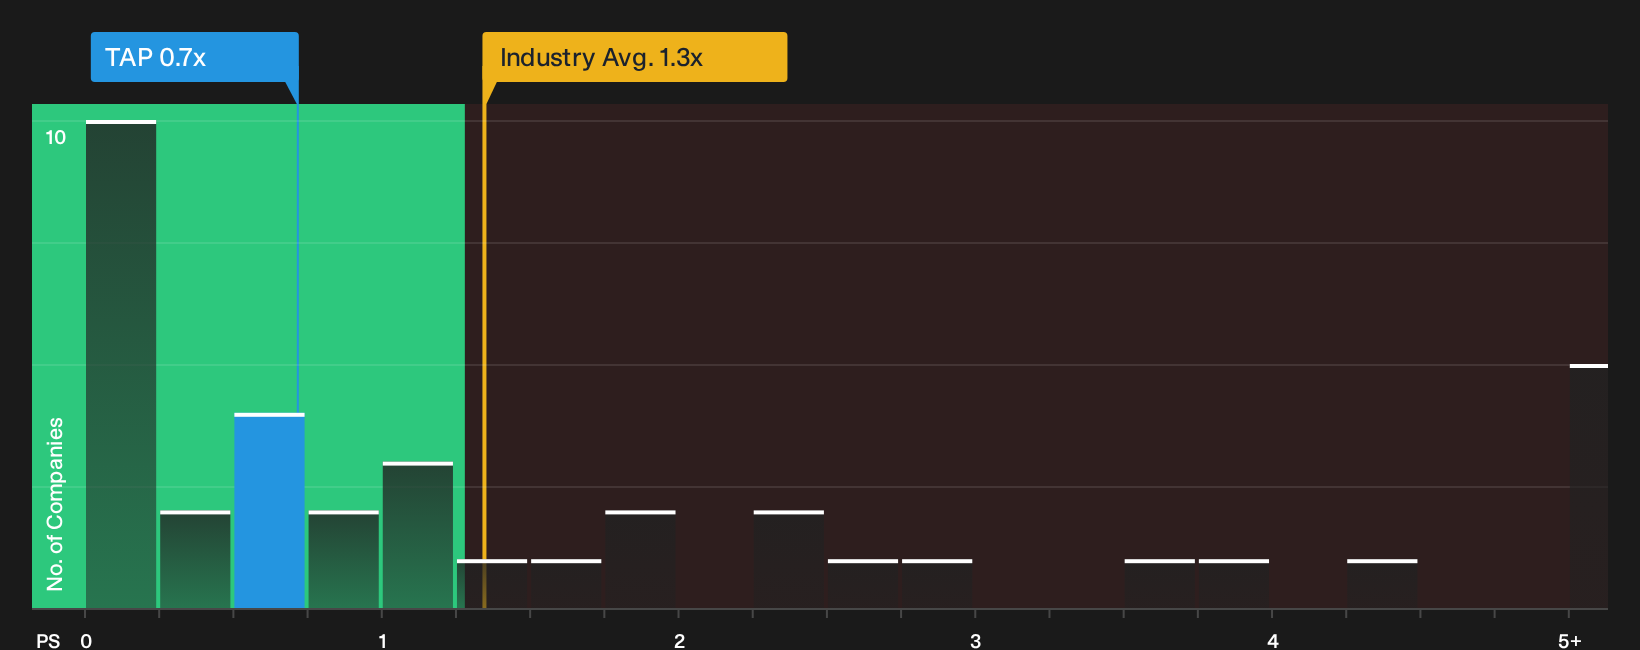
On this lens, the stock trades on a P/S of about 0.7x, compared with a Beverage industry average of roughly 1.3x and a peer group around 2.0x. That sits below the multiple implied by a more tailored fair value framework, which adjusts for Molson Coors Beverage's margins, size and risk profile rather than relying only on simple sector medians. Because management has recently trimmed its 2026 sales and earnings targets, the low P/S suggests the market is already pricing in a cautious view of that softer outlook rather than paying a premium for recovery. For investors, the key question is whether the current discount to those benchmarks fairly reflects the challenges described in the updated guidance or overshoots them. Explore the numbers behind Molson Coors Beverage's P/S valuation.
The Molson Coors Beverage Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Molson Coors Beverage pick up where the P/S puzzle leaves off by spelling out which combinations of future sales growth, profitability and earnings power would need to hold for the shares to sit meaningfully above or below today's price. Each narrative sets out the assumptions behind its fair value view so you can compare those inputs with Molson Coors Beverage's reported results over time on the Community page.
Molson Coors Beverage splits opinions, with some investors seeing more upside in the reset valuation while others focus on pressure in core beer and costs.
Bull case: roughly fairly valued
"Ongoing balance sheet improvement, with net debt to EBITDA at 2.53x, alongside a US$2.35b remaining share repurchase authorisation, gives Molson Coors Beverage capacity to keep returning cash while funding growth investments..."
Discover why this Narrative puts Molson Coors Beverage at roughly fairly valued.
Bear case: 28% overvalued
"Although Molson Coors is pushing Horizon 2030 moves like Monaco, Topo Chico Hard and Fever-Tree to reshape the portfolio toward beyond beer and premium offerings, the recent 3.6% constant currency decline in net sales revenue and 27.8% fall in underlying pretax income show that these newer brands have not yet offset pressure in core beer..."
Explore why this Narrative puts Molson Coors Beverage at 28% overvalued.
Molson Coors Beverage’s valuation still leaves one powerful piece of the puzzle unanswered
The next thing to check is who is actually steering Molson Coors Beverage and how their pay packets line up with the outcomes you care about as a shareholder. See who runs Molson Coors Beverage and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com