


Prediction: November Will Be a Huge Month for Broadcom
Key Points
Management expects huge growth from its AI semiconductor business over the next few years.
The market hasn't priced in any of this growth yet.
Broadcom (NASDAQ: AVGO) hasn't been the best stock to own lately. In June, it hit an all-time high, but it has basically gone straight down from there. It's now down by about 38% from its all-time high, but all that could reverse in November. While Broadcom doesn't have any big events of its own coming this month, there are some others that could drive it higher, like the Anthropic IPO.
Broadcom is a major computing unit supplier to Anthropic, as Anthropic has chosen to deploy a large quantity of Tensor Processing Units (TPUs) that were developed by Broadcom and Alphabet (NASDAQ: GOOG) (NASDAQ: GOOGL). This could drive heightened awareness around Broadcom's stock, but the reality is that it's a viable investment in its own right and shouldn't need the hype of a new IPO to boost its stock.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Broadcom is a great buy in November, and it's easy to see why if you listen to management.
Image source: The Motley Fool.
Broadcom's client list is growing
Broadcom's custom AI chips fill a niche that graphics processing units (GPUs) cannot. GPUs are the industry standard in AI computing because they can be programmed to handle nearly any type of parallel-processing workload. But that type of flexibility costs money.
When a computing unit is designed around a narrow workload, it can be optimized to provide superior performance in that application.
This isn't a new concept. These types of chips, known as application-specific integrated circuits (ASICs), have been around for a while. However, the concept has now made its way to the AI world, and Broadcom has been the primary chip design company to usher it in.
Broadcom's client list is growing. Meta Platforms (NASDAQ: META) now has a custom AI chip in the works, and so does AI lab OpenAI. However, Alphabet has also started to sell more of its TPUs to external customers (rather than solely installing them in its own data centers), and those sales benefit Broadcom as well.
These are all major growth opportunities for Broadcom, and could lead to massive stock returns if management's forecasts pan out.
During Broadcom's latest conference call, CEO Hock Tan discussed the long-term outlook. He noted that its AI semiconductor revenue is expected to rise to $58 billion in 2026, then double to $115 billion in 2027. The company then predicts another doubling to $230 billion in 2028. That's an incredible growth trajectory. To wrap up this projection, Tan noted that Broadcom has secured the supply chain necessary to produce enough computing units to deliver that level of growth.
That should be music to shareholders' ears, as it shows that Broadcom is on top of its game and well positioned for major growth over the next few years. However, the market hasn't taken much heed. None of this forecast growth is currently priced into Broadcom's stock.
Broadcom's stock is priced cheaply
At first glance, you might not think a stock trading at 38 times trailing earnings is cheap, which is fair. However, the trailing P/E ratio doesn't consider future growth at all. Valuing Broadcom stock in relation to the earnings it's expected to have in 2027, it trades at about 10 times earnings.
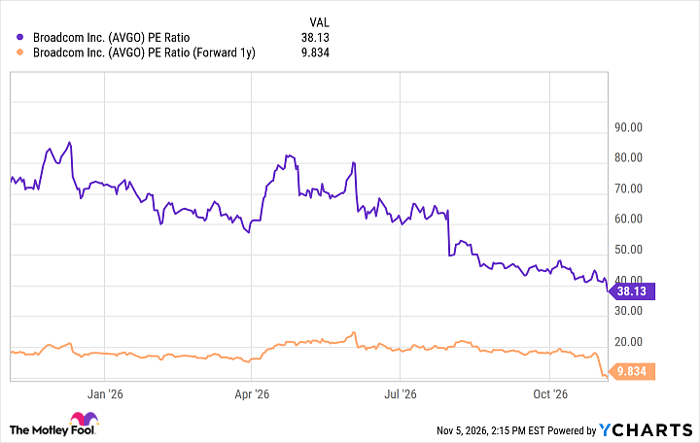
AVGO P/E Ratio data by YCharts. P/E = price-to-earnings.
That's a very attractive price tag, and if a fair value for Broadcom's stock is about 30 times trailing earnings, that suggests that if the company delivers on its guidance, the stock could easily more than double by the end of 2027. That's a pretty attractive investment proposition, and that doesn't even factor in that Broadcom's AI semiconductor business is expected to double again in 2028.
All this points to Broadcom being an excellent AI stock to own for the next few years. With the stock down around 38% from its all-time high, now is the perfect time to scoop up shares. The market may realize what a great value it is, and buy in November to start prepping for what could be an incredible 2027 for the stock.
Keithen Drury has positions in Alphabet, Broadcom, and Meta Platforms. The Motley Fool has positions in and recommends Alphabet, Broadcom, and Meta Platforms. The Motley Fool has a disclosure policy.