


MasterBrand (MBC) Names Interim CFO As Investors Weigh Its Cheap Looking Valuation
MasterBrand (MBC) has just reshuffled its finance bench, with long time accounting leader Mark A. Young stepping in as Interim CFO after Andrea Simon left the role and moved into an advisory position.
Recent trading tells a mixed story. MasterBrand’s 1-day share price return of 9.0% and 7-day gain of 8.68% suggest short term momentum building off the CFO news. In contrast, the year to date share price return has fallen 33.42% and the 1-year total shareholder return is down 30.53%, pointing to a tougher longer term experience for holders.
Compare MasterBrand's CFO shakeup and recent share price swings with other manufacturers on solid financial footing by scanning the list of solid balance sheet and fundamentals (24 results) for potential alternatives in the same broader space.
After a sharp short term rebound and a much tougher 1 year stretch, MasterBrand now sits in awkward middle ground. Does the current price still offer enough upside potential to justify the cabinet of risks?
Preferred Price-to-Sales Multiple of 0.6x: Is it justified?
Valuation on MasterBrand today is being framed heavily by its revenue line, because the business is currently loss making and the P/E lens does not apply. Against that backdrop, a P/S ratio of 0.6x at a last close of $7.51 is doing a lot of the storytelling for this stock.
The P/S metric compares the market value of the equity to the sales the company generates. For a cabinet maker like MasterBrand, where earnings are negative and interest coverage is weak, investors often fall back on revenue based markers to judge how the market is pricing each dollar of turnover.
On that score, the numbers are clear. MasterBrand trades on a P/S of 0.6x compared with 0.9x for its peer group and 1.9x for the broader US Building industry. This represents a steep discount to how similar businesses are being valued. The estimated fair P/S ratio for the company is 2.4x, which is far above the current multiple and indicates a level that the market could move towards if sentiment and fundamentals align.
Explore the SWS fair ratio for MasterBrand.
Result: Price-to-Sales of 0.6x (UNDERVALUED)
Still, MasterBrand faces clear pressure points, including recent multi quarter share price declines and ongoing losses that could limit flexibility if trading conditions tighten.
Find out about the key risks to this MasterBrand narrative.
Another View: SWS DCF Paints A Very Different Picture
The P/S math suggests MasterBrand looks cheap, but the SWS DCF model sends the opposite signal. At a share price of $7.51, the stock trades well above an estimated future cash flow value of $1.43, which implies the shares look expensive if those cash flow assumptions hold up.
That clash between revenue based pricing and future cash flow estimates raises a simple question for any investor reviewing MasterBrand: which story feels more realistic for the next chapter of this business, sales momentum or cash generation?
Look into how the SWS DCF model arrives at its fair value.
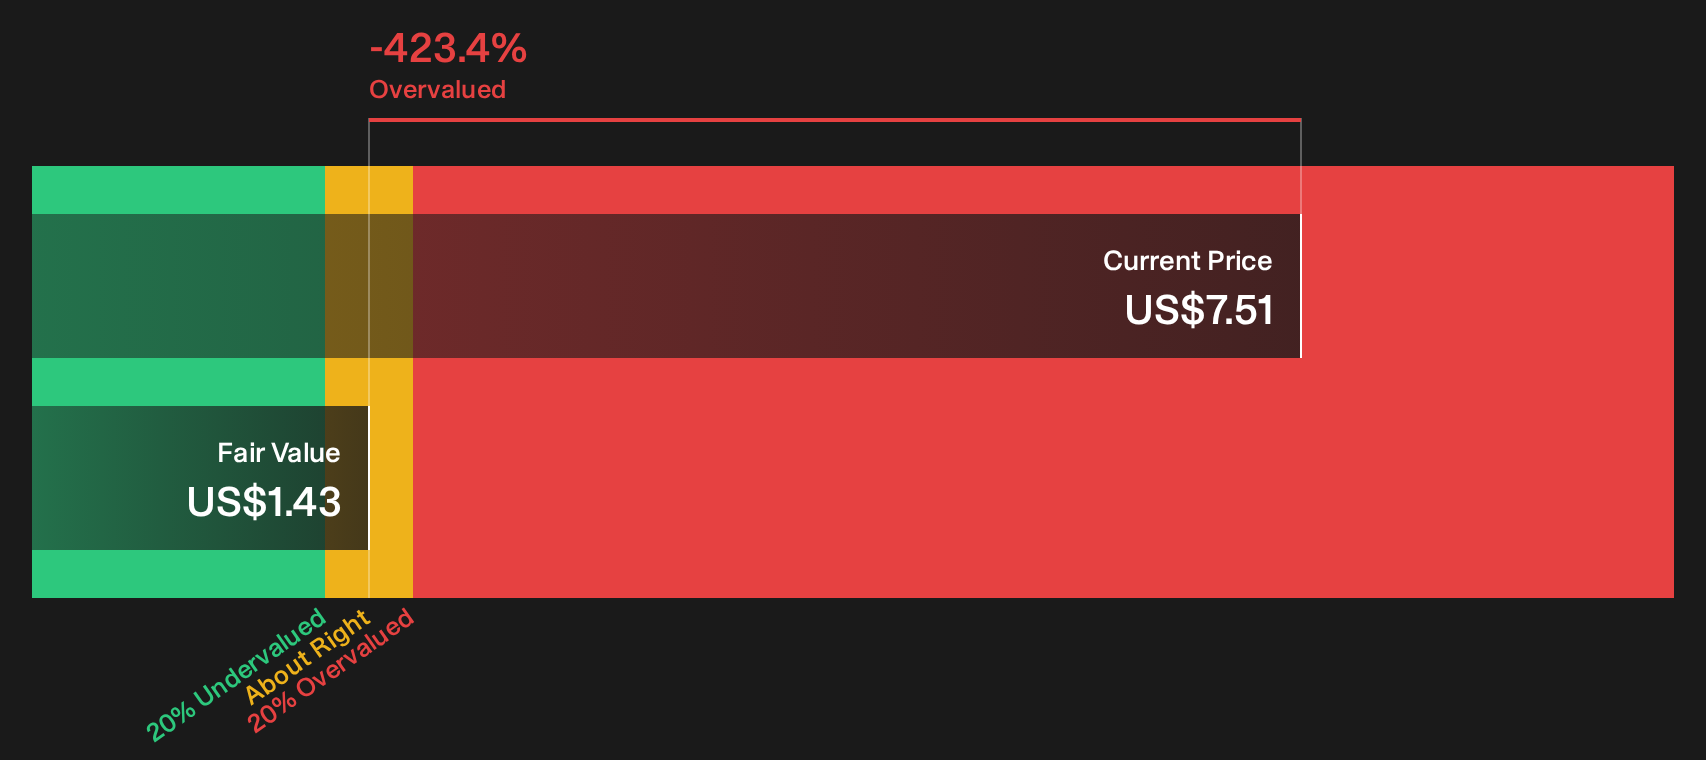
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out MasterBrand for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on MasterBrand can either freeze you or push you to test the numbers yourself and decide quickly where you stand. To weigh the downside worries against the potential bright spots, start with the 3 key rewards and 4 important warning signs.
Looking for more investment ideas beyond MasterBrand?
Do not stop your research with MasterBrand. Fresh ideas often come from comparing it with very different businesses that still match your approach and risk comfort.
- Target potential value opportunities by scanning 35 high quality undervalued stocks that combine lower pricing with solid underlying fundamentals.
- Strengthen the income side of your portfolio by reviewing 5 dividend fortresses that focus on higher yields with an emphasis on resilience.
- Dial back concentration risk by assessing 31 resilient stocks with low risk scores that emphasise balance sheet strength and steadier historical volatility.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com