


MSA Safety (MSA) Lands New Growth Drivers, Is The Upside Already Priced In?
MSA Safety (MSA) just delivered a quarter that combined strong top line progress with softer earnings, as revenue reflected Autronica driven growth while earnings per share and margins faced more pressure.
MSA Safety shares closed at US$177.60 on 3 November, with a 1-day share price return of 2.03% and a year-to-date share price gain of 9.47%. The 1-year total shareholder return of 12.35% points to steady, if recently cooling, momentum as the market weighs strong sales, softer quarterly earnings, ongoing buybacks and fresh contract wins alongside the longer multi-year record of positive total returns.
Compare MSA Safety's blend of growth, dividends, and buybacks with a curated 34 high quality undervalued stocks that currently score well on both cash flow strength and balance sheet quality.
MSA Safety now sits in an interesting spot. Recent gains reflect the better revenue line, but it is unclear whether they already capture most of the value or if there is still meaningful upside left on the table as the valuation case unfolds next.
Most Popular Narrative: 15% Undervalued
MSA Safety currently trades at $177.60, while the most widely followed narrative pegs fair value around $209.14. The story centers on whether the market is fully recognising higher margin detection, connected products, and acquisition driven growth. That narrative applies a 7.2% discount rate and assumes investors are weighing a richer mix of detection and future replacement demand against cost and regional risks.
The current valuation implies the market is not fully crediting MSA Safety for its mix shift toward higher margin detection and connected solutions, the upcoming SCBA replacement cycle, and its record of disciplined capital deployment.
Programmatic acquisitions such as Autronica and M&C TechGroup, which add roughly US$3b of fire detection addressable market and come with targeted cost synergies of 6% of Autronica revenue by around 2028, can broaden the revenue base and support operating margin and EPS compounding.
See why 4 investors see MSA Safety as 15% undervalued.
Result: Fair Value of $209.14 (UNDERVALUED)
Still, the picture can change quickly if Middle East related detection weakness lingers or if higher transport and input costs continue to squeeze gross margins.
Find out about the key risks to this MSA Safety narrative.
Another View: What MSA Safety’s P/E Is Telling You
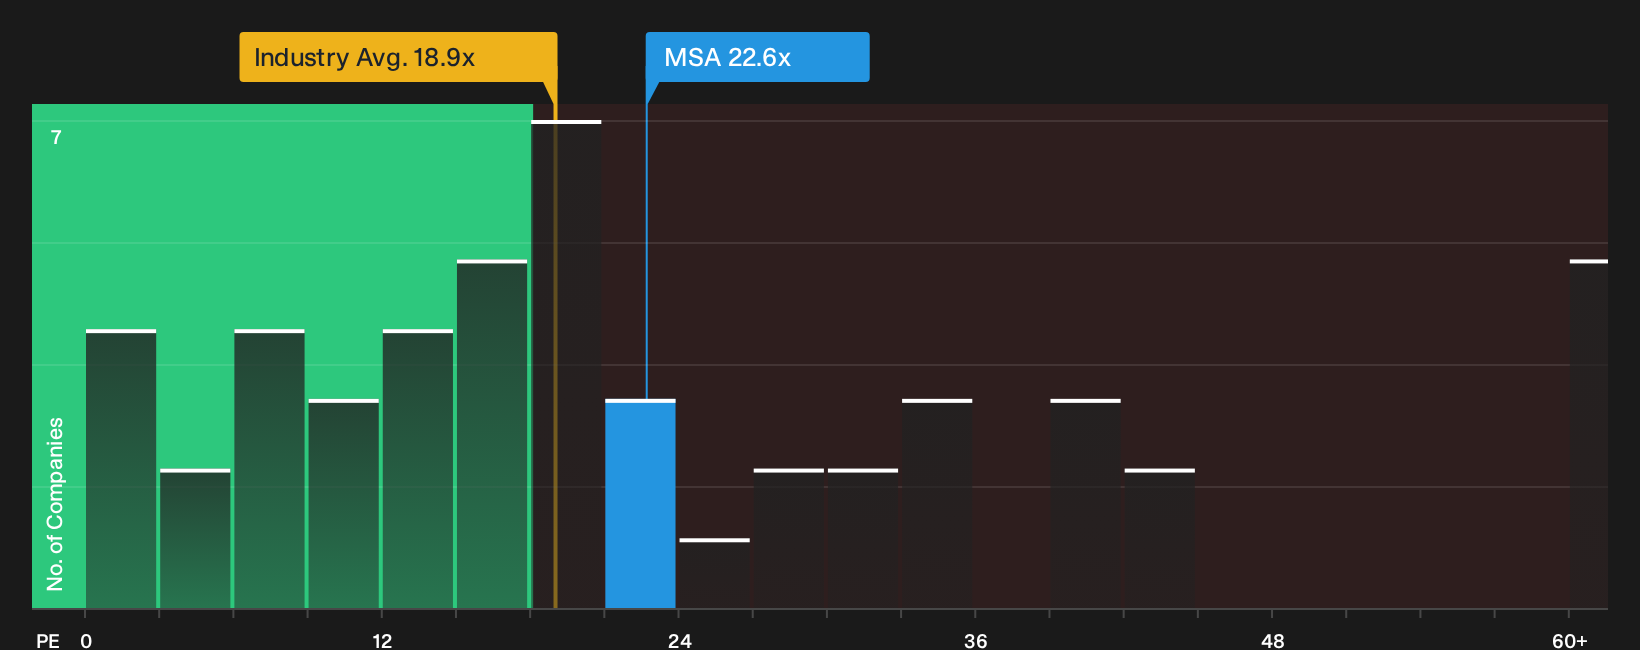
The most popular MSA Safety story leans on fair value around $209.14, yet the market is already paying a P/E of 22.6x. That is above peers at 16.1x and only slightly above a fair ratio of 22x, which suggests less margin for error if growth or margins slip. Is that premium worth paying for you?
For a closer look at how this valuation stacks up against history, peers, and the fair ratio, check the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages on valuation and risks only matter if you take the time to interrogate them yourself. Move quickly, pull apart the numbers, and pressure test your own thesis against the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond MSA Safety?
Do not stop at MSA Safety alone. Broaden your watchlist now and give yourself more ways to put cash to work before the next move arrives.
- Target steadier compounding by checking companies with resilient balance sheets and consistent fundamentals through the list of solid balance sheet and fundamentals (25 results).
- Hunt for potential mispricings by scanning a curated 19 high quality undiscovered gems that many investors may still be overlooking.
- Prioritise capital preservation first and see which businesses clear our 31 resilient stocks with low risk scores with more resilient risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com