


Profit Rebound Might Change The Case For Liberty Global (LBTY.A) Stock
- Liberty Global reported third quarter 2026 sales of US$1,920.6 million and net income of US$457.9 million, compared with a loss in the prior year period, with earnings per share from continuing operations turning positive on both a basic and diluted basis.
- Over the first nine months of 2026, Liberty Global reported US$4,367.2 million in sales and moved from a multibillion-dollar loss to a profit, indicating that recent operational and cost decisions are flowing through to the income statement rather than remaining just on the balance sheet or in restructuring plans.
- We will examine how Liberty Global's investment narrative is reshaped by this swing from a large prior-year loss to current profitability.
Scan how Liberty Global's swing back to profitability compares with other communications and media stocks showing strong balance sheet support and cash generation in our hand picked 35 high quality undervalued stocks list.
Liberty Global Investment Narrative Recap
For an investor to stay with Liberty Global, the core belief is that the telecom and media footprint can turn current operating momentum into steadier cash generation, despite heavy investment needs. The move from a multibillion dollar loss over the prior nine month period to a US$430.6 million profit puts more weight on that view, yet does not remove execution risk around cost control and capital intensity.
In the short term, the key catalyst is whether this profitability holds while spending on network upgrades and AI driven efficiencies is managed sensibly. The biggest risk remains pressure in competitive markets such as the UK and Belgium, where pricing, churn and required capital expenditure could again squeeze margins and slow any effort to improve leverage.
The most relevant data point at the moment is the nine month 2026 result. Liberty Global reported US$4,367.2 million in sales and net income of US$430.6 million, compared with a multibillion dollar loss a year earlier. Earnings per share from continuing operations turned positive on both a basic and diluted basis, which directly addresses previous concerns about persistent losses.
That shift is closely related to the catalysts around asset monetisation, Ziggo Group plans and network modernisation. A period of positive earnings gives management more room to continue pursuing infrastructure deals and AI cost programmes without every move being viewed purely through a balance sheet repair lens, although competition, leverage and technology disruption still remain central considerations for anyone tracking the next few quarters.
Liberty Global's current analyst narrative points to forecast revenues of US$7.7 billion and earnings of US$676.5 million by 2029. That profile assumes revenue expansion of 16.2% per year and an earnings swing of roughly US$3.7 billion, from a US$3.0 billion loss today to the projected profit level.
Uncover why Liberty Global's fair value indicates a 67% potential upside to its current price that could narrow quickly.
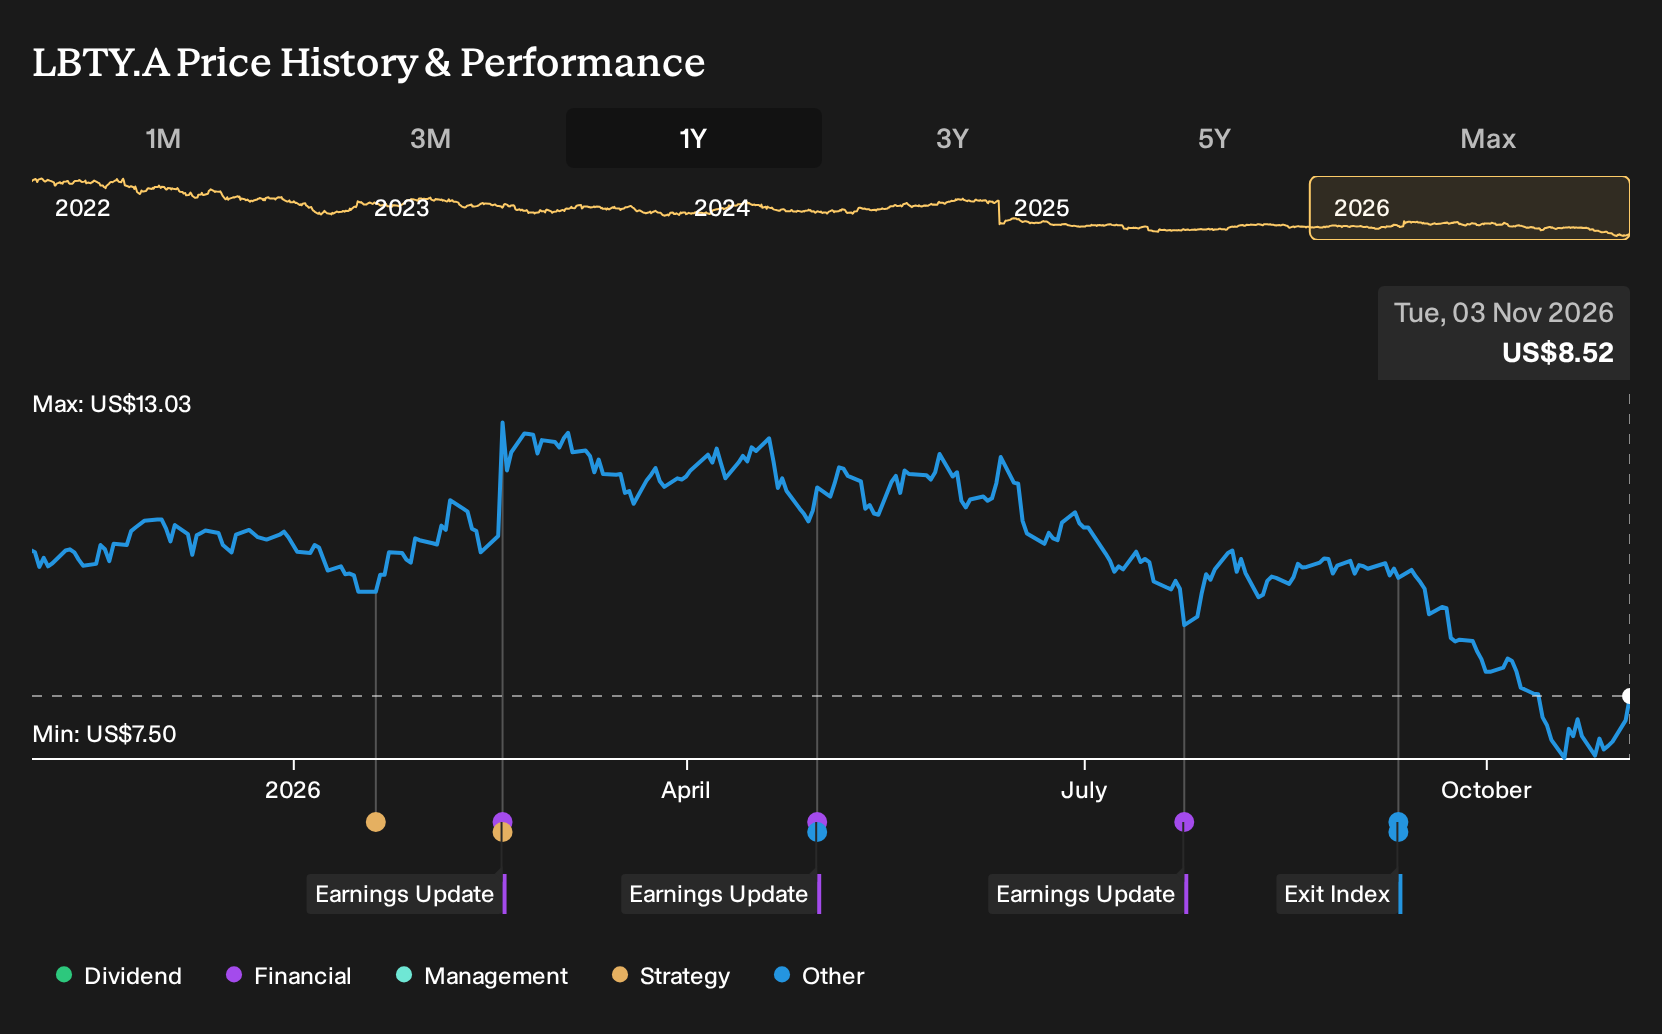
Exploring Other Perspectives
One alternate view on Liberty Global focuses on the risk that heavy Virgin Media O2 capital spending keeps squeezing cash, even after this profit rebound. The most cautious analysts were pencilling in about US$7.3b of 2029 revenue and US$649.6 million of earnings on a low 5.1x P/E, so their story is far more sceptical. Those numbers were set before the latest results, so treat them as starting points and compare several narratives before deciding what makes sense for you.
Explore 2 other Liberty Global fair value estimates, including one that suggests it could be worth just $12.00!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Liberty Global research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Liberty Global. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Liberty Global's overall financial health at a glance.
Looking for more investment ideas beyond Liberty Global?
Once you have formed a view on Liberty Global, it can help to compare it with other companies that fit the type of opportunity you are hunting for. Use the Simply Wall St Screener to filter for financial traits that match your approach instead of just following headlines.
- If you care most about quality at a sensible entry point, scan a curated group of stronger balance sheet and cash flow stories in our 35 high quality undervalued stocks.
- If resilience and capital protection sit at the top of your checklist, focus on a 30 resilient stocks with low risk scores that score well on stability and downside control.
- If you want to hunt for less crowded situations with solid fundamentals, cast a wider net across our 19 high quality undiscovered gems that many investors may not be watching yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com