


3 European Housing Stocks Retail Investors Are Watching As Policy Risk Resets
European housing is suddenly political theatre, with calls for rent caps, fresh construction and protection from foreign competition all colliding at once. That mix can punish some listed companies while giving others a longer runway. This piece walks through that fault line and pinpoints three European housing construction and building materials stocks exposed to these policy shifts, so you can judge whether the current reset is a threat, an opening, or both.
The stocks in the list below are just a small sample, and the full screen surfaced 49 more European construction and building materials companies with equally compelling narratives that are not covered here. If you want to identify potential front-runners in this theme, head straight to the European Housing Construction and Building Materials screener to filter, analyze and focus on the housing-linked ideas that best fit your playbook.
Nexity (ENXTPA:NXI)
Nexity plugs directly into the European Housing Construction and Building Materials theme as a large French developer shaping new residential projects while also running offices, logistics sites, hotels and serviced properties that tie into how cities are rebuilt and lived in.
Nexity generates most of its €2.58b revenue from Promotion at about €2.16b, with Services contributing roughly €415 million and Other Activities a small €6 million, and the group currently carries a market value of about €230 million.
Leadership in urban regeneration and brownfield redevelopment, with 1,200,000 square meters under development and the Carrefour partnership, positions Nexity to benefit from long term demand for city revitalization. This can support residential and commercial revenue and help sustain project level margins.
What happens if a single pressure on Nexity’s cost base shifts just as political support for new housing turns into concrete permitting and funding decisions?
If that cost shift is what matters most, the full narrative for Nexity shows how Nexity’s urban pipeline, balance sheet pressures and policy tailwinds could be quietly decoupling.

Glenveagh Properties (ISE:GVR)
Glenveagh Properties is the pure-play Irish homebuilder in this housing theme, with every euro tied to getting more new homes built rather than collecting legacy rents. This makes policy support for construction far more important than short term sentiment around regulation or rates.
The extension of the 9% VAT rate on apartments to 2030 is a massive tailwind. It directly increases the DCF cash flows in Phase 1 by lowering the break-even point on the Urban landbank (13% of total plots).
What really matters next is how one pressure point in Glenveagh Properties’ cost base interacts with that policy support for Irish housing delivery.
Glenveagh Properties is a pure-play Irish builder of houses and apartments, tightly linked to European housing construction, with €390 million from Homebuilding and €434 million from Partnerships and a market value of about €1.2b.
That single pressure point is where things get interesting, and the full narrative for Glenveagh Properties maps how Glenveagh Properties’ VAT break, cost shifts and partnerships could be quietly accelerating value.

Mota-Engil SGPS (ENXTLS:EGL)
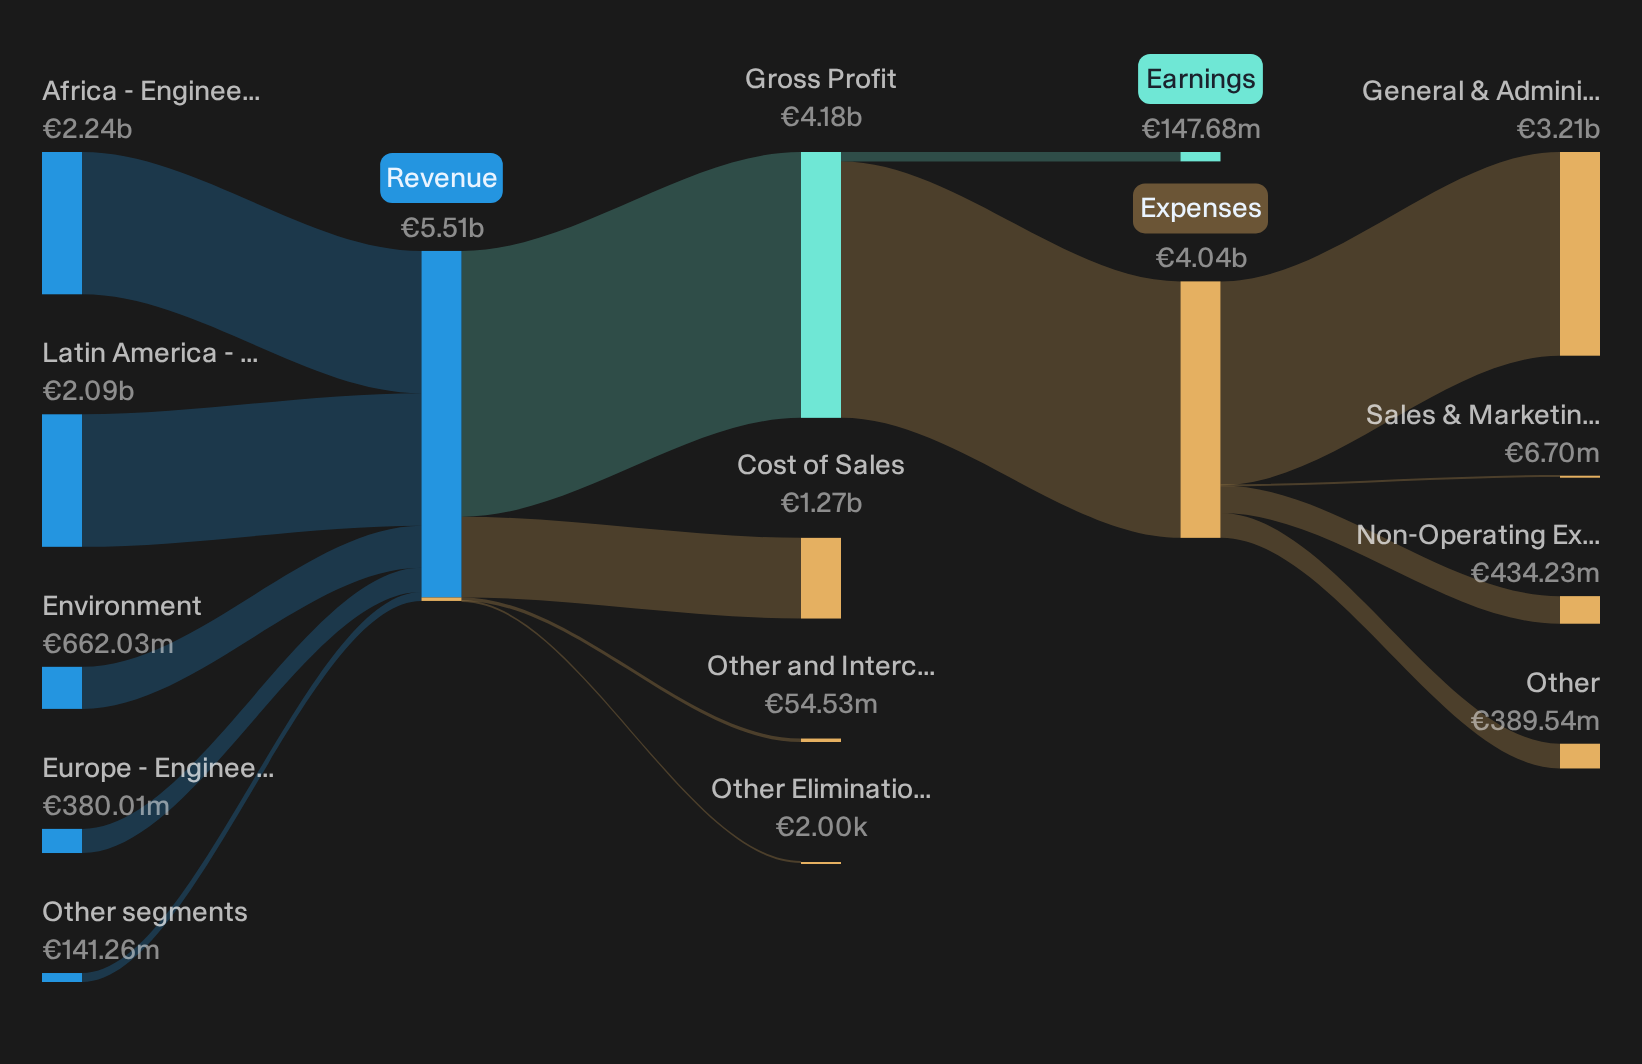
Mota-Engil SGPS plugs into the European Housing Construction and Building Materials theme through large public and private construction work, generating about €2.24b from Africa E&C, €2.09b from Latin America E&C, €380 million from Europe E&C and carrying a roughly €1.37b market cap.
Mota-Engil SGPS matters here because it is one of the few listed contractors that can connect European housing demand to the heavy infrastructure that makes new districts possible, from roads and rail links to utilities and social buildings. This gives additional substance to this housing-focused screen.
As always, given the riskiness of the company, both in its cyclicality and geographic exposure to risky countries, investors may wish to consider a higher margin of safety if an opportunity arises.
One question for investors is what could happen if an unseen pressure on Mota-Engil SGPS’s future project pipeline and pricing power were to emerge at the same time as housing investment increases.
That hidden pressure point is exactly what the full narrative for Mota-Engil SGPS unpacks, separating headline risk from the projects that could accelerate Mota-Engil SGPS over the next cycle.
Seeking Alternatives Before Momentum Flies
Fresh themes move fast. Once momentum hits, the cleanest entries get snapped up and the data edge starts dropping. Scan under-the-radar ideas while it matters and get in early.
- Spot resilient cash generators early by running the list of solid balance sheet and fundamentals (195 results) that highlights businesses built to handle shocks before the crowd catches on.
- Ride targeted income ideas by checking the 221 dividend fortresses focused on companies combining higher yields with balance sheets that still look built to last.
- Track the next infrastructure-led breakout by using the 41 power grid technology and infrastructure stocks packed with potential beneficiaries of grid upgrades while they are still under the radar for now.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com