


Coinbase Global (COIN) Posted Mixed Results, Is The Upside Already Priced In?
Coinbase Global (COIN) just posted third quarter results that combined weaker top line figures with stronger profitability, giving investors fresh numbers to reassess the crypto platform’s business model and risk profile.
The share price reaction has been choppy. Coinbase Global rallied 5.53% on the day of the latest move to about US$145, yet the 7 day share price return is down 10.39% and the 30 day share price return is down 22.72%, while the year to date share price return has fallen 38.51% and the 1 year total shareholder return is down 54.45%. Even though the 3 year total shareholder return is up 64.69%, this points to long term holders still being ahead, while shorter term momentum has clearly faded as investors digest weaker revenue, mixed regulatory headlines and new product announcements around areas such as stablecoins and quantum security.
Scan beyond Coinbase Global and review a curated group of crypto and blockchain related platforms in the 21 cryptocurrency and blockchain stocks that may be reacting differently to the same headlines.
After a sharp pullback, even as Coinbase Global prints stronger earnings per share, the question now is simple. Is most of the good news already in the price, or is meaningful upside still on the table as you look at valuation next?
Most Popular Narrative: 41% Undervalued
On the narrative view, Coinbase Global is priced well below its implied worth, with the latest close at $145.45 against a fair value of $247.39. That gap anchors a thesis that treats the stock less like a steady financial platform and more like a leveraged expression of long term crypto adoption.
I think Coinbase is best understood as a leveraged bet on long-term crypto adoption, rather than a normal operating business with smooth, predictable growth.
What matters most is not whether next year looks clean, but whether crypto becomes a meaningfully larger asset class over time. If that happens, Coinbase should benefit through higher trading activity, higher asset values on the platform, and growth in its custody and subscription businesses.
See why 27 investors see Coinbase Global as 41% undervalued.
Result: Fair Value of $247.39 (UNDERVALUED)
Still, this narrative breaks quickly if crypto trading volumes stay subdued or if regulators tighten rules in ways that compress the fee structure at Coinbase Global.
Find out about the key risks to this Coinbase Global narrative.
Another View: Multiples Paint A Tougher Picture For Coinbase Global
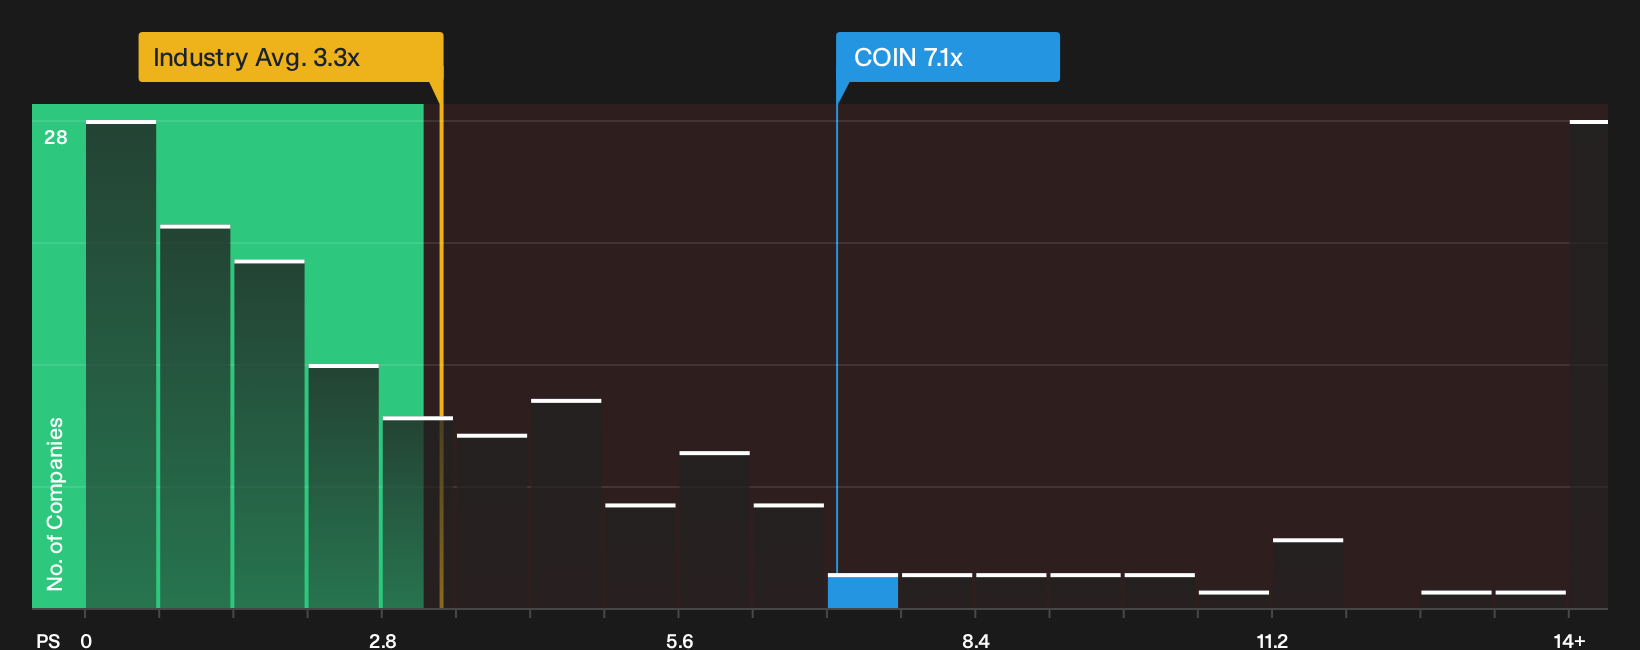
The SWS DCF narrative leans toward Coinbase Global looking undervalued, yet the simple P/S lens tells a different story. At 7.1x sales against a US Capital Markets industry average of 3.3x and a fair ratio of 4.2x, the stock carries a clear valuation premium that could matter if sentiment cools again.
For a closer look at how that gap stacks up against peers and the fair ratio the market could move toward, have a read of the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and concern around Coinbase Global feels conflicted, move quickly, review the underlying data, and put your own stamp on the thesis with 1 key reward and 1 important warning sign
Looking for more Coinbase Global investment ideas?
Do not stop with Coinbase Global. Use the Simply Wall Street Screener to surface fresh opportunities that match your risk tolerance, income goals, and time horizon.
- Target resilient growth by hunting for companies that combine strong balance sheets with solid fundamentals in the list of solid balance sheet and fundamentals (23 results).
- Prioritize sleep-at-night stability and filter for companies with lower risk profiles using the 30 resilient stocks with low risk scores.
- Spot early movers by scanning a curated set of underfollowed stocks with strong fundamentals in the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com