


Etsy (ETSY) Beat Expectations, Is The Upside Already Priced In?
Etsy (ETSY) just posted third quarter 2026 earnings that beat expectations, highlighted renewed active buyer growth and leaned heavily on AI driven personalization, targeted marketing and marketplace improvements as management discussed plans for continued investment.
Etsy’s recent earnings beat landed against a strong run in the shares, with a 30-day share price return of 23.48% and year to date gain of 56.88% as investors reacted to active buyer growth, the buyback program and the new holiday campaigns. At the same time, total shareholder return of 54.21% over one year and a much weaker 5-year total shareholder return of 65.26% show that near term momentum has improved sharply, while longer term holders are still deep in recovery mode.
Ride Etsy’s AI and marketplace momentum by scanning a curated set of 35 high quality undervalued stocks that combine stronger balance sheets with cash flows the market may be underpricing.Etsy’s comeback story is already reflected in a big chunk of the recent share price jump. The next step is to see whether today's valuation still leaves meaningful upside on the table or mostly prices in the recovery.
Most Popular Narrative: 2% Undervalued
Etsy's most widely followed valuation narrative points to a fair value of $91.81, which sits just above the last close at $89.86 and leaves only a modest gap for investors to weigh against the recent share price surge.
The capital light Etsy marketplace model, which converted 81% of adjusted EBITDA to free cash flow in Q2 2026 and is supported by EBITDA margins near 29 to 30%, together with more than US$2.5b already available or authorized for share repurchases, creates scope for ongoing reductions in share count that could amplify any future earnings growth per share.
See why 39 investors see Etsy as 2% undervalued.
Result: Fair Value of $91.81 (UNDERVALUED)
Still, the Etsy narrative can unravel if external AI shopping assistants siphon off discovery and if AI generated goods erode the marketplace’s reputation for authenticity.
Find out about the key risks to this Etsy narrative.
Another View: Etsy On Earnings Multiples
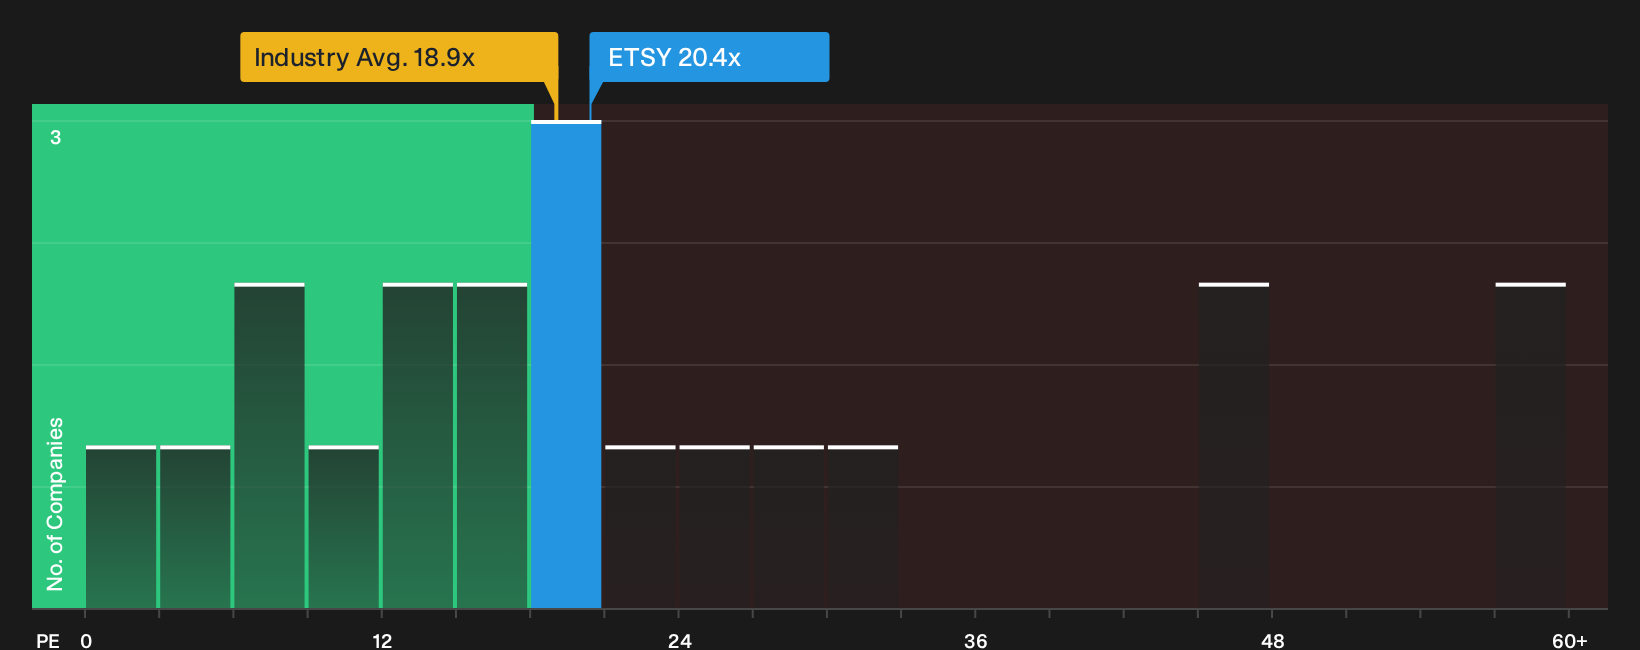
Etsy screens as cheap on cash flow models, yet the current P/E of 20.4x tells a different story. That multiple sits above the global Multiline Retail industry on 18.9x and well ahead of Etsy’s own fair ratio of 14.9x, which points to a clear valuation premium rather than a discount. For investors, the question is whether that higher multiple reflects durable strength or leaves little room for disappointment.
For a closer look at how this earnings multiple stacks up against sector peers and the fair ratio the market could move toward, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Reading the mix of optimism and caution around Etsy so far, it makes sense to move quickly and test the numbers against your own thesis. The easiest way to stress test that view is to weigh both sides using the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Etsy?
If Etsy has sharpened your focus, now is the moment to expand your watchlist and line up a few more high conviction candidates before the next move.
- Target resilient balance sheets and steady fundamentals by filtering a focused list of solid balance sheet and fundamentals (23 results) that can handle a range of business conditions.
- Spot potential mispricings early by scanning a curated 19 high quality undiscovered gems before the crowd starts paying attention.
- Prioritize stability and capital protection by reviewing a 30 resilient stocks with low risk scores designed to keep downside risk front and center.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com