


Centerspace (CSR) Q3 Earnings Lean On One Off Gain As Revenue Falls
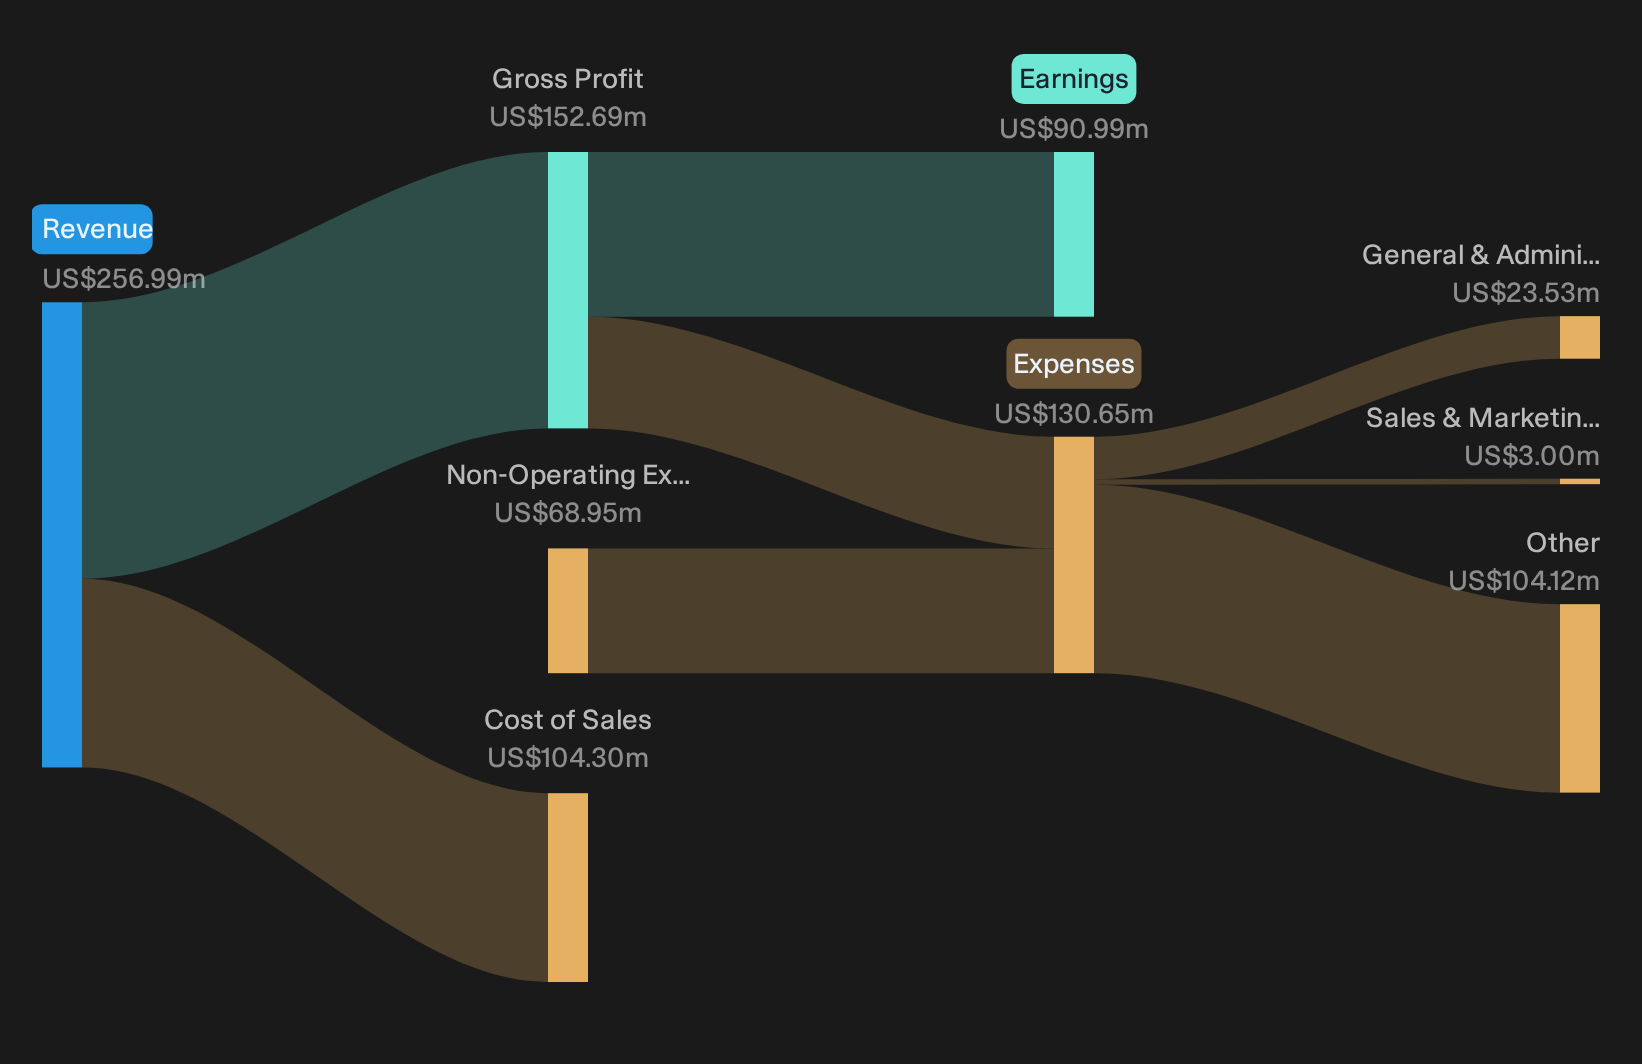
Centerspace came into this Q3 2026 report trading like a discounted income story, with the stock roughly flat over three months and priced on a single digit P/E against peers. The headline this quarter is simple. Reported earnings swung to a Basic EPS of US$7.34 on modest revenue of US$59.52 million, shaped largely by a one off gain that flatters profit.
The share price still slipped 3.2% today to US$57.26. That move appears to reflect investors questioning how durable that profit picture is once the one off boost fades, rather than a collapse in the real estate investment trust story.
Like the high headline EPS from Centerspace but concerned that so much of it hangs on a one off gain instead of recurring cash flow? Check out our list of income oriented real estate stocks screened for cleaner earnings quality in the list of solid balance sheet and fundamentals stocks (23 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): US$59.5 million vs. US$71.4 million (top line declined 16.5%)
- Net Income (Excl. Extra Items, Q3 2026 vs Q3 2025): US$123.3 million vs. US$53.8 million (profit more than doubled, heavily shaped by a large one off gain)
- Basic EPS (Q3 2026 vs Q3 2025): US$7.34 vs. US$3.22 (per share earnings more than doubled, largely driven by the non recurring gain)
- Funds From Operations (FFO, Q3 2026 vs Q3 2025): US$23.5 million vs. US$23.3 million (core real estate cash earnings were broadly stable)
Earnings can swing around when one off gains hit the income statement, but cash generation tends to anchor what long term investors are willing to pay for Centerspace.
When you focus on Centerspace's cash flows instead of the headline profit jump, the stock could be a striking 33% undervalued.
Evaluating Centerspace’s Execution Milestones So Far
For the bullish view to hold, Centerspace needs to prove that its reshaping and merger plans translate into real progress, not just promises.
"The main requirement for this thesis is successful execution on asset sales, deleveraging to the mid 6x net debt to EBITDA range and realization of the projected cost synergies from the Independence Realty Trust combination."
On that score, Centerspace has already ticked important boxes. The firm closed US$288.8 million of property sales and fully repaid its credit lines, which directly supports the deleveraging leg of the plan. The Independence Realty Trust merger is signed, with a shareholder vote set for November 10, 2026, moving the synergy story from concept to a concrete timetable.
The price and this Narrative do not agree. → Uncover what this Narrative says Centerspace is actually worth.
Centerspace Bear Case: Portfolio Remix Still Untested
The cautious view argues that Centerspace’s portfolio reshuffle trades earnings power for balance sheet repair.
"The loss of these higher performing properties could lead to flatter long term revenue and Core FFO trends than investors expect."
Q3 gives that fear some footing. Revenue declined 16.5% year on year even with US$288.8 million of asset sales completed, and the share price slipped 3.2% on the print. Core real estate cash earnings, via FFO, were broadly unchanged at US$23.5 million. That flat profile means the heavier Denver and Minneapolis mix has not yet shown up as a stronger earnings engine.
Hunt For Mispriced Earnings Power
Centerspace shows how a clean headline number can still leave investors debating the quality of the underlying engine. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 39% below our estimate - proves lidar can move from pilot projects to mass production as unit shipments surge across real auto programs.
- Company 2 - 33% below our estimate - leans into AI data centre demand while its software stack keeps customers tied closely to its accelerator ecosystem.
- Company 3 - 17% below our estimate - expands from trackers into storage and inverter offerings so project partners deepen spending across a broader hardware platform.
Those are three of them. See the full list of 35 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com