


Can Alnylam Pharmaceuticals (ALNY) Justify Its Price After A 62% Fall?
Alnylam Pharmaceuticals has seen its share price fall sharply over the past year, even as fresh clinical data and earnings headlines keep arriving. This puts the focus squarely on whether the current valuation still lines up with what the business earns today. For investors watching a stock under pressure but backed by active RNA interference programs, the key issue is how the recent price slide interacts with the earnings power that ultimately needs to support it.
- The share price has fallen 62.3% over the past year, which raises the question of whether that decline has brought the valuation closer into line with the company’s underlying earnings profile.
- Recent updates on transthyretin treatments and Huntington's disease programs may support expectations for future revenue and profitability, which can influence how much investors are willing to pay for each dollar of Alnylam Pharmaceuticals' earnings.
- Your read on Alnylam Pharmaceuticals is one view; the desks covering it have another. See what analysts think Alnylam Pharmaceuticals's shares could be worth.
The stock's next move may depend on whether the current share price is justified by Alnylam Pharmaceuticals' earnings when set against the Fair Ratio benchmark.
If you want to test the same earnings-based valuation question you are asking of Alnylam Pharmaceuticals across a wider field, scan through 35 high quality undervalued stocks.
Is Alnylam Pharmaceuticals a Bargain on Earnings?
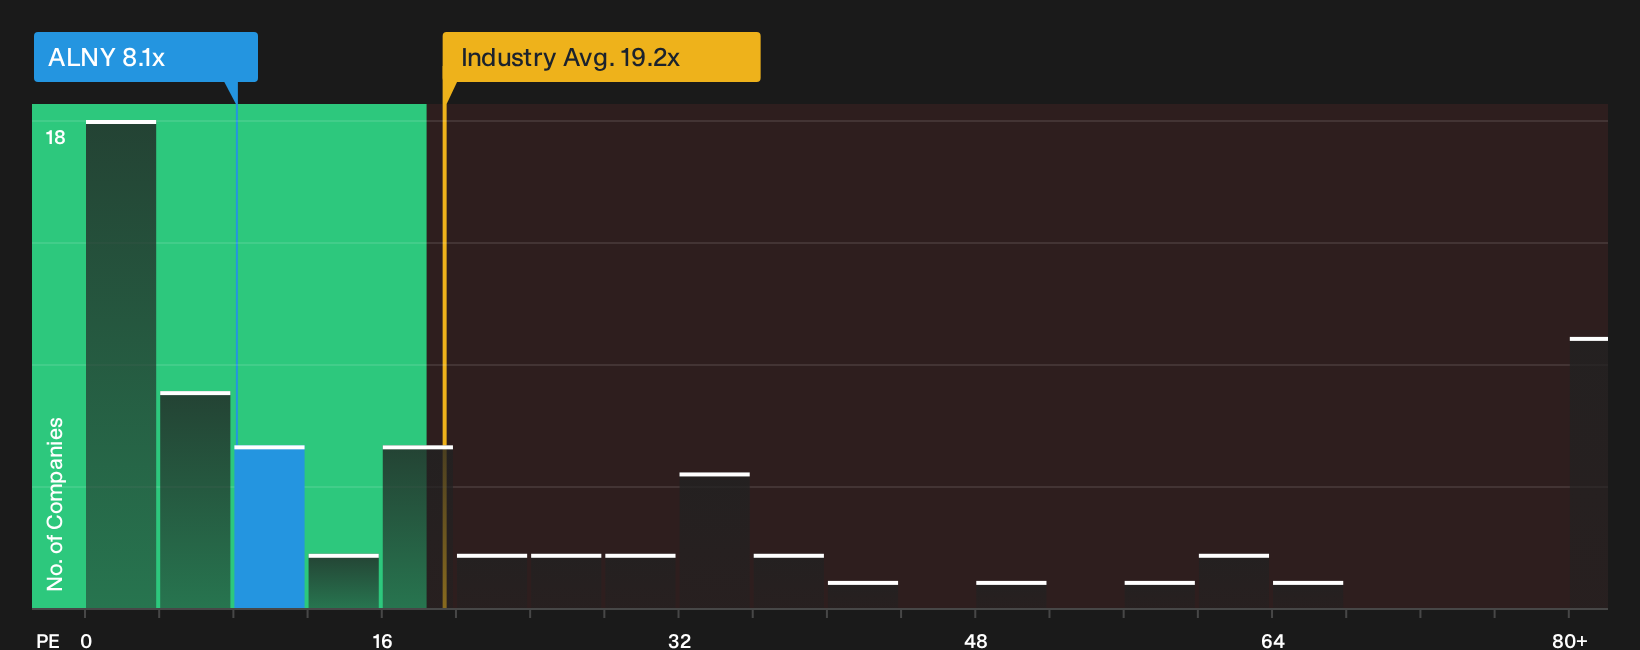
P/E works well for Alnylam Pharmaceuticals at this stage because the business is now reporting profits that give the ratio real earnings behind it. The current P/E sits around 8.1x, which is well below the Biotechs sector average of about 19.2x and also below the broader peer group near 44.0x. On the face of it this means investors are currently paying far less for each dollar of Alnylam Pharmaceuticals' earnings than for many comparable drug developers.
The Fair Ratio, which looks at factors like growth prospects, profitability, size and risk together, points to a higher multiple than where the stock currently trades, so the P/E signals the shares screen as undervalued on this framework. Because the company recently reported strong Q3 2026 earnings yet still trades on a discount P/E to the sector and peers, the market is not giving those results a full valuation uplift. To see how large that gap is and whether it looks worth acting on, check the detailed multiple workup in. Explore the numbers behind Alnylam Pharmaceuticals's P/E valuation.
The Alnylam Pharmaceuticals Narrative: What Would Justify Today's Price?
Narratives for Alnylam Pharmaceuticals pick up where the P/E puzzle leaves off by spelling out in plain terms what growth, margin and earnings paths would need to play out for the current share price to look high or low. Each scenario lays out the assumptions that sit behind its view of fair value so you can track those inputs against Alnylam Pharmaceuticals' future results as they are reported.
One of the top community narratives on Alnylam Pharmaceuticals: 52% undervalued
"The broad RNAi portfolio at Alnylam Pharmaceuticals, with more than 25 programs and multiple pivotal studies underway, creates repeated opportunities…"
Discover why this Narrative puts Alnylam Pharmaceuticals at 52% undervalued.
Before you move, there is one more factor to weigh for Alnylam Pharmaceuticals
Price tags and earnings multiples only tell part of the story, because the people steering Alnylam Pharmaceuticals and the way their pay is structured can heavily shape future decisions and risk. See who runs Alnylam Pharmaceuticals and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com