


AutoZone (AZO) CFO Exit Puts Valuation Back In Focus
Why AutoZone’s CFO Exit Has Put Leadership Under The Microscope
AutoZone (AZO) has been pushed into the spotlight after Chief Financial Officer Jamere Jackson resigned, effective November 25, 2026, with Vice President and Controller J. Scott Murphy set to assume key financial officer responsibilities.
The CFO exit comes at a tricky moment for sentiment. AutoZone’s share price has climbed 14.6% over the past month even though the year-to-date share price return is down 3.1%. The 1-year total shareholder return has declined 13.0%, compared with a 71.5% gain over five years. This indicates that short-term momentum is improving as investors reassess leadership and long-term execution.
Spot shifts in leadership driven sentiment at AutoZone and then extend your watchlist using a curated set of 29 resilient stocks with low risk scores that focus on resilience when headlines change.AutoZone appears to be a solid auto parts retailer on the surface, and the recent 14.6% share price jump in a month reinforces that view. The key question now is whether that strength is already fully reflected in today’s valuation.
Most Popular Narrative: 13% Overvalued
AutoZone last closed at $3,200, while the most followed narrative fair value sits at $2,829. This frames the recent share price rebound as running ahead of what that analysis supports.
The new-store economics arrived this quarter with numbers attached. A store now assumes $1.7 million in first-year sales, ramping to $2.7 million by year six, against an average investment of $2.9 million. This is a path management says produces roughly 15% ROIC by year four and north of 20% by year six. The prior call’s answer to the same underlying question was qualitative: new stores were “performing better” than the pro forma, full stop. Investors who wanted math instead of adjectives got it.
See why 2 investors see AutoZone as 13% overvalued.
Result: Fair Value of $2,829 (OVERVALUED)
Still, AutoZone’s narrative leans heavily on guided domestic comp resilience and disciplined SG&A. Any renewed DIY softness or expense creep could quickly challenge that story.
Find out about the key risks to this AutoZone narrative.
Another Lens On AutoZone’s Valuation
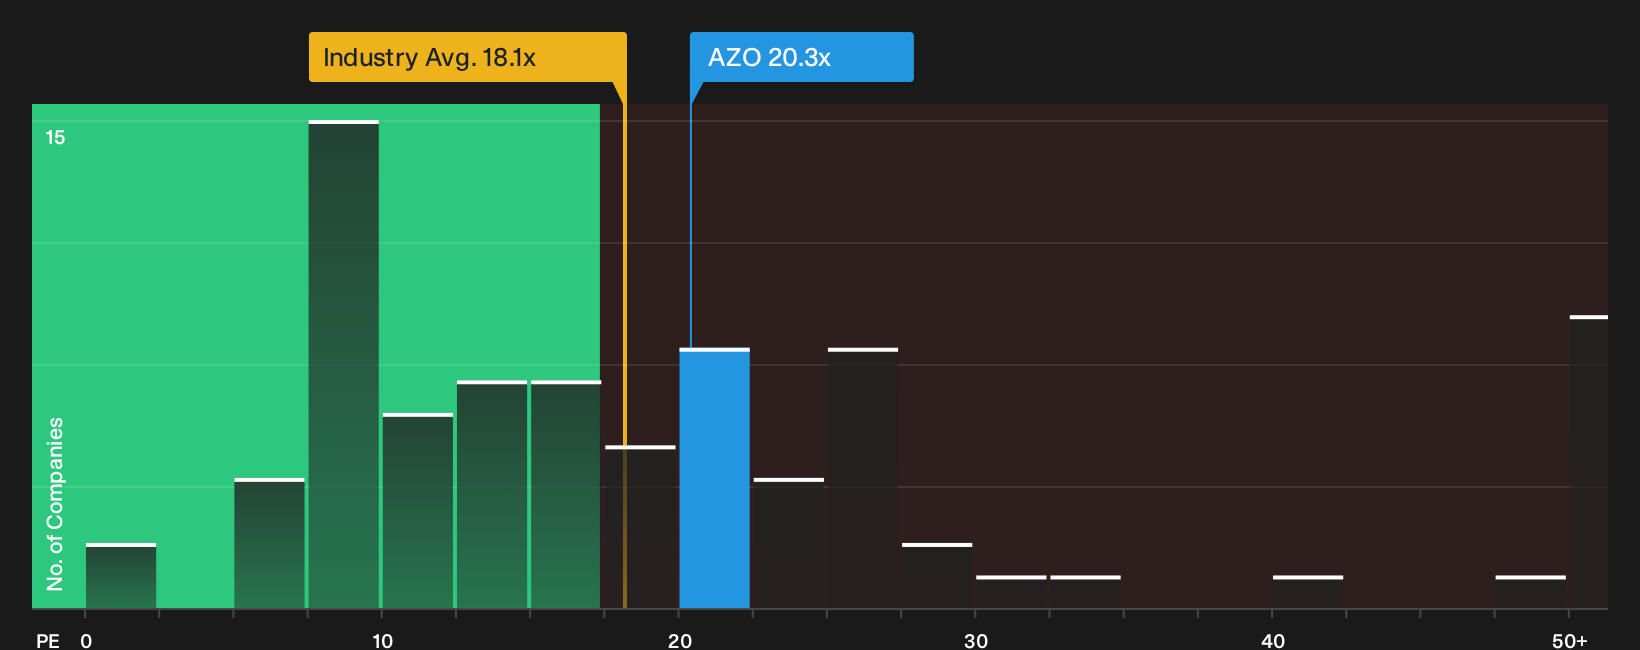
The first narrative pegs AutoZone as 13% overvalued at $3,200 versus a fair value of $2,829. A different lens uses earnings. At a 20.3x P/E, the stock trades richer than the US Specialty Retail average of 18.1x and slightly above a 20.1x fair ratio.
Peers on average sit at 21.7x, so AutoZone effectively threads the gap. That narrow spread around the fair ratio leaves less margin for error. Investors are left weighing whether current earnings quality and growth justify paying close to what the model suggests the P/E could move toward, or whether patience makes more sense.
See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out AutoZone for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
The sentiment around AutoZone is split enough that waiting on someone else’s verdict could mean missing key shifts in risk and reward. Act quickly, pull apart the underlying drivers yourself, and weigh the 3 key rewards and 2 important warning signs.
Looking For More Ideas Beyond AutoZone?
If AutoZone has sharpened your focus on risk, reward, and pricing, broaden your opportunity set with a few targeted screeners that surface very different types of businesses.
- Target resilient balance sheets by scanning a curated list of solid balance sheet and fundamentals (24 results) that can help reduce financial stress risk when conditions change suddenly.
- Hunt for potential bargains using a focused 34 high quality undervalued stocks that highlights companies combining quality fundamentals with prices that lag underlying metrics.
- Spot early-stage potential by reviewing a selective 9 elite penny stocks with strong financials that filters for smaller listings with stronger financial underpinnings than the wider microcap universe.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com