


CVR Energy (CVI) Posted Strong Q3 Earnings, Is It Already Above Fair Value?
Why CVR Energy's latest earnings matter for shareholders
CVR Energy (CVI) just put fresh third quarter numbers on the table, with higher sales and net income than a year earlier, and that earnings release is what moved this stock into focus.
Recent trading tells a slightly different story to the earnings headline. CVR Energy’s share price has pulled back, with a 1-day share price return of 4.2% down and a 7-day share price return of 9.8% down, even though the 90-day share price return of 67.8% and year to date share price return of 122% suggest strong momentum that has cooled in the very short term, while the 5 year total shareholder return of 346.8% shows how powerful the longer journey has been.
Scan beyond CVR Energy and see how it compares with other US-listed energy players by reviewing the hand picked list of solid balance sheet and fundamentals (24 results).
CVR Energy now trades above the average analyst target, even after the latest pullback. Is the market overreacting to strong recent earnings, or is it correctly pricing in the risks that a simple fair value discount cannot capture?
Most Popular Narrative: 16.5% Overvalued
CVR Energy last closed at $55.92, while the most followed narrative anchors fair value at $48.00. The story hinges on whether current earnings power truly supports that gap.
The main factor that has to go right is that CVR Energy contains rising RFS compliance and hedge losses that already consume more than twice all other refinery operating costs and have produced large realized and unrealized crack spread losses.
The current numbers, including sizable RIN expense, hedge losses and a modest recurring dividend, imply a share price that already reflects strong refining and fertilizer conditions while leaving limited room for setbacks, which supports a view that CVR Energy may be overvalued.
See why 6 investors see CVR Energy as 17% overvalued.
Result: Fair Value of $48 (OVERVALUED)
Still, the narrative can break if CVR Energy faces extended refinery outages again, or if RFS compliance and hedge losses expand faster than current assumptions.
Find out about the key risks to this CVR Energy narrative.
Another View: CVR Energy through a cash flow lens
The analyst narrative pegs CVR Energy at $48 and leans on earnings and multiples, yet Simply Wall St's DCF model points the other way. In that framework, CVR Energy at $55.92 trades well below an estimated future cash flow value of $434.43, which raises a simple question. Is the earnings based story missing something buried in long term cash generation?
Look into how the SWS DCF model arrives at its fair value.
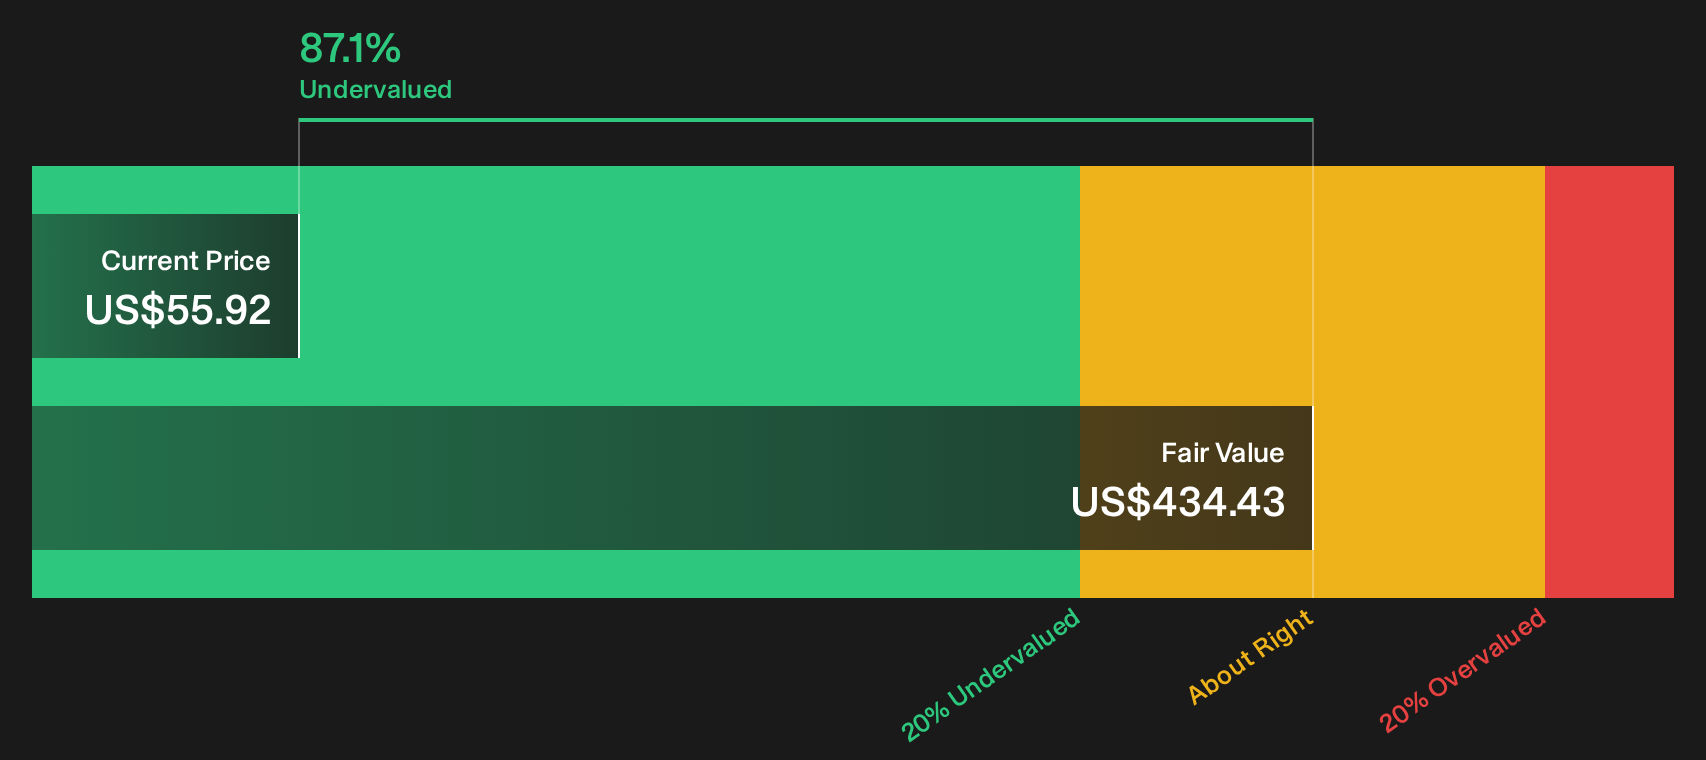
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out CVR Energy for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on CVR Energy is clearly split, which is exactly why you should move fast, review the numbers directly and decide where you land on that spectrum by weighing the 3 key rewards and 1 important warning sign.
Looking for more CVR Energy sized ideas?
If CVR Energy has your attention, do not stop here. Use this window of focus to line up a broader bench of opportunities that fit your style.
- Target resilience first and scan a 29 resilient stocks with low risk scores that could help you focus on businesses with steadier profiles and fewer red flags.
- Hunt for pricing gaps and review a curated 34 high quality undervalued stocks that may have stronger balance sheets than their current market tags suggest.
- Prioritise durability and income by lining up a 4 dividend fortresses that leans toward higher yields backed by underlying fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com