


Kinder Morgan (KMI) Lifts Dividend And 2026 Outlook, Is The Stock Still Cheap?
Kinder Morgan (KMI) just paired higher third quarter sales and earnings with a 2% dividend increase and fresh 2026 net income guidance, giving investors a clearer picture of cash generation and capital priorities.
Despite the solid third quarter update, Kinder Morgan’s share price has slipped about 3% over the past week and on the day of the release, after a roughly 5% gain over the past month and an 18% year to date share price return. This points to momentum moderating in the very short term but still remaining firmly positive over a longer stretch.
Scan Kinder Morgan’s latest move against a wider income playbook by lining up its dividend update with a curated set of 4 dividend fortresses.
That sets up the real tension. Kinder Morgan trades at a clear discount to both intrinsic estimates and analyst targets after this pullback, so is the market correctly pricing in caution, or is it leaning too hard on old worries?
Most Popular Narrative: 12% Undervalued
On the latest numbers, Kinder Morgan closed at $32.71 against a narrative fair value of $37, with that gap framed using a 7.24% discount rate and tied directly to how much of its growth backlog ultimately converts into cash flow.
The current roughly $9.6b Board approved growth backlog, which is mainly tied to take or pay natural gas projects with an average in service date in the first half of 2028, is expected by management to translate into about $1.7b of incremental EBITDA over time, which could lift Kinder Morgan's future cash generation as these assets move from construction to operation.
See why 76 investors see Kinder Morgan as 12% undervalued.
Result: Fair Value of $37 (UNDERVALUED)
Still, the Kinder Morgan narrative depends heavily on moving more than US$10b of proposed gas projects to firm contracts and on large acquisitions avoiding weaker than planned returns.
Find out about the key risks to this Kinder Morgan narrative.
Another View on Kinder Morgan’s Valuation
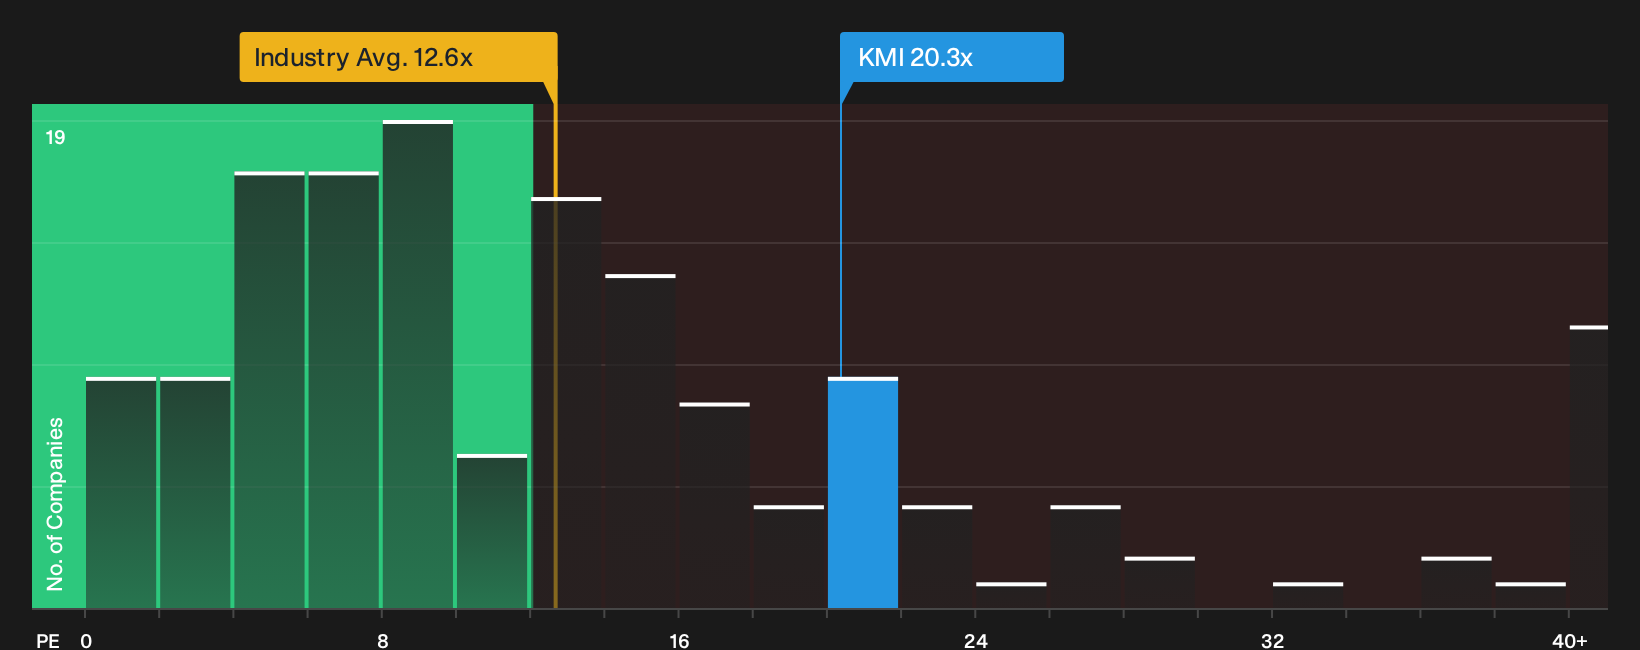
That 12% gap to fair value looks appealing at first glance, yet Kinder Morgan’s P/E of 20.3x is higher than the US Oil and Gas industry at 12.6x and slightly above peer levels near 19x. The fair ratio sits at 20.5x, so is the real risk that the multiple has already done a lot of the work?
To pressure test that view against the earnings-based approach, you can turn to the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals or early opportunity? Act quickly, review Kinder Morgan’s financials and sentiment data yourself, then weigh up the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Kinder Morgan?
If Kinder Morgan has your attention but you want a broader watchlist, use curated screeners to quickly surface fresh candidates that fit very different playbooks.
- Target reliable income by focusing on companies screened as potential 4 dividend fortresses that may appeal if you prioritize consistent payouts.
- Spot potential value setups early by reviewing a curated 34 high quality undervalued stocks before pricing moves away from you.
- Protect your downside first by zeroing in on a 29 resilient stocks with low risk scores that can help you keep volatility in check while you hunt for returns.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com